Diebold Nixdorf Edges Past Q3 Estimates, But A Sweeping Guidance Cut Shows Growth Isn't Translating Into Profit
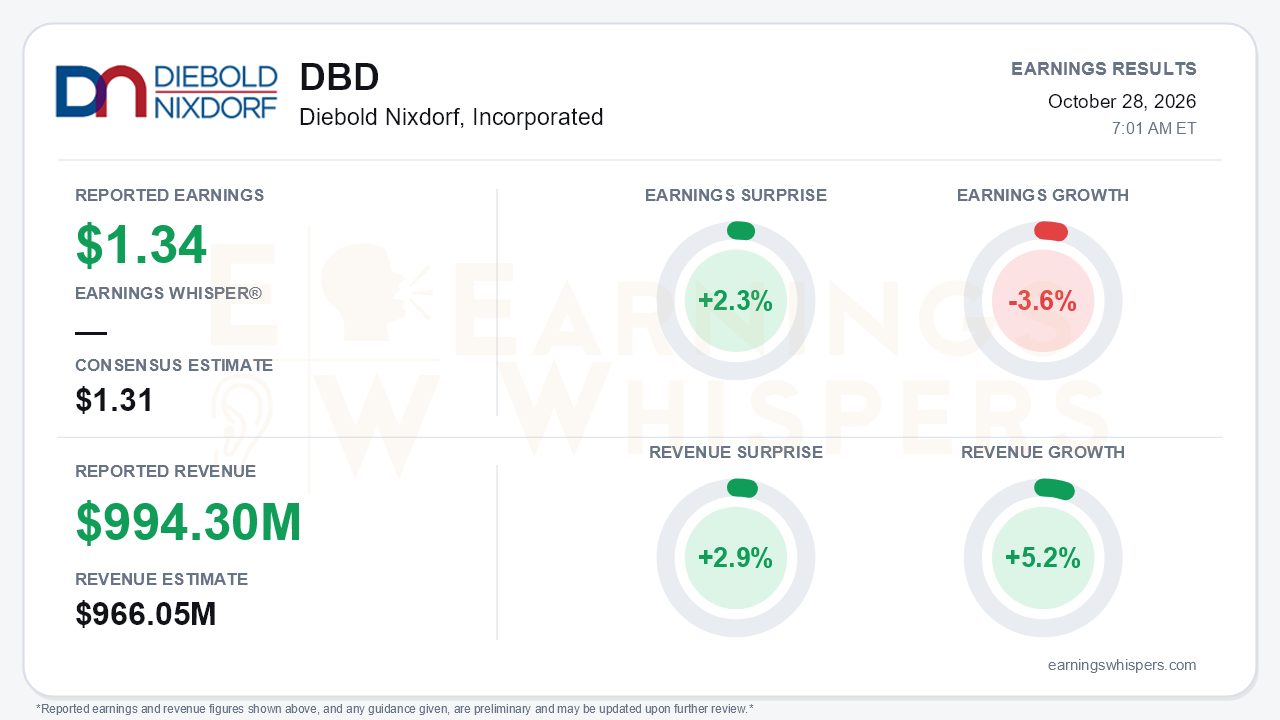
Diebold Nixdorf (NYSE: DBD) cleared a modest bar in the third quarter, but the beat matters less than what followed it. The company reported adjusted earnings of $1.34 per share, 2.3% above the $1.31 consensus. Revenue was $994.3 million, beating the $966.05 million estimate by 2.9% and rising 5.2% year over year. The call summary cited revenue of roughly $991 million, a small gap likely reflecting rounding or presentation differences. Earnings still fell 3.6% from a year ago despite higher sales. Management then cut full-year 2026 adjusted EPS guidance to $4.50-$4.85 from $5.25-$5.75. That is the central tension: the top line is growing again, but more revenue is producing less profit and less cash.
The quality of the quarter deserves scrutiny. GAAP gross profit rose only to $247.2 million from $245.1 million, and non-GAAP gross profit rose to $250.4 million from $247.9 million. Both were well short of the 5% revenue gain. Product gross margin fell 530 basis points year over year to 22.1%, down from 28.7% in Q2.
Retail was both the growth engine and the margin problem. The segment grew 16%, its fourth straight double-digit quarter, but retail gross margin dropped 400 basis points to 20.7%. Two factors drove the decline: a mix shift toward point-of-sale hardware, where volume more than doubled, and rising memory costs. Year-to-date, retail product margins have run around 15%, compared with roughly 30% in banking.
Service gross margin looked strong at 27.7%, up 230 basis points, but about 100 basis points came from a one-time tax credit of roughly $8 million. Adjusted EBITDA rose 5% to $128 million at a flat 12.9% margin.
The call showed a clear deterioration from Q2:
- **Memory costs:** In Q2, management had described memory costs as largely offset by tariff refunds and declining. They are now a roughly $25 million net headwind for 2026.
- **Cash flow:** Third-quarter free cash flow was negative $46 million. Management had guided to something similar to Q2's negative $11 million, and the result reverses an earlier goal of positive free cash flow every quarter.
- **Orders and backlog:** Backlog fell to $689 million from $814 million in Q2, and order entry moderated.
- **Banking:** Large banking tenders slipped again, and Middle East weakness weighed on the Asia-Pacific/Middle East/Africa region.
- **Margin targets:** Management abandoned its target of up to 50 basis points of service-margin expansion.
- **Tone:** Management moved from "on track" in Q2 to "more measured" and "not satisfied."
The guidance reset was broad:
- Adjusted EBITDA: $490-$510 million, down from $510-$535 million, a range set at the end of FY25 and reaffirmed twice.
- Free cash flow: $190-$210 million, down from $255-$270 million.
- Revenue: narrowed to $3.86-$3.90 billion, lowering the midpoint, with the Turkey banking exit now excluded.
- Cash conversion: 40%-45%, short of the earlier 50%-plus goal.
Management also declined to reaffirm its 2027 analyst-day targets. Bears have legitimate ammunition there: tougher European retail comparisons, about $30 million in higher German cash taxes and a pending debt refinancing all sit ahead.
The call did preserve a credible commercial story. Wins included:
- a 520-unit recycler order from one of the largest North American banks;
- a roughly 6,000-ATM managed-service contract with a major Spanish bank;
- a 6,000-lane self-checkout refresh with a European grocer and a 1,200-lane North American grocer;
- an early-stage ATM-outsourcing collaboration with Euronet.
SmartVision AI is on track for more than 1,000 retail deployments by year-end. Several margin levers are also in motion. Memory escalator clauses should cover about 95%-98% of contracts by the end of Q4, and renegotiated U.S. service contracts are expected to lift pricing starting in Q1 2027. Operating expenses fell 2%, the third straight decline, and guidance now calls for at least a 2% full-year decrease. The board authorized a new $250 million buyback, replacing the $200 million program. However, a larger buyback alongside a roughly 25% cut to free cash flow guidance will invite questions about capital priorities.
The market had already lost patience before the report. Shares closed at $66.68 the day before earnings, down 24.5% from the $88.32 open after the July report. That July open also marked the inter-earnings high. The stock was 11.2% below its 200-day moving average of $75.11. It had bounced 12.5% off a September 30 low of $59.28, but remained much closer to the bottom of its range than the top. Investor sentiment stayed positive but cooled, slipping to 0.14 from 0.22, a meaningful though not dramatic erosion. Earnings Whispers price and AVWAP trend readings were negative, though the sequential growth reading was positive, consistent with revenue that is reaccelerating while profitability lags.
The bottom line is that Diebold Nixdorf delivered a headline beat and a healthy-looking order pipeline, but the quarter showed that its fastest-growing business is diluting margins and that cost inflation and cash consumption were worse than management had signaled three months earlier. Until memory pass-through clauses, service repricing and banking tenders show up in margins and free cash flow, the guidance cut and the unconfirmed 2027 targets will likely weigh more heavily than the beat.
Read our earnings preview for Diebold Nixdorf, Incorporated: https://www.earningswhispers.com/article/DBD/20837
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-08 | |
| Oct-07 | |
| Sep-01 | |
| Aug-18 | |
| Aug-11 | |
| Aug-03 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 |
