Zurn Elkay Posts Record Margins And Lifts EBITDA Outlook, But Slowing Core Growth And A Softer 2027 Market Are The Real Story
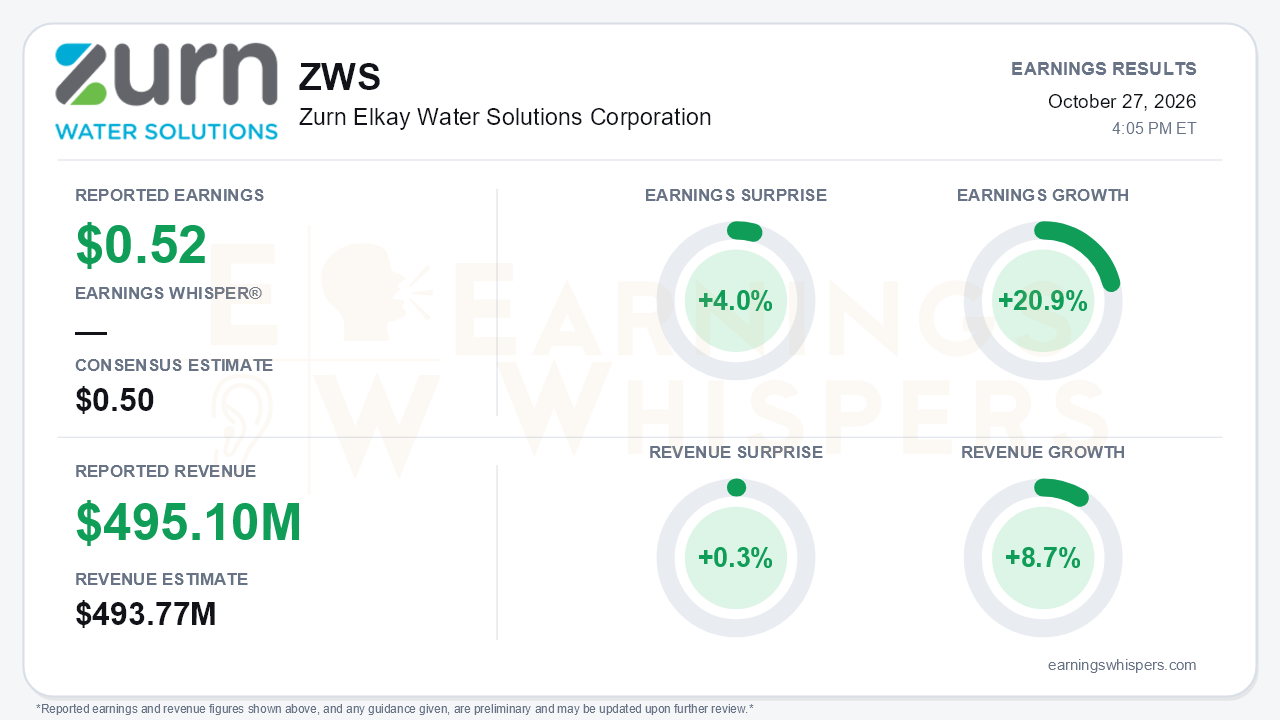
Zurn Elkay Water Solutions (NYSE: ZWS) delivered another clean beat in the September quarter, but the profit story and the growth story are moving in opposite directions. Adjusted EPS of $0.52 topped the $0.50 consensus by 4.0% and rose 20.9% year over year. Revenue of $495.1 million edged past the $493.77 million estimate by 0.3% and grew 8.7%. Management also raised full-year adjusted EBITDA guidance. That is the central tension: margins and cash generation keep improving while the top line normalizes. The fourth-quarter sales outlook came in below estimates, and management is now preparing investors for a shrinking end market in 2027.
The beat itself holds up well. Adjusted EBITDA rose to $140.1 million, and margin reached a record 28.3%, up 150 basis points from a year ago. That compares with 27.7% in the second quarter and 26.8% in the first, and it cleared the roughly 28% the company had guided. Gross profit climbed to $245.8 million on lower cost of sales, and GAAP operating margin expanded 490 basis points. Management credited product mix, productivity initiatives, and supply chain repositioning. Part of that GAAP improvement reflects an $11.2 million LIFO charge in the year-ago quarter that did not recur. Importantly, the IEEPA tariff refunds that inflated year-to-date GAAP results ($49.1 million over nine months, $1.5 million in the quarter) are stripped out of adjusted EBITDA and adjusted EPS, so the non-GAAP beat was not refund-driven. GAAP diluted EPS from continuing operations rose to $0.45 from $0.35, despite a much smaller other-income contribution than last year. Free cash flow of $110 million excludes refunds and funded $35 million of buybacks. After the $107 million Intellihot acquisition, net leverage sits at just 0.4x, which leaves ample room to support the 18% dividend increase to $0.52 annually.
Beneath the headline, revenue momentum is clearly fading:
- **Core growth:** 11% in the first quarter, 10% in the second, 7% in the third, with mid-single digits implied for the fourth. Management noted the third quarter landed at the high end of its 6-7% guide.
- **Pricing:** Price contribution fell from about 5 points to roughly 2 points as the tariff-related price carryover fully cycled.
- **Acquired growth:** Intellihot added about 2 points, or roughly $6 million, so organic volume is still growing but moderating.
- **Fourth-quarter outlook:** Net sales of $430-$437 million and adjusted EBITDA of $120-$123 million imply that margins stay near 28% even as growth cools.
- **Full year:** The EBITDA range moved up to $512-$515 million from $503-$513 million. The free cash flow target of more than $350 million was held.
The call's tone shifted toward resilience. The conference-call analysis characterized the language as "grit," and management said the broader economy is not a tailwind. It now frames the 2027 market as likely down a couple of points, softer than its flat-to-slightly-positive view of 2026. The Architecture Billings Index has stayed below 50 for an extended period, residential remains weak, and some project delays were noted. Rising inflation and interest-rate spikes were flagged as risks. Offsetting this, backlogs are stable at roughly eight-plus months, the Dodge Momentum Index sits at the high end of its range, and Dodge forecasts education and healthcare starts improving to a 3% CAGR after a 4% decline.
Management's answer to a softer market is self-help and adjacency expansion. It set a 40%-plus incremental margin framework for 2027, a step up from 35% in the initial 2026 guide and about 40% cited last quarter. It also expects at least $5 million of additional EBITDA benefit from supply chain actions. The company launched the internally developed Wilkins Runpoint digital master mixing valve. Management sizes that market at more than $200 million and is targeting it as a $50 million long-run category, sold through existing Wilkins channels. Combined with Intellihot and a planned IntelliPro services network, management says it has expanded served markets by roughly $400 million in 2026, with more $100-$200 million adjacency launches planned for 2027. These are credible levers, but they remain early-stage and are unproven at scale.
The market had already been pricing in the slowdown. Shares closed at $49.15, down 9.7% from the open after the July report, despite record margins in the interim. The stock sits just 1.7% above its 200-day moving average of $48.32, a thin cushion. Investor sentiment improved modestly, moving from slightly negative (-0.04) to slightly positive (0.08). That signals a less skeptical crowd rather than an enthusiastic one. Earnings Whispers trend readings are mixed, with the price trend negative while AVWAP is positive.
The bottom line is that Zurn Elkay keeps proving it can expand margins and generate cash faster than its top line grows. However, decelerating core growth, fading price, a below-consensus fourth-quarter revenue outlook, and an expected 2027 market decline give bears legitimate ammunition. The next leg of the story depends on whether 40%-plus incrementals and new adjacencies can offset a shrinking market. Until volumes stabilize, the stock's sideways-to-lower drift reflects a reasonable degree of caution.
Read our earnings preview for Zurn Elkay Water Solutions Corporation: https://www.earningswhispers.com/article/ZWS/20812
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-14 | |
| Sep-02 | |
| Aug-03 | |
| Jul-29 | |
| Jul-28 | |
| Jul-23 | |
| Jul-20 | |
| Jul-15 | |
| Jun-15 | |
| May-27 | |
| May-26 | |
| Apr-30 |
