Slide Insurance Crushes EPS Consensus And Lifts Profit Outlook, But Premium Growth Has Slowed To A Crawl
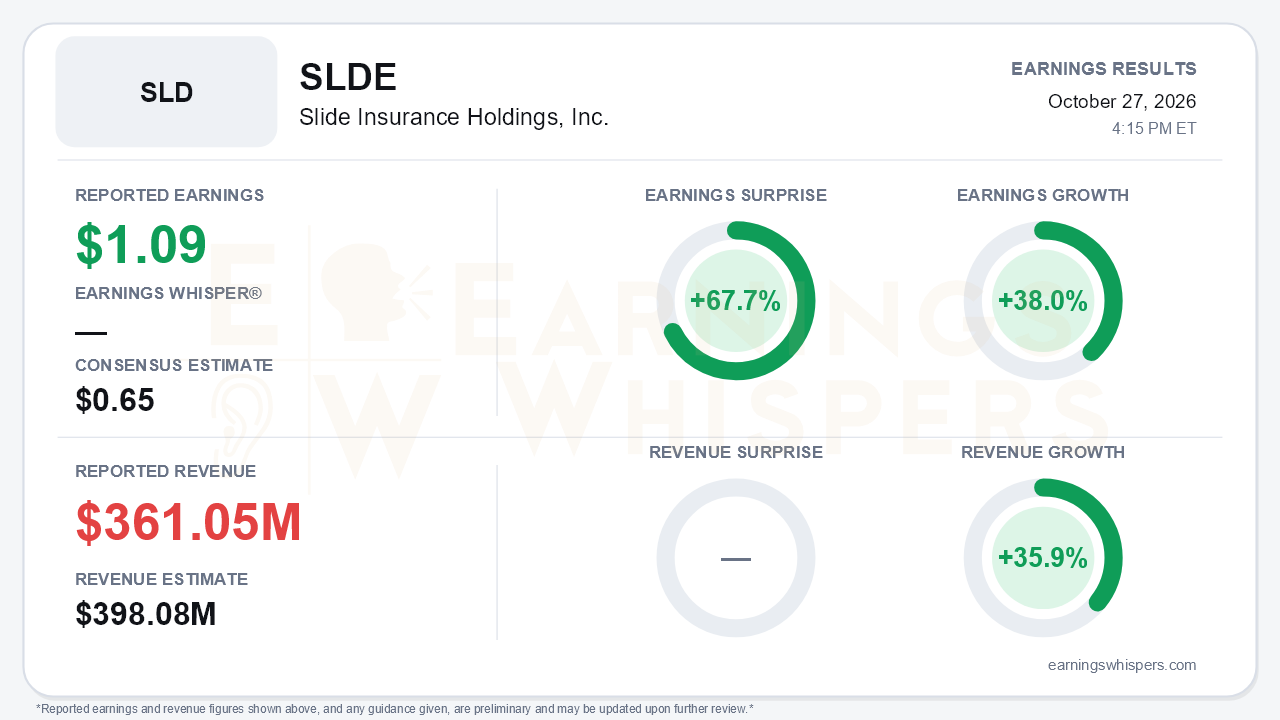
Slide Insurance Holdings delivered a large bottom-line beat for the third quarter. It earned $1.09 per share against a $0.65 consensus, a 67.7% surprise, and EPS grew 38.0% year over year. Revenue rose 35.9% to $361.05 million but still missed the $398.08 million consensus by 9.3%. That split frames the quarter. Slide is producing more profit per dollar of premium than expected while its top-line engine is slowing quickly. Management answered with a roughly 10% increase to full-year net income guidance, a $1.50 special dividend and a much larger credit facility. Those moves shift the story from organic premium growth toward capital deployment.
The quality of the beat deserves scrutiny. Net income rose 24.5% to $138.2 million, but pre-tax income grew more modestly, to $161.7 million from $147.0 million. Three items widened the gap between pre-tax and per-share results:
- **Tax:** the Q3 tax rate was roughly 14%, which management attributed to a one-time catch-up.
- **Share count:** diluted shares fell to 127.1 million from 140.1 million.
- **Reserves:** $18.0 million of favorable prior-period reserve development flattered results, though that was down from $32.5 million a year ago.
The reported combined ratio deteriorated to 59.3% from 48.5% a year earlier and 57.5% in Q2. The main cause was $34.2 million of Florida convective-storm catastrophe losses, which added about 10 points.
Beneath the noise, underwriting improved. The accident-year loss ratio excluding catastrophes and reserve development fell to 25.5% from 27.5%. The ex-cat accident-year combined ratio dropped to 54.4% from 62.3%. Those are strong margins for a coastal property writer, and they explain why management could raise guidance. The expense ratio is the caveat. It improved year over year to 28.9% from 34.8%, but it has climbed sequentially from 25.1% in Q1 and 27.4% in Q2. Management guided it to about 28.5%-29%, which suggests the H1 run-rate will not return soon.
The weaker thread is growth. Gross premiums written rose 9.3% to $506.6 million, flat sequentially. That compares with 16.7% growth in Q2, 49% in Q1 and 57% in Q4 FY25, as Citizens takeouts faded. Management framed initial 2027 premium growth at only about 8%-9%, back-end loaded and dependent on regulatory ramps in new states. The expansion footprint is real:
- California E&S launched in May.
- South Carolina is expanding.
- Texas went live this quarter.
- New York and New Jersey are expected next quarter.
Execution timing has slipped, however. New York was hoped for in Q3, and California, once pitched as a $50-$100 million opportunity this year, was described only as "ramping." Raising the low end of 2026 GWP guidance to $1.90-$1.95 billion narrows the range but does not change the deceleration.
That is why the capital-allocation news may matter more than the beat. The new $1.07 billion credit facility replaces a $530.4 million agreement and is earmarked for ex-Florida growth and acquisitions. Management cited a "shift in the market" and the potential for something "transformative" into 2027, a notable change from Q2, when it called target prices too high. A large deal could restart growth, but it also brings integration and pricing risk. Cash and equivalents fell to $700.6 million from $1.24 billion at June 30. Near term, the new full-year net income range of $500-$520 million already absorbs up to $50 million of pre-tax Hurricane Isaias retention in Q4. Management also expects benign reinsurance pricing because Isaias will not reach its reinsurance panel. The lower 21.5%-22% tax-rate outlook adds further support.
Investor sentiment remained negative but improved modestly, moving to -0.117 from -0.176. That is a cautious crowd despite a powerful rally. Shares have gained 32.0% since the open after the July report and sit about 42% above their 200-day moving average. The AVWAP trend reading is positive. So the market has already rewarded the margin story well ahead of this print, which raises the bar for evidence that growth can re-accelerate.
The bottom line is that Slide's quarter was stronger on profitability than on growth. Ex-cat underwriting margins improved sharply, guidance moved meaningfully higher and shareholders are getting cash back. But part of the EPS beat came from tax, buybacks and reserve releases, and premium growth has slid from 57% to 9% in a year with only 8%-9% pencilled in for 2027. Bulls can point to a highly profitable book and a well-funded acquisition pipeline. Bears have legitimate ammunition in the revenue miss, the rising expense ratio and slipping state launches. With the stock well extended above its long-term average, the next leg likely depends on whether management can turn its new borrowing capacity into growth.
Read our earnings preview for Slide Insurance Holdings, Inc.: https://www.earningswhispers.com/article/SLDE/20798
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-01 | |
| Sep-23 | |
| Sep-21 | |
| Jul-29 | |
| Jul-28 | |
| Jul-27 | |
| Jul-13 | |
| May-04 | |
| Apr-28 | |
| Apr-28 |
