OppFi Misses Again As Third Guidance Cut And Rising Charge-Offs Overshadow Product Pipeline
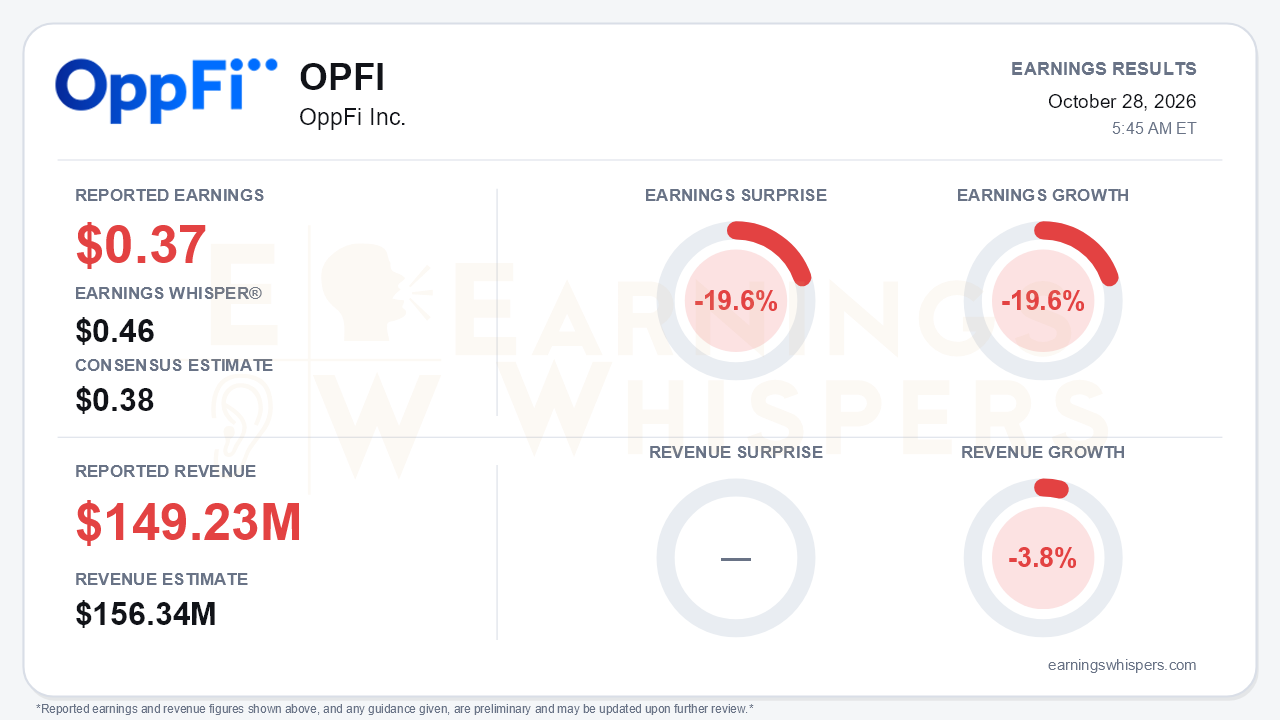
OppFi's third quarter fell short on both lines, and guidance moved lower again. Adjusted EPS of $0.37 was a penny below the $0.38 consensus but well short of the $0.46 Earnings Whisper number, a 19.6% miss against the expectation that mattered most to investors. Earnings fell 19.6% from a year ago. Revenue of $149.23 million missed the $156.34 million consensus by 4.5% and declined 3.8% year over year. That decline continues a clear slide: revenue grew roughly 8% in the first quarter and 1.9% in the second before turning negative now. Earnings Whispers characterizes the outlook as narrowed. That is accurate, but the narrowing came entirely from the top of the range. Full-year adjusted EPS guidance is now $1.34 to $1.40, against $1.34 to $1.51 in August and $1.76 to $1.84 at the start of the year. This is the central tension: management keeps expanding the product roadmap while the core lending engine shrinks and the earnings bar keeps dropping.
The quality of the quarter deserves scrutiny beyond the modest consensus shortfall. Credit is the main problem:
- Annualized net charge-offs rose to 52.6% of average receivables from 46.7% a year ago.
- Charge-offs consumed 40.1% of revenue versus 35.1%.
- The negative fair-value adjustment on receivables widened to $56.5 million from $50.5 million, pushing net revenue down 11.3%. That is roughly three times the decline in gross revenue.
The loan book is also contracting:
- Net originations fell 6.8%.
- Retained originations fell 11.4%.
- Ending receivables declined 4.7%.
- Average yield slipped to 131.4% from 133.2%.
Cost discipline in marketing, salaries and interest expense was offset by higher professional fees, technology and G&A, and operating income fell 23.5%. GAAP net income dropped to $34.5 million from $75.9 million. Most of that drop reflects a $31.7 million warrant gain in last year's quarter rather than core deterioration, but the adjusted numbers confirm the downtrend on their own.
The call added little to offset that picture. Management attributed the origination weakness to tighter screening criteria at marketing partners. It also cited higher-for-longer inflation and weak consumer sentiment behind elevated losses. The CEO described himself as more cautious than most. There were sequential bright spots:
- Originations improved to $229 million from $212 million in the second quarter.
- Adjusted EPS rose from $0.33.
- Recoveries held near $15 million versus $11 million a year earlier.
The guidance math tempers that, however. With $1.05 of adjusted EPS through nine months, even the top of the new range implies a fourth quarter below the third.
The forward story rests on a long list of initiatives:
- **Line of credit:** launched in the quarter after a roughly two-month delay, now scaling in new geographies.
- **Model 7:** the new underwriting model is slated for a fourth-quarter launch, with a 20% improvement in pre-screen alignment.
- **Pricing Test 5:** the company's largest rate and payment reduction to date, expected to support originations into 2027.
- **LOLA platform:** now handles all new originations.
- **Bitty:** surpassed $1 billion in cumulative funding.
- **Earned wage access:** under evaluation for 2027.
Management also reaffirmed its target of roughly $3 in EPS by the end of 2028. Bears have legitimate ammunition here, though. Pricing Test 5 and an explicit willingness to give up yield for better-quality borrowers could pressure revenue before any credit benefit appears. The BNCC bank acquisition cleared its stockholder vote on September 17, but closing may slip from the fourth quarter into the first quarter of 2027 pending regulatory approval. OppFi also drew $75 million on a Castle Lake facility at roughly 12%, lifting total debt to about $350 million. Liquidity is stronger as a result, with $140.7 million in cash and restricted cash and about $691 million in funding capacity. That flexibility is expensive, however.
Investors were already bracing for disappointment. Earnings Whispers sentiment moved further into negative territory, from -0.418 to -0.494. That is a meaningful but not dramatic deterioration. The stock tells a starker story. Shares closed at $5.45 before the report, down 27.3% from the $7.50 open after the August release and 34.3% below the 200-day moving average of $8.30. The stock sat just 1.7% above a fresh 52-week low of $5.36 set on October 26, after peaking at $8.07 in September. The $17.9 million in year-to-date buybacks were executed at an average of $8.91, well above where the stock now trades. The Earnings Whispers trend readings are mostly negative across price, momentum and AVWAP. Sequential growth is the lone positive, consistent with the quarter-over-quarter improvement in originations and EPS.
The bottom line is that OppFi delivered another quarter of shrinking revenue, rising charge-offs and a lower ceiling on full-year earnings, while its growth case shifts further into 2027 and beyond. The product pipeline is real and the balance sheet is more liquid. Even so, the company now needs pricing cuts, a new underwriting model, a new credit product and a delayed bank deal to reverse a downtrend that management has not yet stopped. With the stock near its lows and sentiment souring, the market is clearly demanding evidence over roadmap.
Read our earnings preview for OppFi Inc.: https://www.earningswhispers.com/article/OPFI/20869
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 8 hours | |
| Oct-19 | |
| Oct-02 | |
| Sep-17 | |
| Aug-25 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Aug-04 | |
| Jul-28 | |
| Jul-17 | |
| May-27 | |
| May-27 |
