Jersey Mike's Beats On EBITDA And Returns Capital Fast, But Comp Guidance Loses Its Ceiling
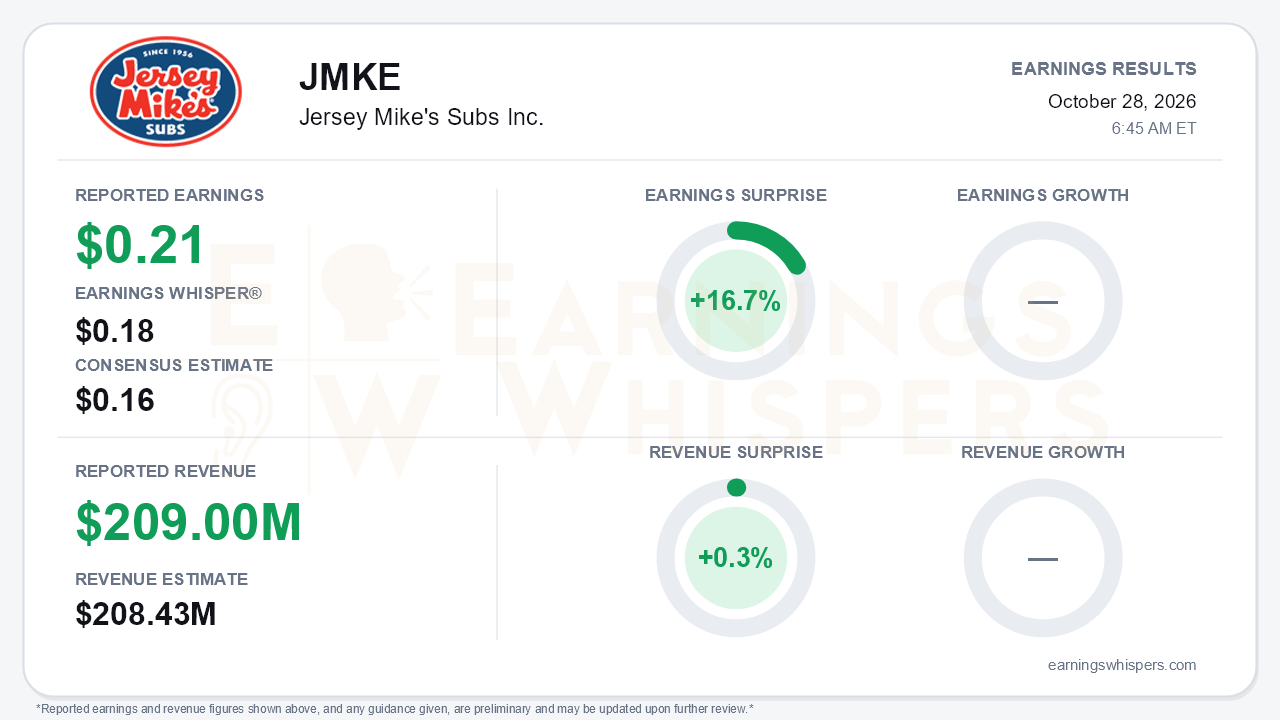
Jersey Mike's Subs (NYSE: JMKE) delivered a clean beat in its first quarter as a public company. Earnings Whispers puts fiscal third-quarter earnings at $0.21 per share, against a $0.16 consensus and an $0.18 Whisper number, a 16.7% surprise. Revenue of $209.0 million rose 10% and edged past the $208.43 million consensus by 0.3%. The company also announced roughly $200 million in capital returns, made up of a $100 million buyback and a $0.35 special dividend, less than three months after its July 31 IPO. Beneath that, the demand story is more measured. Same-store sales of 3.0% came in at the bottom of the 3-4% range management guided on its prior call. The full-year comp outlook also moved from 2.5-3% to "at least 2.5%," which drops the upper bound. That is the central tension: profitability and capital allocation are running ahead of plan, while the top-line engine is merely holding steady.
The earnings figures need some translation. The company's own Adjusted EPS was $0.23, a newly introduced metric. It assumes full exchange of common units and a 25% tax rate, and it excludes $25 million of acquired-intangible amortization. GAAP results were far weaker. Net income fell to $10 million from $32 million, and Class A shareholders absorbed a $0.05 diluted loss for the post-IPO stub period. The drivers were a $29 million one-time equity compensation charge tied to the IPO and $17 million of IPO-related professional fees, partly offset by a $7 million gain on selling company-owned stores. Adjusted EBITDA grew 20% to $125 million, well above the call guide of at least 13%. The quality of that beat deserves scrutiny, though. About $5-6 million of the upside came from ad-fund timing. Another $9 million came from lower costs following the completed Area Director buyouts, a tailwind that laps through 2027. Underlying operations were still healthy. Royalties rose 12%, and adjusted G&A slipped to $31 million from $33 million.
The operating trend line is better than the guidance optics suggest. Comps have accelerated from 1.7% in the first quarter to 2.3% in the second and 3.0% in the third, with transactions leading for a third straight quarter. Gross openings jumped to 80 from 54 a year ago, net unit growth held near 9%, and the system reached 3,456 stores. Catering grew 17% year to date and now exceeds 4% of the mix, against a long-term target of up to 10%. Not every metric moved forward, however. Digital mix gains slowed to about 100 basis points, and loyalty sign-up growth eased slightly to 21%. Average unit volume of $1.386 million remains a long way from the $2 million goal.
The most telling shift was in tone on the consumer. Management acknowledged industry-wide softness late in the quarter tied to weaker consumer sentiment. It then launched a $7.99 digital-only mini sub and chips bundle, a notable pivot from its earlier stance that the brand did not need value offers. Management describes the bundle as margin-friendly for franchisees, and franchisee margins were said to be improved year over year. Still, a premium sandwich chain leaning into value is a signal worth watching. An analyst also noted that the fourth-quarter comp guide implies slower two- and three-year stacked trends. Other forward items cut both ways:
- **Catalysts:** the first UK store opening within weeks and more international partners expected over the next 6-12 months.
- **Risks:** the Middle East was flagged as challenging, a distributor consolidation toward Performance carries execution risk, and Walmart's entry into restaurant delivery could reshape the aggregator landscape.
The balance sheet supports the capital-return story. Operating cash flow reached $177 million through three quarters against just $7 million of capex. IPO proceeds paid down debt, net leverage fell to 3.9x from about 4.4x, and fourth-quarter interest expense is guided to roughly $25 million, down from about $28 million. Bears can point to $1.8 billion of debt and a $1.37 billion tax receivable agreement liability. Returning capital this quickly at that leverage is a choice, not a free lunch.
The market had not been kind going into the print. Shares closed at $16.96 before the report, 15.1% below the 200-day moving average of $19.98. That is also well under the $21.50 average closing price since the IPO that the company cited in its share-count math. Investor sentiment stood at -0.25, modestly negative, and Earnings Whispers trend readings tilt more negative than positive. The setup is more complicated than the surprise implies. A beat on the quarter's earnings figures and an EBITDA growth outlook of at least 20% were not enough to quiet worries about comp durability.
The bottom line is that Jersey Mike's delivered the profitability, unit growth and cash generation a franchisor IPO is supposed to show, and backed it with an aggressive capital return. The quarter left the demand question open. A comp at the low end of guidance, a guidance range that lost its ceiling, a new emphasis on value, and an EBITDA tailwind that will fade all suggest growth is steady rather than inflecting. With the stock trading well below its post-IPO levels, upcoming quarters will need to show that transaction-led comps can hold up without leaning on discounts.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-14 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 |
