CTO Realty Growth Beats And Lifts Guidance Again, But Growth Now Leans On Deals As Same-Store Momentum Cools
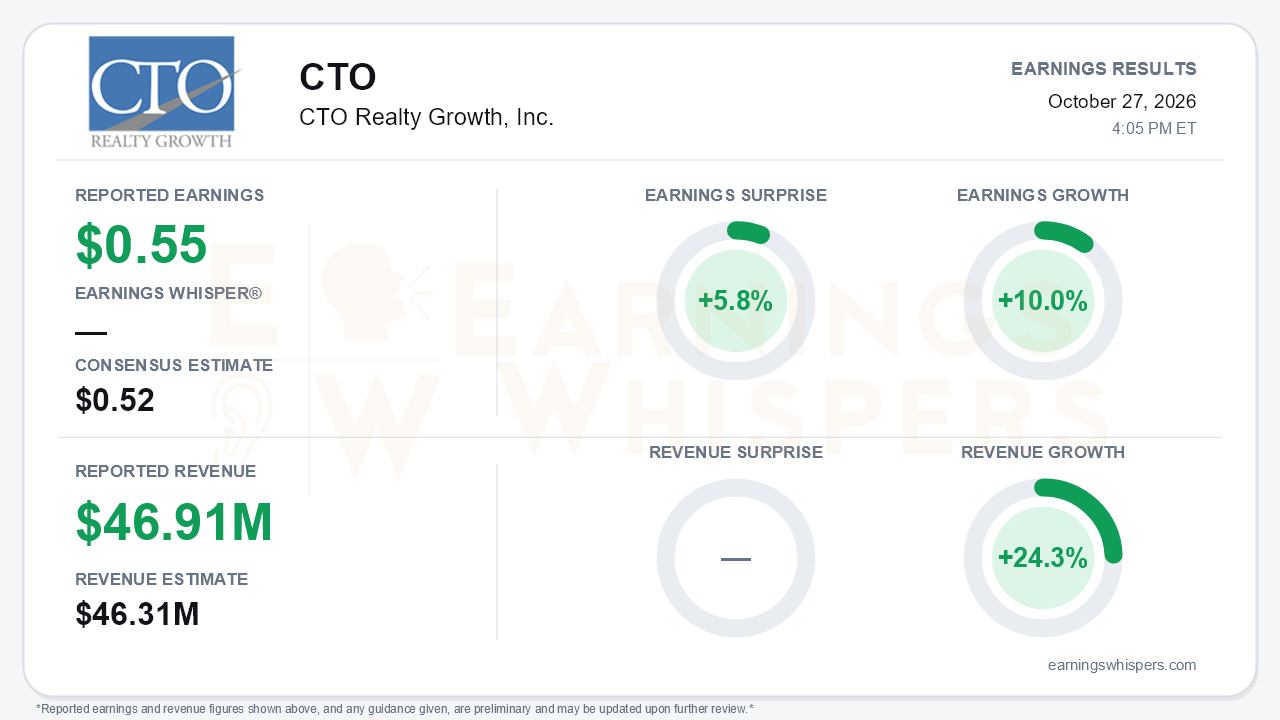
CTO Realty Growth delivered another beat-and-raise quarter, reporting third-quarter earnings of $0.55 per share against a $0.52 consensus, a 5.8% surprise. Revenue of $46.91 million topped the $46.31 million estimate by 1.3% and rose 24.3% year over year, while earnings grew 10.0%. Management raised 2026 Core FFO guidance for the third straight quarter, to $2.11-$2.14 from $2.09-$2.13, and lifted the low end of AFFO guidance to $2.22. The headline is clean. The central tension sits underneath it: CTO's growth engine is shifting from organic leasing gains toward acquisitions, structured lending, and balance-sheet capacity. That shift is happening while the stock trades below the level that makes equity funding comfortable.
The quality of the quarter deserves a closer look. Core FFO was $0.53 per diluted share, up from $0.48, and AFFO was $0.55, up from $0.50. On a GAAP basis, however, CTO posted a net loss of $0.19 per share, compared with a $0.03 profit a year earlier. The swing came largely from a $9.8 million realized and unrealized loss on investment securities, which is excluded from FFO.
More telling is the revenue mix:
- Interest income from commercial loans and investments more than doubled, to $6.9 million from $3.1 million.
- Income-property revenue grew a more modest 15%, to $38.5 million.
- Structured investments now total roughly $260 million at a 12.1% yield.
- That book includes a new $32 million preferred equity position yielding 17%, of which 7% is paid-in-kind.
- PIK interest earned but not yet paid in cash reached $224,000 in the quarter.
Those are high-yield, accretive investments, but they carry more credit risk than rent from a grocery-anchored center. The per-share gains also came despite diluted share count rising about 15% year over year after $125 million of ATM issuance.
The call made clear that organic momentum has cooled, as management had flagged on the prior call. Shopping center same-property NOI growth slowed to 3.8% from 10.1% in the second quarter as anchor openings lapped, though full-year guidance held at 5%-6%. Comparable cash rent spreads moderated to 7% from 14% in the first quarter and 24% for fiscal 2025. The signed-not-open pipeline slipped to $5.6 million, or 4.6% of base rent, from $6.3 million as the State of New Mexico began paying rent in Albuquerque. Including the 67%-leased Zona Rosa acquisition, total leased occupancy fell to 92.4% from 95.4% in the second quarter. Excluding Zona Rosa, occupancy edged up to 95.7%, and same-property shopping center occupancy improved 90 basis points year over year to 95.8%. The leasing story is also largely de-risked: all 11 vacated anchor boxes are resolved, with nine re-leased at roughly 70% spreads and two sold for $20.7 million.
The forward catalysts are mostly external. Year-to-date investment volume reached $472 million at a 9.4% weighted average yield, far above the initial $100-$200 million plan. The Kansas City entry through Zona Rosa and Summit Woods Crossing made Dick's and Best Buy the two largest tenants. Zona Rosa, bought at $82 per square foot with about 250,000 square feet of vacancy, gives CTO a lease-up runway.
The new $1.0 billion unsecured facility was a meaningful improvement:
- Weighted average debt maturity extended to 4.3 years from 1.6 years.
- The nearest maturity is now September 2029.
- Liquidity rose to about $255 million from $131.8 million.
Bears still have legitimate ammunition:
- Leverage is expected to climb to roughly 6.5x from 5.9x after fourth-quarter deals.
- A $100 million swap rolls up about 180 basis points in 2027.
- The Harkins space faces roughly 12 months of downtime.
- Disposition cap rates have widened 25-30 basis points.
- The Albuquerque sale slipped into 2027.
- G&A guidance rose to $21.0-$21.5 million.
- Management acknowledged that a sub-$20 stock shifts funding toward asset recycling.
The market had already turned skeptical. Shares have fallen 12.3% since opening at $22.17 after the July report, closing at $19.45, about 3.8% below the 200-day moving average of $20.21. Investor sentiment swung sharply, from a moderately positive 0.32 to a negative -0.43. That is a substantial deterioration for a company that has raised guidance all year. The AVWAP trend reading is negative, consistent with the stock's slide. The fact that the raised guidance only matched existing estimates helps explain why the beat may not reset the narrative on its own.
The bottom line is that CTO is executing well on what it controls, with steadily higher guidance, a cleared anchor backlog, a stronger debt maturity profile, and a large, high-yielding investment pipeline. But the quarter marks a transition from organic re-leasing gains to growth funded by rising leverage and higher-risk structured investments, at a share price that constrains equity issuance. Until same-store growth stabilizes or the stock regains its cost-of-capital footing, investors appear inclined to discount the guidance raises rather than reward them.
Read our earnings preview for CTO Realty Growth, Inc.: https://www.earningswhispers.com/article/CTO/20750
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 8 hours | |
| Oct-27 | |
| Oct-08 | |
| Oct-06 | |
| Sep-30 | |
| Sep-25 | |
| Sep-24 | |
| Sep-16 | |
| Sep-14 | |
| Aug-19 | |
| Jul-30 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 |
