Dana's Margin Momentum Collides With A Steep EPS Miss And Flat Profit Guidance
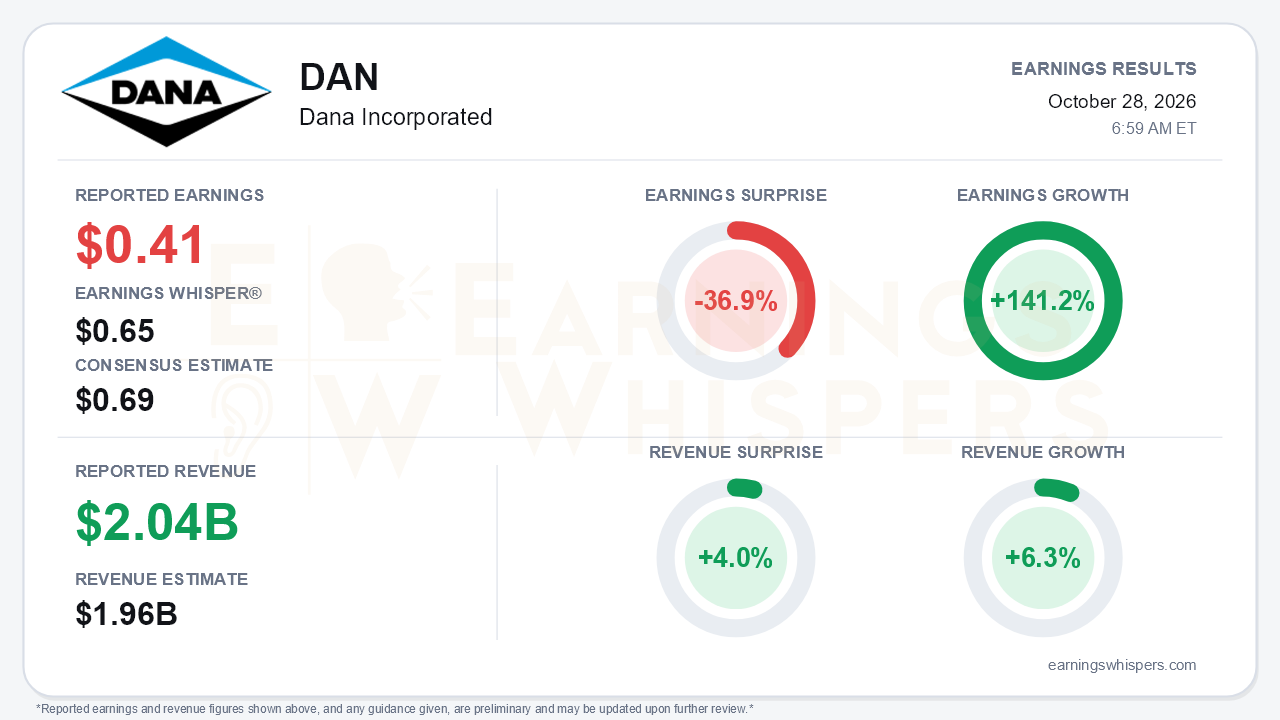
Dana Incorporated delivered an awkward quarter: its operating results improved, but the earnings number fell short. Adjusted earnings of $0.41 per share missed the $0.69 consensus by 36.9% and came in well under the $0.65 Earnings Whisper number. Revenue of $2.038 billion beat the $1.96 billion consensus by 4.0% and grew 6.3% year over year. Adjusted EPS grew 141.2%, a swing from an adjusted loss of $0.04 a year ago. The central tension is that Dana posted its best margin quarter of 2026 and raised its sales outlook again, yet left its EBITDA, EPS and free-cash-flow targets unchanged. Management also flagged an inflation burden that the company cannot contractually pass through to customers.
The operating improvement was real. Adjusted EBITDA rose $56 million to $218 million, and margin reached 10.7%, up 220 basis points from a year earlier. That continues a clear sequential climb from 9.2% in the first quarter and 10.3% in the second. Commercial Vehicle drove the top line, with sales rising to $667 million from $564 million and segment EBITDA climbing to $69 million from $51 million. Light Vehicle sales were roughly flat at $1.371 billion, but segment EBITDA improved to $151 million from $126 million on cost actions. The GAAP picture was messier. Continuing operations lost $0.13 per share, burdened by a $24 million loss on debt extinguishment and a $29 million foreign tax settlement charge. Cash flow also weakened. Adjusted free cash flow fell to $66 million from $101 million, as the divested Off-Highway cash stream disappeared and capital spending rose.
The call explained where the momentum is coming from. Volume and mix added $87 million to sales, compared with $6 million in the second quarter and a $33 million drag in the first. Stronger commercial vehicle demand and backlog conversion finally showed up in the numbers. Management marked up its North American Class 5-7, bus and Class 8 outlook relative to the March Capital Markets Day, only a quarter after it had flagged softness in Class 5-7 and bus. The cost program has delivered $320 million of a $325 million goal, against an original $200 million target. Automation is contributing roughly $20 million in run-rate savings, with 56 more deployments planned. Full-year sales guidance has now moved from $7.5 billion to $7.75 billion to roughly $7.8 billion.
The weaker signals sit inside the profit guidance. Adjusted EBITDA guidance held at $800-$850 million, and diluted adjusted EPS remained at $1.75-$2.25, a range that was already cut from $2.50 in the second quarter. With nine-month adjusted EPS at $0.74, that range leaves a demanding fourth quarter. Management described general inflation in energy and freight as a 'nine-digit' headwind without contractual recovery. The performance contribution in the full-year EBITDA bridge shrank to about $95 million from about $125 million, with higher volume and mix filling the gap. The implied fourth quarter shows roughly $15 million of volume and mix on sales but no EBITDA conversion. Other pressures include softness on some North American light vehicle platforms, aftermarket weakness in Europe, the Middle East and Asia, and higher union labor costs. Bears have legitimate ammunition.
The forward story rests heavily on capital allocation and the Eaton Mobility combination. Dana repurchased $200 million of stock in the quarter and plans about $100 million more in the fourth quarter, lifting the 2026 total to $469 million from an original $300 million. The Eaton deal has every regulatory approval but one. A shareholder vote is set for December 7, and closing is targeted around the end of the first quarter of 2027. Management discussed revenue synergies explicitly for the first time and expects margins to step up again in 2027. However, pro forma leverage at close is now cited at 1.6x rather than 1.4x. Transaction costs of about $250 million plus roughly $200 million to achieve synergies are ahead, and whether buybacks resume after the close remains undecided.
The market had already been leaning skeptical. Earnings Whispers investor sentiment slipped from a mildly positive 0.18 to a roughly neutral -0.03, a meaningful cooling. Shares entered the report at $27.20, down 8.0% since the open after the August release and 12.8% below the 200-day moving average. They sat just 3.7% above the inter-earnings low set on October 23 and 15.8% below the September 4 high. The trend signals lean negative, with price, sequential growth and AVWAP readings all weak, although momentum remains positive.
The bottom line is that Dana's quarter was better operationally than the headline miss implies. It showed accelerating volume, a fresh high in margin and a credible commercial vehicle upcycle. Even so, the large EPS shortfall, unchanged profit guidance and an unrecovered inflation burden suggest margin gains are becoming harder to convert into earnings upside. With the stock near its quarterly low and sentiment cooling, the setup now depends on Dana proving it can deliver its fourth-quarter targets and close Eaton cleanly.
Read our earnings preview for Dana Incorporated: https://www.earningswhispers.com/article/DAN/20835
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-07 | |
| Sep-08 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-21 | |
| Jul-20 | |
| Jul-02 | |
| Jun-25 | |
| Jun-22 | |
| Jun-18 |
