Littelfuse Posts 96% EPS Growth As Organic Sales Accelerate To 22%; Dortmund Fee Drives Revenue Miss, Margin Durability Becomes The Debate
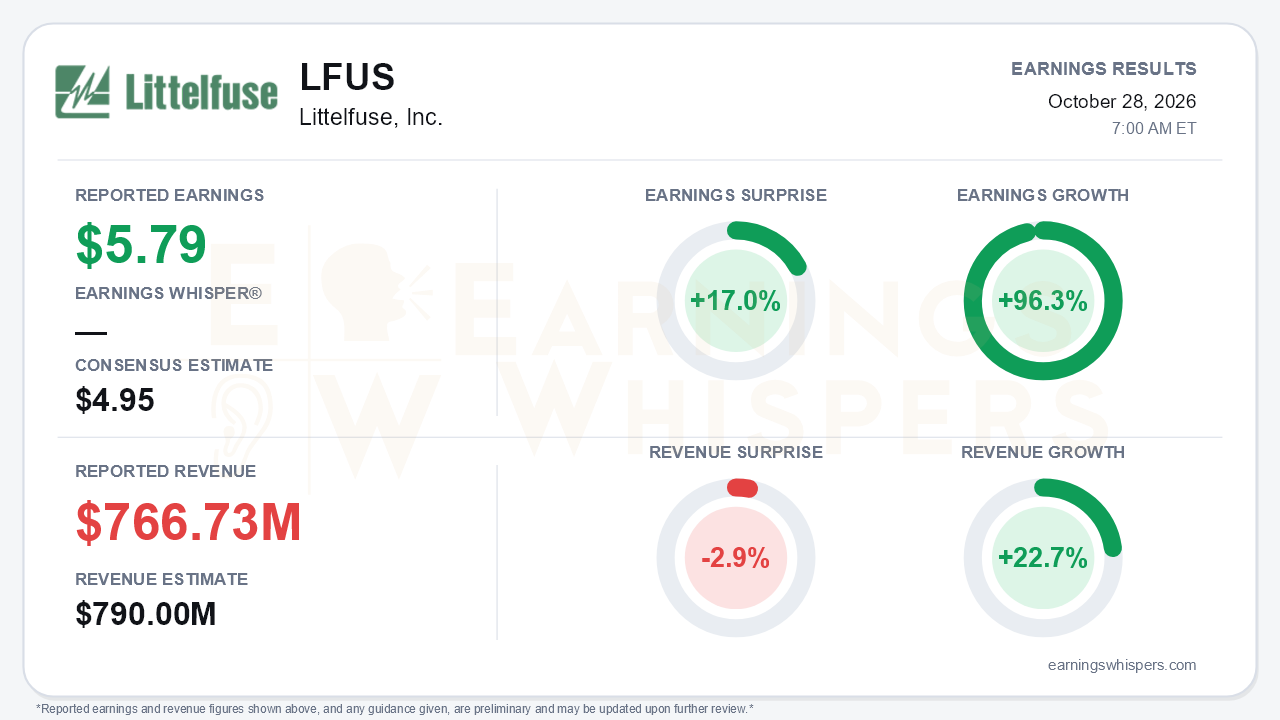
Littelfuse delivered a large earnings beat that its reported revenue line understates. Adjusted EPS of $5.79 topped the $4.95 consensus by 17.0%, grew 96.3% year over year, and cleared management's own $4.85-5.05 guidance range by a wide margin. Revenue of $766.73 million rose 22.7% but missed the $790.0 million consensus by 2.9%. The miss is almost entirely an accounting artifact. A one-time $28.5 million Dortmund contract amendment fee was booked as a reduction of semiconductor sales. Excluding it, adjusted net sales were $795.2 million, inside the top half of the $780-800 million guide. The central story is that growth and profitability are still accelerating. The open question has shifted from whether the recovery is real to how much of this margin profile can last.
The beat still deserves scrutiny. GAAP diluted EPS was $4.49, up 62%. The $1.30 gap to adjusted EPS is far wider than the $0.18 gap a year ago, because adjusted results add back the Dortmund fee along with $6.2 million of restructuring charges and $3.5 million of acquisition costs. The adjusted tax rate also fell to 21.8% from 24.6%, a modest tailwind relative to the roughly 24% assumed for the fourth quarter. Even so, the operating improvement is clearly genuine on a GAAP basis:
- GAAP operating margin expanded 440 basis points to 20.0%.
- Operating cash flow rose 57% to $230 million.
- Free cash flow reached $216 million, up from $127 million in the second quarter.
- Cash climbed to $825 million and net leverage fell to 0.7x.
- Littelfuse paid down $166 million of its credit facility year to date.
Beneath the headline, the trajectory is striking. Organic growth has stepped up every quarter, from 7% in Q4 2025 to 9%, 14%, and now 22%, ahead of the 21% guide. Adjusted EBITDA margin moved from 20.5% to 28.4% over the same span. The segments tell a consistent story:
- **Electronics:** ex-fee adjusted EBITDA margin jumped to 33.1% from 26.3% in Q2. Passives grew 30% organically, and semiconductor organic growth accelerated from 8% to 15% to 24%.
- **Industrial:** organic growth reached 27%, with a 25.2% margin. The Basler acquisition added another 38 points of growth and remains ahead of plan.
- **Transportation:** organic growth improved to 7% from 1%, entirely on a 20% gain in commercial vehicles.
Passenger vehicles are the clear soft spot. Organic sales slid from +4% in Q1 to -2% in Q2 to -5% now, reflecting weaker global auto builds and sensor line exits.
Management's forward commentary preserved a credible growth story. Customers are booking beyond lead times, and 2027 backlog is fuller than normal for this point in the year. Data center design wins doubled year over year, and higher-voltage content is increasingly showing up in bookings. Aerospace and defense picked up defense flight-control and commercial space wins. Management said the Dortmund amendment accelerates contracted volumes and removes restrictive covenants, giving Littelfuse more flexibility over its manufacturing footprint.
Bears have legitimate ammunition, however. Analysts openly questioned whether electronics margins above 30% represent a cyclical peak. Customers booking further out because of supply constraints elsewhere could signal pull-forward demand. High-voltage data center revenue remains small, with growth so far coming from low-voltage products. The fourth-quarter guide, which Earnings Whispers characterizes as above estimates, calls for $750-770 million in revenue (about 28% growth) and adjusted EPS of $5.05-5.25. Management describes that as better than typical seasonality, but it still implies a sequential step-down from Q3's ex-fee revenue and its $5.79 EPS.
The market setup is more complicated than the surprise implies. Shares entered the report at $383, down 8.6% from the $419.06 open after the July report. They sat 3.7% below the 200-day moving average and about 20% beneath the $476.30 inter-earnings high set in mid-August. The stock had bounced 12% off a $342.06 low reached just days before the release. In other words, investors spent the quarter fading a fundamental acceleration, likely on peak-margin concerns. Investor sentiment edged up from 0.03 to 0.06, a slightly more positive but still essentially neutral reading. The Earnings Whispers trend signals are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Littelfuse posted its strongest quarter of the cycle by nearly every operating measure. Organic growth, margins, cash flow, and bookings all improved, and the revenue miss reflects a deliberate one-time strategic payment rather than weaker demand. The debate now centers on durability: whether 33% electronics margins and bookings stretching into 2027 reflect structural gains in data center, industrial, and power semiconductor content, or a cyclical peak flattered by pull-forward. A neutral-sentiment, below-trend stock suggests investors have not yet resolved that question in the company's favor.
Read our earnings preview for Littelfuse, Inc.: https://www.earningswhispers.com/article/LFUS/20861
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| 7 hours | |
| 12 hours | |
| Oct-14 | |
| Sep-16 | |
| Sep-10 | |
| Aug-11 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-04 | |
| May-14 | |
| May-06 |
