Orion Beats On A Concrete-Led Margin Rebound, But A 0.7x Book-To-Bill And Negative Cash Flow Leave The Recovery Unproven
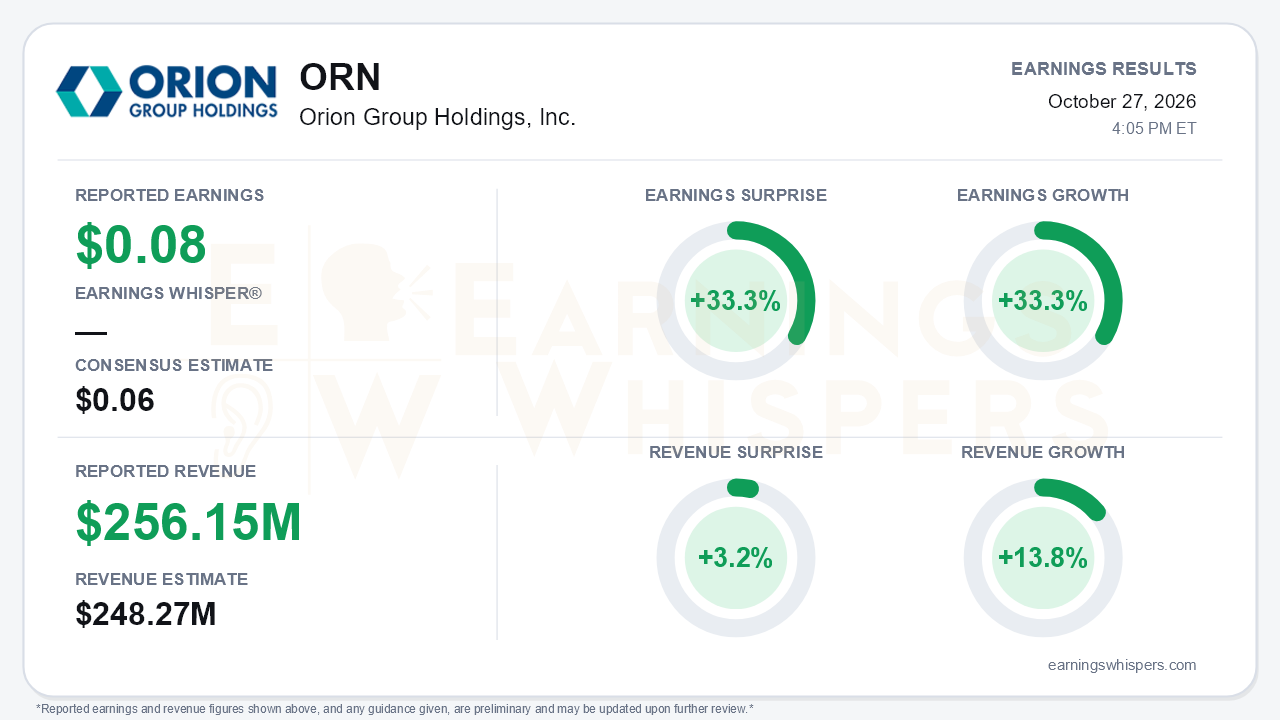
Orion Group Holdings delivered the clean quarter it needed after a disappointing second quarter. On Earnings Whispers' normalized basis, third-quarter earnings were $0.08 per share, beating the $0.06 consensus by 33.3% and rising 33.3% from a year ago. Revenue of $256.15 million topped the $248.27 million estimate by 3.2% and grew 13.8%. That is a clear acceleration from the 8% growth reported in Q2.
The company's own figures are higher. Orion reported GAAP EPS of $0.14 and adjusted EPS of $0.12, against $0.08 and $0.09 a year earlier. The gap is worth understanding. The GAAP number benefits from tax items, and the company's adjusted figure strips out a $2.6 million reversal of valuation-allowance effects. On any basis, though, the direction is the same: profitability improved meaningfully. Management reiterated full-year guidance of:
- revenue of $900-$950 million
- adjusted EBITDA of $50-$54 million
- adjusted EPS of $0.23-$0.30
On the call, management said it is now tracking toward the upper end of those ranges.
The quality of the beat deserves scrutiny, because nearly all of the improvement came from one segment.
- **Concrete:** revenue rose 16% to $95 million. Adjusted EBITDA jumped to $10.3 million from $1.5 million, lifting the segment margin to 10.8% from 1.8%. Management acknowledged that roughly two points of that margin came from non-recurring project write-ups, putting the normalized rate near 7%. That is still a solid improvement over Q2's 5.5-6%, but it is not the 11% headline.
- **Marine:** revenue grew 13% to $161 million, helped by the J.E. McAmis acquisition. Adjusted EBITDA fell to $18.8 million from $24.3 million, and the margin compressed to 11.6% from 17.0%. Last year's figure was flattered by close-out benefits that did not recur, but management guided Marine margins to only about 12-13%. Orion's larger, higher-quality segment is therefore not yet a margin driver.
- **Consolidated:** adjusted EBITDA rose 37% to $17.9 million, and the margin expanded to 7.0% from 5.8%.
The central tension is on the order book. Q3 bookings were $179 million, down from more than $275 million in Q2. Book-to-bill was roughly 0.7x, and backlog slipped to about $645 million from $722 million at midyear. Management pointed to slower owner award cycles. It offered several forward indicators to counter the decline:
- Submitted bids awaiting award climbed to about $2 billion, up from $1.6 billion at Q2 and roughly $1 billion at the start of the year.
- About $100 million of Concrete awards, including two large mission-critical projects, landed in October, after the quarter closed.
- Orion won positions on the $9 billion NAVFAC Northwest VENTI MACC and the $700 million Waterfront MACC. These vehicles narrow the field of qualified bidders for future task orders.
The Navy wins are genuine strategic catalysts, but they are contract vehicles, not guaranteed revenue. The roughly $200 million Pacific Northwest design-to-budget selection is not expected to reach backlog until mid-to-late 2027. Bulls are being asked to underwrite pipeline rather than booked work.
The balance sheet gives bears legitimate ammunition:
- Operating cash flow was negative $10.7 million through nine months, compared with positive $14.3 million a year earlier.
- Contract assets swelled to $84 million from $31 million at year-end.
- Management expects full-year free cash flow to be negative, against $14 million positive in FY2025, because of derrick barge and fleet capital spending.
- Total debt reached $109 million against just $5.7 million of cash, and net leverage rose to about 2.2x from 1.5x in Q1.
- Interest expense climbed to $3.0 million from $2.1 million.
It also matters that the reiterated guidance is the reduced version set in Q2. The original targets were $54-$58 million of adjusted EBITDA and $0.36-$0.42 of adjusted EPS. Hitting the upper end of the current range would still leave Orion short of where it started the year.
Investors entered the report skeptical. Earnings Whispers sentiment stayed negative and weakened slightly, moving to -0.353 from -0.316. Shares closed at $9.15 on the report date, down 10.8% from the open following the July report. They sit 22.8% below the 200-day moving average of $11.86, and the price and AVWAP trend readings remain negative. The market has been treating Orion as a show-me story, and this quarter supplied execution evidence without fully resolving the booking and cash questions.
The bottom line is that Orion produced a credible operational rebound: faster revenue growth, a dramatic Concrete turnaround, and confident upper-end guidance language. Those gains coexist with a shrinking backlog, a sub-1.0 book-to-bill, compressed Marine margins, and rising leverage. Concrete's normalized margin is closer to 7% than 11%, and the largest federal opportunities will not convert for quarters. The next leg of the story depends on whether the $2 billion bid pipeline turns into backlog quickly enough to fund growth without further straining the balance sheet.
Read our earnings preview for Orion Group Holdings, Inc.: https://www.earningswhispers.com/article/ORN/20785
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-27 | |
| Oct-08 | |
| Sep-22 | |
| Jul-29 | |
| Jul-28 | |
| Jul-14 | |
| May-18 | |
| Apr-28 | |
| Apr-08 | |
| Mar-19 | |
| Mar-17 | |
| Mar-06 | |
| Mar-05 | |
| Mar-04 |
