Labcorp's Organic Acceleration Drives A Third Guidance Raise, But A $125 Million PAMA Hit Clouds 2027
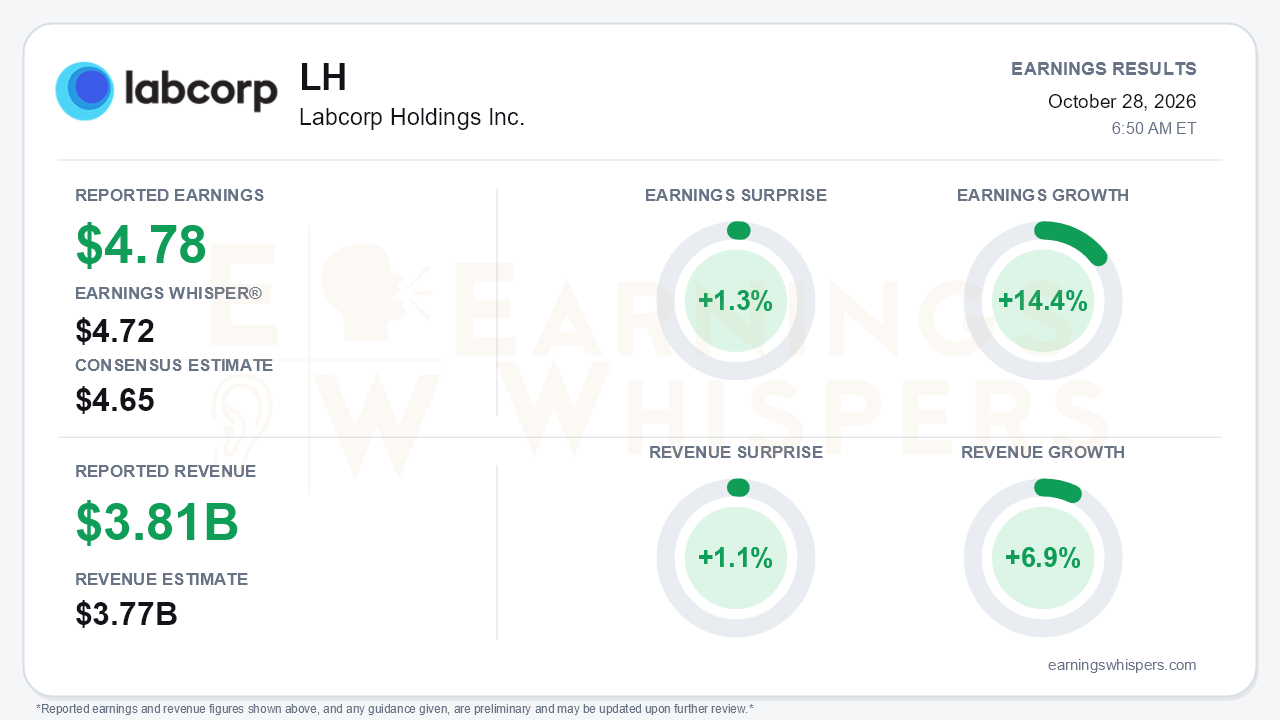
Labcorp delivered its cleanest growth quarter of the year. Adjusted EPS came in at $4.78, ahead of the $4.65 consensus and the $4.72 Earnings Whisper number, a 1.3% beat. Revenue of $3.81 billion topped the $3.77 billion consensus by 1.1%. Earnings grew 14.4% year over year and revenue rose 6.9%, a clear step up from the 5.8% revenue growth posted in each of the first two quarters. The beat was modest. What changed is the trajectory: organic growth has accelerated from 3.1% in Q1 to 4.2% in Q2 and 5.5% in Q3, and management raised full-year guidance for the third straight quarter. The central tension is that this improving trend now runs into a quantified reimbursement headwind for 2027.
The quality of the beat deserves some scrutiny. On a GAAP basis, diluted EPS rose only 3.3% to $3.22. GAAP operating margin fell 60 basis points to 10.6%, even as adjusted operating margin expanded 60 basis points to 15.0%. The gap came from adjustments that climbed to $167.9 million from $116.7 million, including:
- acquisition-related costs of $23.0 million, up from $10.8 million;
- LaunchPad costs of $28.6 million, up from $13.7 million;
- higher restructuring charges.
A lower diluted share count (81.6 million versus 83.7 million) and a lighter tax provision also helped the per-share result. Cash generation was a genuine positive. Free cash flow jumped to $412 million from $281 million, driven mainly by working capital. However, full-year free-cash-flow guidance was held at $1.24 to $1.36 billion rather than raised, and quarter-end cash of $262 million against $5.85 billion of debt leaves little slack for an accelerating deal pace.
Beneath the headline, Biopharma Laboratory Services was the standout. Organic constant-currency growth reached 9.6%, up from 6.2% in Q2 and 3.7% in Q1. Central lab growth accelerated to 11.3%, and segment margin widened 180 basis points to 18.3%. Quarterly book-to-bill was 1.13, the trailing figure improved to 1.10 from 1.03, and backlog rose to $8.9 billion. Management lifted full-year BLS growth guidance to 7.4% to 8.4% from 5.5% to 6.5% and raised its central lab outlook to high single digits. Diagnostics was steadier than spectacular. Organic volume improved to 3.1% from 1.8% in Q2, but organic price/mix slowed to 1.3% from 1.8% and segment margin expanded only 40 basis points. Management also acknowledged that part of the central lab strength reflected favorable study-start timing, so the Q3 growth rate may not be a clean run rate.
The forward story now has two competing threads. On the catalyst side, Labcorp closed MLM Medical Labs and signed three deals after quarter end:
- BioReference assets, roughly $216 million of revenue and about $0.15 of year-one EPS, expected to close mid-2027;
- Myriad's prenatal business, roughly $160 million of revenue;
- Millennium Health.
The company also secured FDA approval for its PGDx melanoma companion diagnostic and launched a pTau-217 Alzheimer's blood test. On the risk side, CMS's preliminary PAMA fee schedule implies roughly a $125 million Medicare and Medicaid headwind in 2027, with some spillover to other payers and smaller cuts in 2028 and 2029. Management reaffirmed its 2026-2029 long-term outlook and argued that PAMA pressure should enlarge the pipeline of hospital and regional lab acquisitions. Bears still have legitimate ammunition:
- 2027 margin cadence is uncertain;
- the Myriad assets come with a history of steep revenue declines;
- softening biotech funding could weigh on Early Development, which grew just 0.4%.
The guidance raise itself was incremental rather than transformative. Adjusted EPS guidance moved to $18.30 to $18.70, up $0.18 at the midpoint, a raise that landed in line with estimates. Enterprise revenue growth rose 50 basis points at the midpoint to 5.9% to 6.7%.
The market had already been leaning toward this outcome. Shares rose 11.1% from the $298 open after the July report to $331.17 ahead of this release. That leaves the stock about 15.9% above its 200-day moving average and only 3.1% below the $341.80 52-week high set in late August, near the top of its inter-earnings range. Investor sentiment improved from slightly negative to roughly neutral, a modest shift rather than a wave of enthusiasm. The Earnings Whispers trend signals are uniformly positive, consistent with the steady improvement in sequential growth. That positioning raises the bar: a 1.3% beat and an in-line raise give the stock less of a surprise cushion than the acceleration narrative might suggest.
The bottom line is that Labcorp's operating momentum is real and broadening, led by a re-accelerating central lab business, rising organic volumes, and six straight quarters of adjusted margin expansion. The call preserved a credible growth story. However, the gap between GAAP and adjusted earnings, slowing diagnostics pricing, study-timing help in BLS, and a $125 million PAMA hit in 2027 mean the next leg depends on execution and M&A integration rather than simply extending this quarter's trend.
Read our earnings preview for Labcorp Holdings Inc.: https://www.earningswhispers.com/article/LH/20862
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 |
