Clean Harbors Smashes Estimates And Raises Again, But A $120 Million Fire Response And Peak Oil Spreads Set Up A Tough 2027
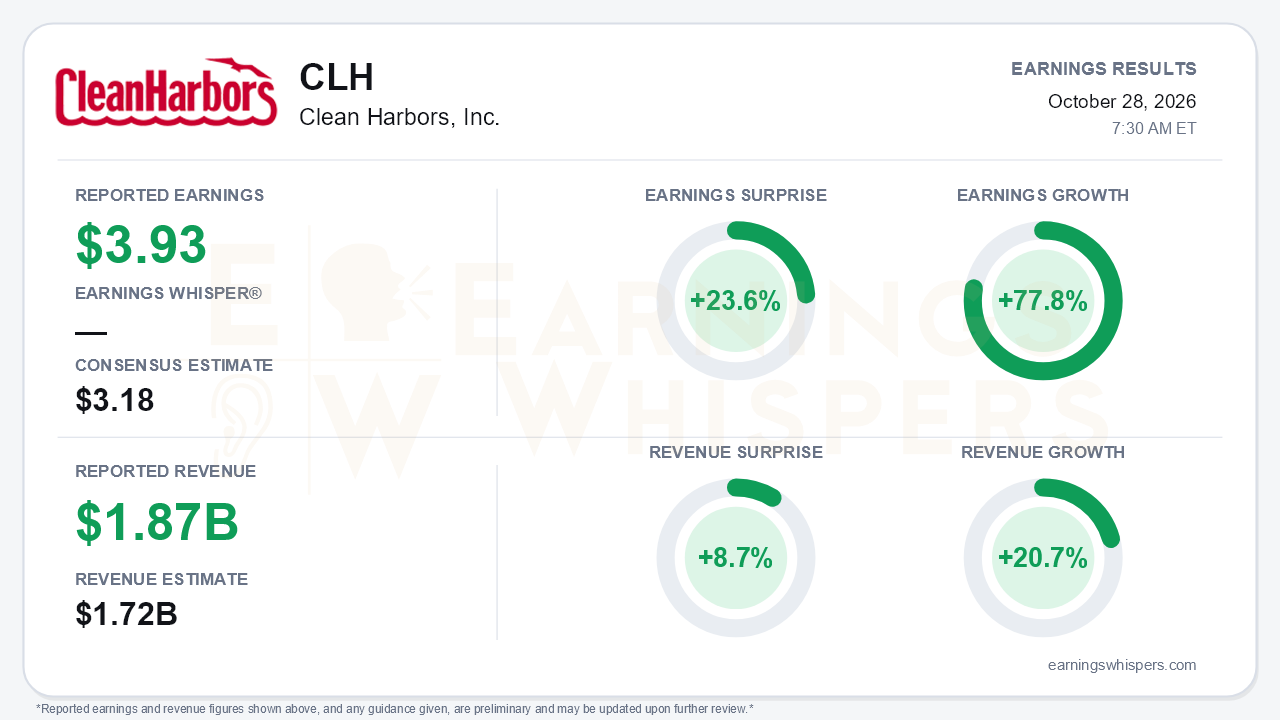
Clean Harbors delivered one of its strongest quarters, and the size of the beat was hard to ignore. The company earned $3.93 per share, 23.6% above the $3.18 consensus and up 77.8% from a year ago. Revenue reached a record $1.869 billion, beating the $1.72 billion estimate by 8.7% and growing 20.7%. Management raised full-year adjusted EBITDA guidance to a $1.44 billion to $1.48 billion range, the third straight beat-and-raise. The central tension is that much of the quarter's lift came from two sources that will be difficult to repeat: a single large emergency response job and record pricing for re-refined oil. The bull case now depends on whether the core franchise can carry 2027 once those tailwinds fade.
The quality of the beat deserves scrutiny. Field Services revenue jumped more than 70%, driven largely by a Los Angeles warehouse fire response that generated roughly $120 million of revenue at premium emergency rates. That single event accounts for more than a third of the company's $320 million year-over-year revenue increase. The Safety-Kleen Sustainability Solutions segment (SKSS) was the other swing factor. Segment adjusted EBITDA more than tripled to $126.5 million from $40.9 million as global supply disruptions kept base oil and lubricant prices elevated. Mix and execution helped, with Group III output up about 20%, but market pricing did the heavy lifting. Consolidated adjusted EBITDA rose 42% to $456.1 million, and the margin reached a record 24.4%, up 370 basis points.
The Environmental Services (ES) segment is the stronger evidence of durable growth. Segment margin reached 27.4%, its 18th consecutive quarter of year-over-year expansion. The call put organic ES growth at roughly 16%, and management lifted its full-year ES EBITDA growth outlook to 9%-11%, up from about 5% at the start of the year. There were also signs of slowing beneath the headline:
- Technical Services growth slowed to 3% from 18% in the second quarter, against tough project comparisons.
- Incineration utilization fell to 87% from 91% in the prior quarter.
- Industrial Services remains roughly flat, with margins pressured by depressed refinery turnaround activity.
- Corporate expense growth guidance worsened again, to 14%-17% from 8%-10%, on incentive compensation and insurance claims.
The forward catalysts are real and specific. A $600 million, 10-year reshoring contract began in the fourth quarter and is ramping ahead of expectations. PFAS revenue is now tracking about 30% growth, versus the 20% assumed in February. Planned data center investment rose to $70 million across roughly a dozen active projects. Deferred revenue rose 20%, and management described the sales pipeline as larger than it was 90 days ago. Against that, management guided SKSS lower sequentially in the fourth quarter, and the timing of base oil normalization is uncertain. Acquisitions are expected to weigh on 2027 margins by about 30 basis points. Leverage is climbing toward the low-2x range after $689 million of year-to-date acquisitions and a $600 million notes offering, which helps explain why cash fell to $424 million from $826 million at year-end. Co-CEO Mike Battles retires at year-end, leaving Eric Gerstenberg as sole CEO, adding a leadership transition to the mix.
The market had not been rewarding the guidance raises before this report. Shares closed at $312.92 on the eve of results, down 5.5% from the opening price after the July report. The stock set its 52-week high of $335.94 on that July report day and spent the quarter retreating toward the $303.46 low. That leaves it 6.9% below the high, 3.1% above the low, and still 5.3% above its 200-day moving average. Investor sentiment improved from 0.09 to 0.19, which is constructive but hardly euphoric. The Earnings Whispers trend readings are mixed: momentum is positive, while sequential growth and AVWAP trends are negative. That pattern matches a stock where investors acknowledge the strength but question its durability.
Bears have legitimate ammunition on comparisons. Management has not provided 2027 guidance, and lapping a $120 million emergency job alongside peak re-refining spreads will make growth arithmetic harder. Bulls can counter that the ES franchise is compounding on its own, that new contract and PFAS revenue is starting rather than ending, and that guidance has risen $230 million since February.
The bottom line is that Clean Harbors posted an exceptional, cash-rich quarter and preserved a credible growth story, but this quarter's results flatter the run rate. The investment debate now shifts from whether 2026 will be a record year, which looks settled, to how much of that record holds up in 2027 once the fire-response windfall and peak oil spreads roll off.
Read our earnings preview for Clean Harbors, Inc.: https://www.earningswhispers.com/article/CLH/20833
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 7 hours | |
| 12 hours | |
| 12 hours | |
| Oct-13 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 | |
| Sep-17 | |
| Sep-17 | |
| Aug-12 | |
| Aug-12 | |
| Jul-31 | |
| Jul-29 |
