UMB Financial Beats On Record Loan Production, But Flat Sequential Earnings And Rising Costs Test A 37% Rally
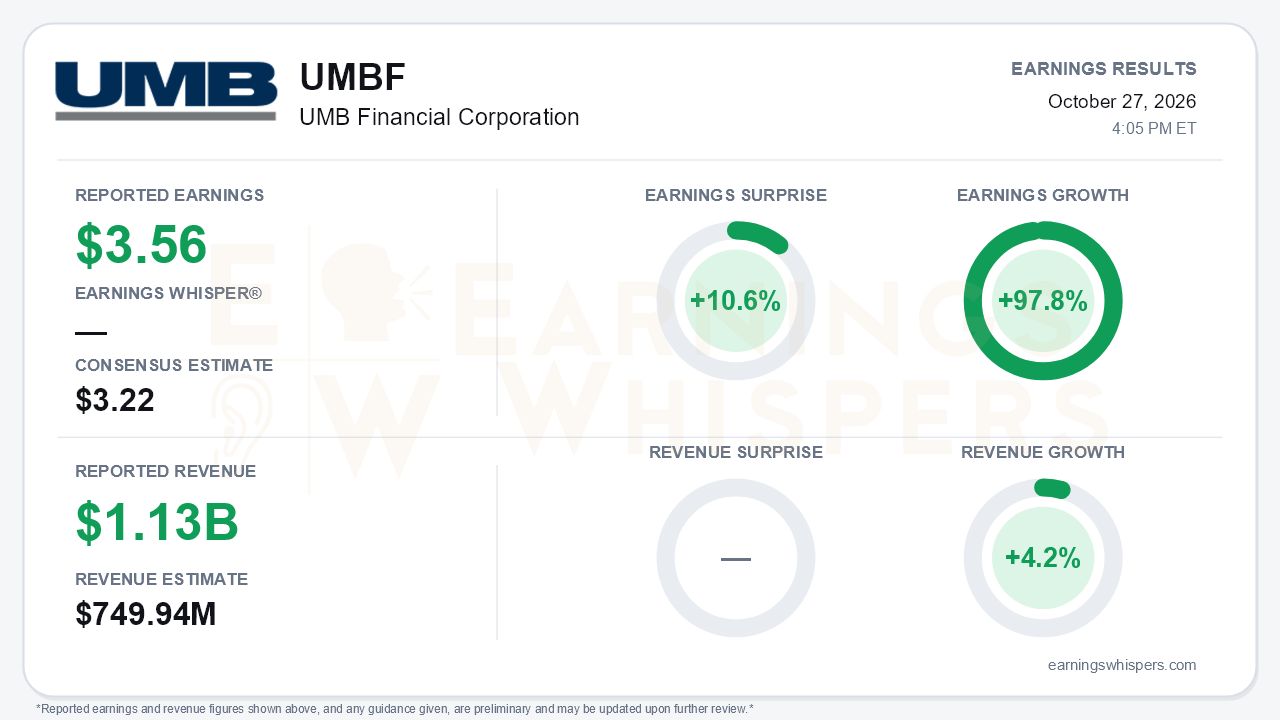
UMB Financial delivered a clean beat in the third quarter. It earned $3.56 per share against a $3.22 consensus, a 10.6% surprise, and Earnings Whispers calculates year-over-year earnings growth of 97.8%. Revenue on the Earnings Whispers basis was $1.128 billion versus $749.94 million expected, a 50.4% surprise, with year-over-year growth of 4.2%. Investors should know that this revenue figure captures total interest income plus fee income, so it is not comparable with the street's net-revenue estimate. On UMB's own net-revenue measure, the quarter produced $772.4 million, up 13.9%. The central tension is that the year-over-year comparisons look spectacular while the sequential picture is essentially flat. GAAP EPS of $3.56 matched the second quarter exactly. Operating EPS slipped a penny to $3.56. Operating pre-tax, pre-provision income fell 1.8% from the linked quarter to $373.0 million.
The quality of the beat holds up reasonably well, with caveats. Much of the year-over-year surge reflects the absence of Heartland-related integration costs. The year-ago quarter carried $35.6 million in acquisition and nonrecurring expenses; this quarter carried just $0.1 million. That swing is why the company's own GAAP EPS growth (51%) and operating EPS growth (31.9%) differ so sharply. Net interest income rose 1.4% sequentially to $540.0 million on a flat 3.32% margin. Reported fee income fell 5.3% to $232.4 million, but the decline traces mostly to a $17.9 million non-marketable security gain in the prior quarter and lower COLI income. COLI is offset in deferred compensation, so it is noise rather than erosion. Credit was a genuine positive:
- net charge-offs fell to 13 basis points;
- nonperforming loans improved to 28 basis points from 31;
- the higher $31.0 million provision reflected loan growth rather than deterioration.
Beneath the headline, the operating engine is accelerating:
- gross loan production hit a record $3.1 billion, up from $2.6 billion in the second quarter and $2.3 billion in the first;
- average loans grew 11.1% annualized;
- C&I balances grew roughly 22% annualized;
- core NIM, excluding purchase accounting, edged up to 3.10% from 3.09%, extending a steady climb from 2.96% in the fourth quarter of 2025;
- the core fee run-rate rose to about $218 million from roughly $210 million;
- trust and securities processing rose 8.8% sequentially;
- private wealth net new assets of $1.2 billion year to date already match all of 2025.
The call also added a new catalyst. UMB agreed to acquire Eldorado Savings Bank for about $500 million in cash and stock. The deal brings $2.1 billion of deposits costing just 88 basis points, a 24% loan-to-deposit ratio, and 35 branches around Sacramento, Tahoe and Reno. Management expects it to close in the first quarter of 2027, be modestly accretive in 2027, and lower total deposit costs by about 4 basis points.
Bears have legitimate ammunition, however:
- **Rate backdrop:** the rate cycle has turned to hikes, interest-bearing deposit costs rose about 4 basis points, and management noted index deposits reprice faster than loans.
- **Funding:** average deposits grew only 1.1%, noninterest-bearing balances fell 6.1% seasonally, and loans are outrunning funding.
- **Production:** management guided fourth-quarter production back toward first-half levels and flagged elevated payoffs.
- **Expenses:** fourth-quarter expenses are guided to $400-405 million, above the roughly $390 million once guided for the third quarter.
- **Accretion:** purchase accounting accretion keeps shrinking, to $33.1 million from $35.9 million, and projected 2027 accretion fell to $75 million.
- **Returns:** operating ROTCE slipped to 19.5% from 20.3%.
- **Book value:** rising rates hit book value hard. Accumulated other comprehensive loss more than doubled to $793 million, producing a quarterly comprehensive loss and pulling tangible book value per share down to $70.07 from $72.03, even as regulatory CET1 improved to 11.50%.
- **Deal dilution:** Eldorado will dilute CET1 by 15-20 basis points at close.
The market setup is more complicated than the surprise implies. Shares have rallied 37.2% since opening at $97.53 after the July report and now sit near $133.80, roughly 39% above the 200-day moving average. Price and AVWAP trend readings are positive. Investor sentiment, however, cooled from 0.0696 to 0.0071, essentially neutral. That suggests enthusiasm did not keep pace with the stock. A rally of that magnitude prices in much of the loan-growth and fee story, leaving less room for the cost, funding and rate headwinds management itself flagged.
The bottom line is that UMB's franchise is executing well: record production, accelerating fee businesses, pristine credit and a deposit-rich tuck-in deal. Yet sequential earnings power has plateaued while expenses, deposit costs and fading accretion press against it. With the stock extended well above its long-term average and sentiment fading toward neutral, the next leg depends on whether core margin and fee momentum can outrun those headwinds once loan production normalizes.
Read our earnings preview for UMB Financial Corporation: https://www.earningswhispers.com/article/UMBF/20806
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-07 | |
| Sep-10 | |
| Aug-28 | |
| Aug-10 | |
| Aug-03 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-08 |
