Lennox Misses As Price Realization Fails; Second Straight Guidance Cut Overshadows Commercial Strength
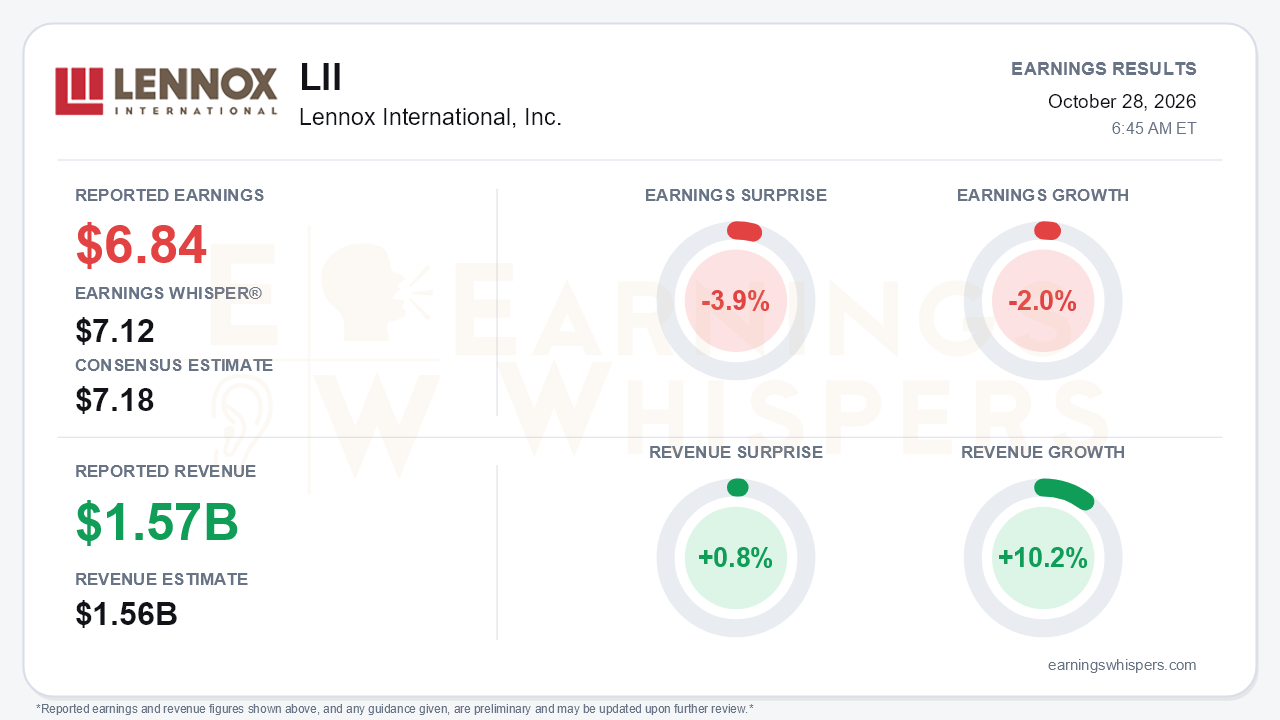
Lennox International (NYSE: LII) reported third-quarter adjusted earnings of $6.84 per share, missing the $7.18 consensus by 3.9% and falling short of the $7.12 Earnings Whisper number. Revenue was $1.573 billion, up 10.2% year over year and 0.8% above the $1.56 billion consensus. Earnings fell 2.0% on Earnings Whispers' normalized basis. The company's own comparison is harsher: adjusted EPS fell 7% from $7.38. Either way, the headline is not the miss itself. Lennox cut full-year adjusted EPS guidance for the second consecutive quarter, to $21.00-$21.50 from $23.00-$24.00, and this cut was larger than the one in July. The original outlook of $23.50-$25.00 now looks distant. That is the central tension: top-line trends improved, but the company lost control of the price-cost equation.
The quality of the quarter deserves scrutiny because growth and profitability moved in opposite directions. Building Climate Solutions did its job. Revenue rose 24%, including 15% organic growth, and segment profit climbed 19% to $167 million at a still-strong 26.2% margin. Home Comfort Solutions is where the story broke. Segment revenue rose 3%, but profit fell 18% to $176 million and margin collapsed 490 basis points to 18.7%. Within HCS, $32 million of product-cost inflation and tariff headwinds, plus $15 million of higher fuel, SG&A and distribution costs, swamped just $13 million of price and mix benefit. Management also cut prices in select segments to defend share. Below the operating line, the picture was also less favorable:
- Net interest expense rose to $17.5 million from $10.5 million as commercial paper balances climbed.
- The tax provision took a bigger bite than a year ago.
- GAAP EPS of $6.41 absorbed restructuring, litigation and acquisition costs.
The call made clear that the late-second-quarter price increase did not stick. Management cited competitive pressure and pricing fatigue, while Section 232 derivative tariffs of up to 25% on some categories hit in the third quarter and created a price-cost mismatch. The tone shifted noticeably. In the first quarter, management framed HCS as stabilizing; in the second, as a demand delay. Now it is an explicit four-part recovery plan built on pricing, productivity, portfolio and promoters. To be fair, the underlying volume picture improved. HCS organic sales were down just 1% versus down 9% in the second quarter, two-step organic sales rose 13%, and management said share has stabilized with no incremental losses. The problem is that the stabilization was purchased with margin.
The guidance revisions were broad, and they look forward as well as backward:
- Full-year revenue growth was trimmed to about 6% from 8%.
- The HCS revenue outlook moved to roughly -4% from +1%.
- The price/mix contribution was cut to low single digits from mid single digits.
- Free cash flow guidance was lowered for the first time, to $700-$750 million from $750-$850 million.
- Enterprise margins are now expected to contract about 200 basis points, after management entered the year guiding to a fourth straight year of expansion.
With nine-month adjusted EPS at $17.89, the new range implies a fourth quarter of roughly $3.10-$3.60. That includes another steep HCS margin decline and a soft start from warm Midwest weather. The lone raised target was BCS revenue growth of about 23%, up from 20%.
Management is leaning on 2027 for the recovery. Its plan includes:
- an annual price increase above the traditional 1-2%, plus inflation riders on national accounts;
- a full entry-tier launch in the first quarter, covering side-discharge, lower-cost unitary and mini-split products, to counter overseas entrants;
- distribution and SG&A restructuring, including lease exits tied to the new Dallas facility;
- an expected accretive contribution from Heat Controller.
Management said it expects higher sales, EPS and EBIT dollars next year. Bears have legitimate ammunition here. The 2027 price increase only works if competitors follow, and the entry-tier push carries mix and ASP dilution risk. Slower pricing on national contracts is also starting to pressure BCS margins. Cash flow is the clearest positive. Third-quarter operating cash flow rose to $395 million from $301 million on lower inventory, and that supports management's stated tilt toward opportunistic buybacks.
The market had already priced in much of the disappointment. Shares were $372.05 entering the report, down 24.2% from the $491 open after the July release. That left the stock 21.7% below its 200-day moving average and only 9.3% above the 52-week low of $340.32 set on October 13. Investor sentiment swung from mildly positive (0.09) to clearly negative (-0.51), a genuinely large deterioration. The Earnings Whispers trend signals are uniformly negative, with sequential growth and momentum still deteriorating. Low expectations may cushion the miss, but the guidance cut resets the earnings base lower again.
The bottom line is that Lennox delivered the revenue but not the earnings. The commercial business is accelerating while the residential franchise is paying to hold share against tariffs and lower-cost competition. Until the 2027 pricing and entry-tier strategy shows it can restore HCS margins, the investment case rests on management's recovery plan rather than demonstrated results, and the third quarter left credibility to rebuild.
Read our earnings preview for Lennox International, Inc.: https://www.earningswhispers.com/article/LII/20863
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-19 | |
| Oct-14 | |
| Oct-14 | |
| Oct-08 | |
| Sep-28 | |
| Sep-18 | |
| Sep-10 | |
| Sep-03 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 |
