Generac Edges Past Consensus But Misses The Whisper As Amazon Deal Nearly Triples Its Data Center Backlog
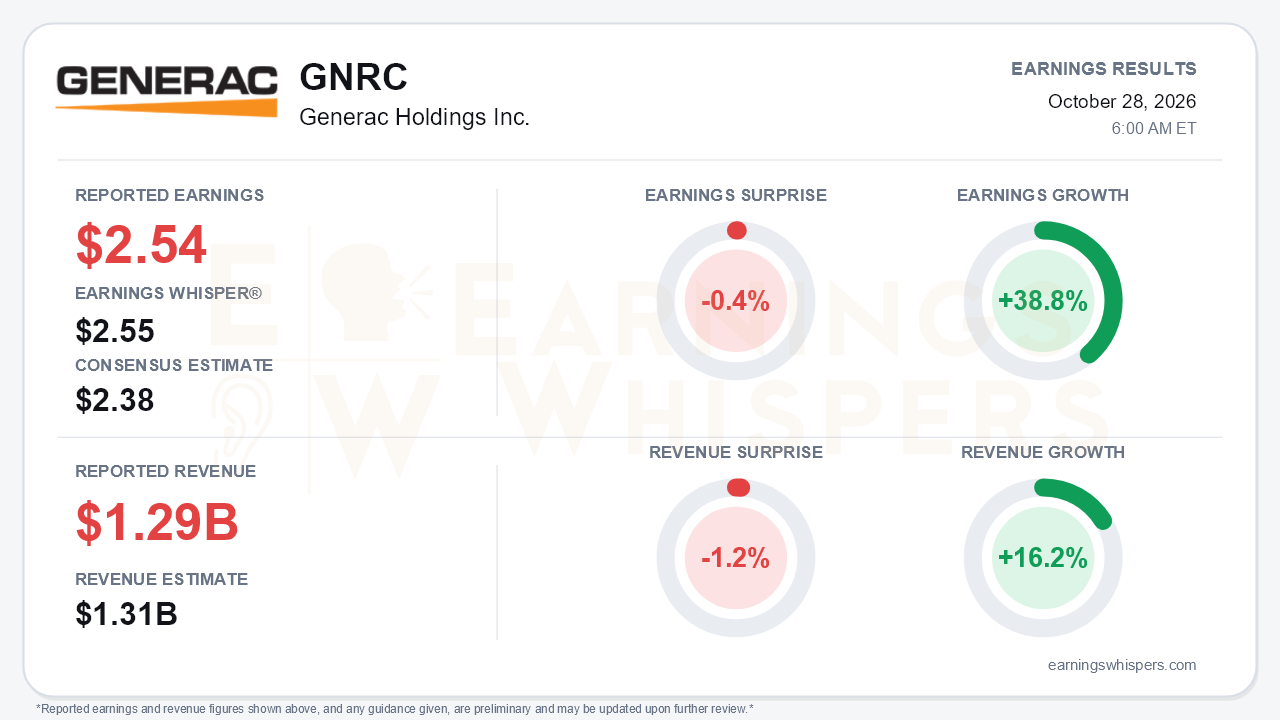
Generac's third quarter was a narrow miss against the Earnings Whisper number and a major advance in its long-term story. Adjusted earnings of $2.54 per share beat the $2.38 consensus but fell a penny short of the $2.55 Whisper, a 0.4% shortfall. Revenue of $1.295 billion missed the $1.31 billion consensus by 1.2%. The year-over-year numbers were strong. Earnings grew 38.8% and revenue rose 16.2% to a record, an acceleration from 11% sales growth in the second quarter and 12% in the first. That is the central tension. The quarter barely cleared its bar, but the data center backlog jumped from $1.6 billion to roughly $4.5 billion, and management now frames 2027 in terms most investors had expected to take several years.
The quality of the beat holds up better than the headline suggests, with a few caveats. GAAP EPS rose to $1.83 from $1.12 even though the effective tax rate climbed to 23.9% from 15.0%. Gross margin expanded to 39.9% from 38.3%, and adjusted EBITDA rose 33% to $256 million, or 19.8% of sales. Free cash flow increased to $132 million. Some of the gross margin gain came from lower tariff costs rather than purely operational improvement. The adjusted figures also add back $14.3 million tied to clean energy warranty matters. Below the income statement, receivables have climbed about $243 million since December as data center shipments ramp, which investors will want to watch.
The operating mix improved in both segments.
- **Commercial & Industrial:** Sales grew 28% to $553 million on more than $100 million of data center revenue. Segment EBITDA margin rose to 12.5% from 10.1%. Domestic industrial distributor shipments declined as the Beaver Dam relocation stretched lead times, and telecom slowed further.
- **Residential:** The segment returned to growth, up 9% after declining 2% in the second quarter and 23% in the fourth quarter of 2025. Home standby grew in the mid-teens, and activations rose in September for the first time since the second quarter of 2025. Segment margin expanded to 27.0% from 23.4%. Energy storage remains weak.
The forward story is the catalyst package. The Amazon agreement covers roughly $2.4 billion of initial deliveries in 2027 and 2028 and up to $8 billion over seven years, with warrants tied to purchases. The quarter also added about $600 million of orders from customers outside the hyperscale market. Management now expects 2027 data center revenue to "well exceed" $2 billion and sees a path to doubling C&I next year. That compares with the earlier framing of doubling over three to five years. On capacity:
- The Sussex facility began production at the end of the third quarter.
- The capacity target rose to about $4 billion by the second half of 2027.
- Management is weighing a further step from $4 billion to $6 billion.
Guidance moved in both directions:
- **Raised:** The adjusted EBITDA margin range moved to 20.5% to 21.0%. Free cash flow guidance rose to roughly $450 million from the $350 million held over three prior calls. Fiscal 2026 data center revenue was nudged to nearly $500 million.
- **Held or lowered:** Total sales growth guidance was only reaffirmed in the mid-to-high teens. The residential outlook slipped to high single digits from about 10%. Fourth-quarter gross margin is expected to fall to 37% to 38% on data center mix and inflation. Interest expense is tracking the high end of its range.
Bears have legitimate ammunition. A draft executive order on foreign-produced bulk power system components could affect engine sourcing, with final wording expected in December. Engine supply is already single-sourced. Management also acknowledged credit and concentration risk with non-hyperscale project vehicles and has tightened guarantee and deposit requirements in response. Contract terms with data center customers, including cancellation rights and delivery obligations, appear among the release's stated risks. Execution on a capacity ramp of this scale is not trivial.
The market setup is more complicated than the fundamentals imply. Investor sentiment remained positive heading into the report but weakened meaningfully, falling from 0.33 to 0.19. Shares closed at $193.71 before the release. That was 7.8% below the open following the July report and nearly 11% below the 200-day moving average of $217.52. The inter-earnings range was set in back-to-back sessions in mid-September, with a low of $173.25 and a high of $231.89 a day later. The stock entered earnings 16.5% below that high, having given back much of the spike. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Generac delivered a quarter that disappointed narrowly against the Whisper and consensus revenue but transformed its data center visibility. Its backlog nearly tripled, margin and cash flow guidance rose, and residential returned to growth. Cooling sentiment and a stock below its 200-day average suggest investors were not positioned for this much improvement in the outlook. Even so, the softer fourth-quarter margin, merely reaffirmed sales guidance, and policy and supply-chain risks mean the burden now shifts to executing the 2027 ramp.
Read our earnings preview for Generac Holdings Inc.: https://www.earningswhispers.com/article/GNRC/20851
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours |
Generac reports record sales of $1.29 billion, driven by data centers
GNRC
Milwaukee Journal Sentinel
|
| 4 hours | |
| 6 hours | |
| 9 hours | |
| 13 hours | |
| Oct-21 | |
| Oct-14 | |
| Oct-14 | |
| Oct-08 |
Amazon Supplier Gets Boost From Bullish Analyst Calls; The Stock Is Climbing
GNRC
Investor's Business Daily
|
| Oct-08 | |
| Oct-02 | |
| Sep-29 | |
| Sep-25 | |
| Sep-24 | |
| Sep-18 |
