Townsquare's Digital Pivot Faces A Credibility Test After A Halved Share Price
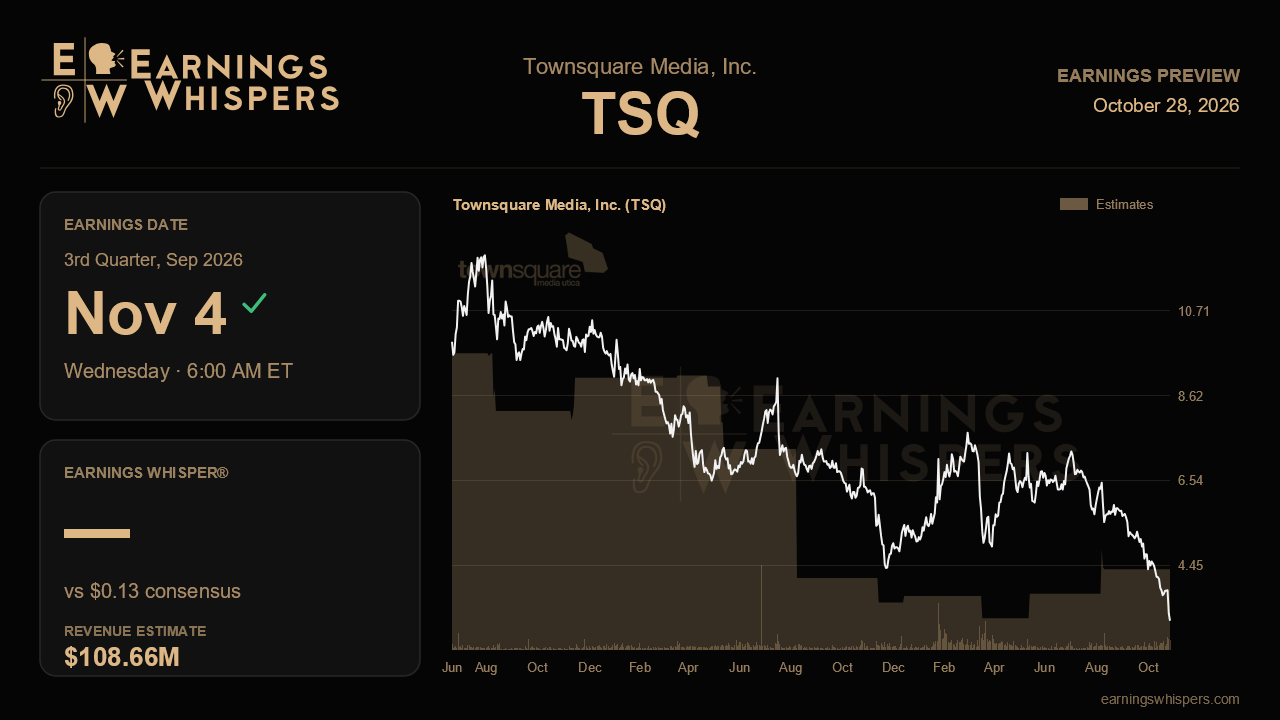
Townsquare Media enters its third-quarter report with one of the starker disconnects in small-cap media. Last quarter, management described its digital-first transformation as an accomplished fact, pointing to accelerating digital advertising, record margins at its Townsquare Interactive unit and a brand-new software licensing stream. The market's reply has been brutal: the stock has fallen about 50% since that call, while the S&P 500 was essentially flat. Thursday-morning optimism is not the issue here. The November 4 release, due before the open, needs to show that the operating story is real enough to matter against a balance sheet and broadcast base that investors plainly distrust.
The bar itself is modest. Analysts expect earnings of $0.13 a share, up from $0.05 a year ago, on revenue of $108.7 million, only 1.8% higher. That revenue figure sits in the lower half of management's guidance of $108 million to $110 million, so a quarter merely at the midpoint would count as a small beat. The full year is more awkward. Management narrowed its 2026 revenue outlook to $425 million to $431 million and trimmed the top of its adjusted EBITDA range to $90 million, yet full-year consensus revenue of roughly $432 million still sits above the company's own ceiling. Either the Street trims its numbers, or Townsquare has to show that the fourth quarter can carry more weight than its guidance implies.
Digital is the metric that matters most. Digital advertising growth climbed from a decline of 1.6% a year ago to about 7% in the first quarter and 11% in the second, and management guided the third quarter higher still. Programmatic, now about 70% of digital ad revenue, grew 27% last quarter. Another step up would confirm that lapping last August's remnant audience headwind is producing a cleaner growth runway. A stall near 11% would suggest the acceleration was mostly an easier comparison. Media partnerships offer a second check. Management expects that revenue to more than double to over $12 million this year from 16 partners across 115 markets. Any early read on the Blueprint CRM licensing deal with Summit Media would help show whether software can become a recurring line rather than a one-off.
Townsquare Interactive is the more nuanced test. Its margin reached a record 37.6% last quarter, well above the historical level near 28%. Revenue, however, fell 8.5% to $17.2 million because the sales force was cut by roughly 40% and won't be fully rebuilt until 2027. Management said a return to sequential growth could come as early as this quarter and by year-end. Hitting that milestone while holding margins in the mid-30s would validate the profit-over-volume strategy. Missing it would suggest the margin gains came largely from cost cuts. Broadcast is the drag the digital engine must outrun. Ex-political declines improved to around 7% from a steady 8% in 2025, but national network revenue is still falling in the high teens.
Sentiment has soured, moving from slightly bullish before the last report to 16.5% bearish now. The chart reflects that pessimism. At $3.08, the stock trades about half its 200-day average of $6.03 and sits just above its post-earnings low of $2.95, far below the prior quarter's $5.65 floor. Net leverage of 5.44x has drifted higher, and recurring non-cash FCC impairments, which produced a $41.8 million GAAP loss last quarter, will likely muddy reported results again. The dividend yield was already near 13% before the selloff, so how management talks about capital allocation and debt reduction may matter as much as the income statement.
Ultimately, the question is whether digital growth and partnership revenue can lift adjusted EBITDA, which fell 6.2% last quarter, at a pace that stabilizes leverage. If Townsquare shows a faster digital line, a turn in Interactive revenue and EBITDA tracking toward the middle of its range, the market's harsh verdict could look overdone. If EBITDA keeps slipping while leverage rises, the transformation story will struggle to outweigh the balance sheet worries.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-01 | |
| Sep-30 | |
| Aug-17 | |
| Aug-14 | |
| Aug-12 | |
| Aug-06 | |
| Aug-06 | |
| Jul-15 | |
| May-27 | |
| May-12 | |
| May-11 | |
| May-05 | |
| Apr-27 | |
| Apr-15 |
