EXL's Third Beat-And-Raise Shows Faster Growth, But Margins Are Not Keeping Pace
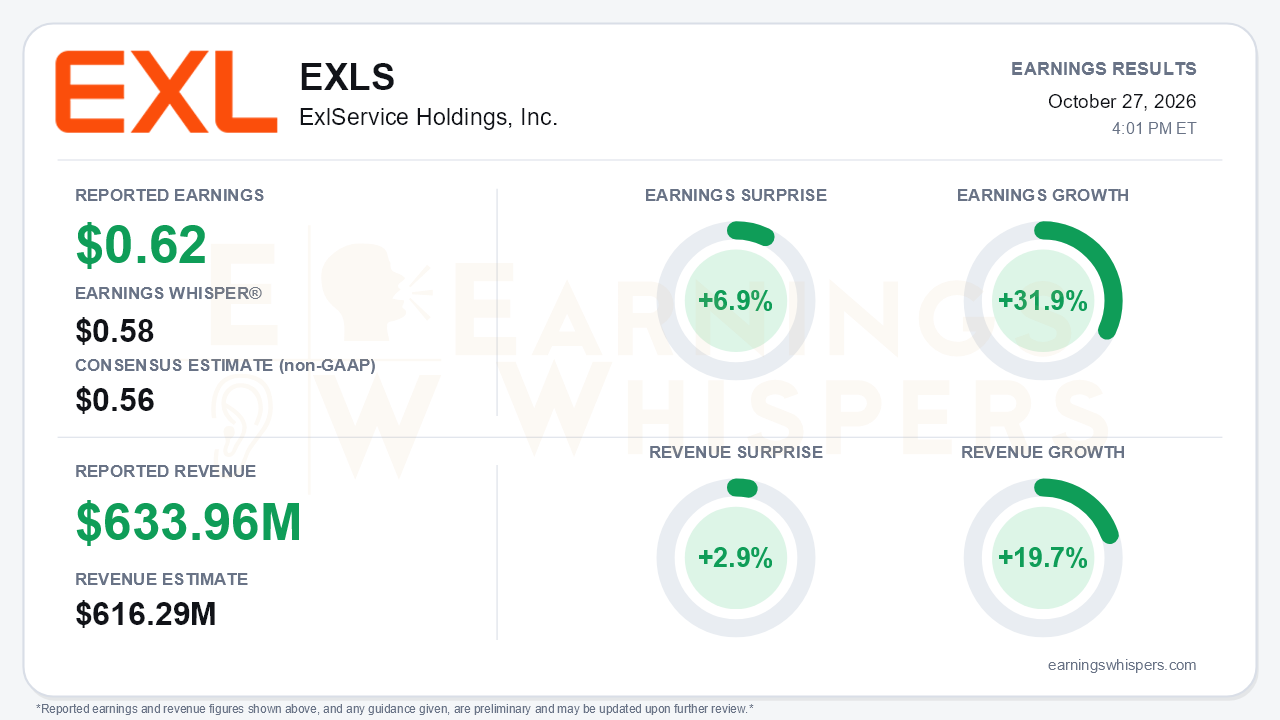
ExlService Holdings delivered its third straight beat-and-raise quarter, and its growth is still speeding up. Adjusted EPS of $0.62 topped the $0.56 consensus by 6.9% and cleared the $0.58 Earnings Whisper number. Revenue of $633.96 million beat the $616.29 million consensus by 2.9%. On Earnings Whispers' normalized basis, earnings grew 31.9% year over year. The company's own comparison against its reported $0.48 a year ago shows 28.5%. Revenue grew 19.7%, and organic constant-currency growth reached 17%, up from 15.9% in Q2, 13.4% in Q1 and 12.6% in Q4. The central tension is that EXL is growing faster than it has in years without converting any of that acceleration into margin expansion.
The quality of the beat deserves some scrutiny. Adjusted operating income rose to $122.5 million from $102.6 million, essentially in line with revenue growth. The adjusted operating margin slipped to 19.3%, down from 19.4% a year ago, 19.7% in Q2 and 20.5% in Q1. GAAP operating margin fell to 14.0% from 14.7% sequentially. Several factors helped EPS grow faster than operating profit:
- The diluted share count fell to about 152.6 million from 161.7 million a year earlier.
- A $1.5 million foreign exchange gain replaced a prior-year loss.
GAAP EPS of $0.45, up from $0.36, is a solid result on its own. Still, part of the per-share growth reflects financial engineering rather than operating leverage.
The call nonetheless preserved a credible and broadening growth story. Data and AI-led revenue, now nearly two-thirds of the business, grew 31% organically (36% reported). That marks a fifth straight quarter of acceleration, up from 21% in Q4. Gains were widespread:
- Insurance accelerated for a third consecutive quarter to 15.5%, up from 7.2% in Q4.
- International Growth Markets reached 21%.
- Banking, Capital Markets and Diversified Industries grew 16.8% organically, up from 8.1% in Q1.
- Even the operations business improved to 12% growth.
Management said pipeline creation is growing at a double-digit rate and deal cycles are shortening. The iMerit acquisition, closed at the end of July, contributed $15.3 million in two months. It also launched a Model Training Solutions practice and a Scholars platform of more than 30,000 domain experts for model fine-tuning. Together with a Google-partnered UK bank win, these give EXL a tangible foothold in the AI model-training ecosystem.
Bears have legitimate ammunition, however.
- **Healthcare and Life Sciences:** Organic growth slowed to about 17% from 22% in Q2 and 26% in Q4. Management characterized the slowdown as timing. Segment gross margin also dipped sequentially to 45.2%.
- **BCMDI margins:** Gross margin fell to 34.4% from 38.3% a year ago on ramp-up hiring.
- **Margin outlook:** Management expects margins to stay roughly flat while investment continues. It conceded that the shift to outcome-based pricing is lagging the embedding of AI, which leaves the margin story unclear.
- **Leadership:** President Vivek Jetley, who ran Insurance and Healthcare, departed, forcing a reshuffle of the two segments.
- **Balance sheet:** Net debt climbed to $180 million from $97 million in Q2, after $205 million of year-to-date buybacks. The new $1 billion credit facility signals more M&A ahead.
Guidance moved higher again. Full-year revenue guidance is now $2.430 billion to $2.440 billion, with 15% organic constant-currency growth, versus $2.275 billion to $2.315 billion in February. Adjusted EPS guidance rose to $2.34 to $2.36 from $2.25 to $2.29. Against $1.80 billion of revenue through nine months, the outlook implies fourth-quarter revenue roughly in line with Q3, despite a full quarter of iMerit. That looks deliberately conservative, consistent with management's warning that short-cycle data and AI work, and iMerit revenue, can be lumpy.
The market setup is more demanding than it was three months ago. Shares have risen 31.0% since opening at $31.25 after the July report, to $40.93. They now sit 24.9% above the 200-day moving average of $32.76, and the price and AVWAP trend readings are positive. Investor sentiment improved from -0.13 to roughly neutral at +0.01. That is a meaningful shift from mild skepticism, but not enthusiasm. A large part of the acceleration story already appears reflected in the price.
The bottom line is that EXL's top-line momentum is real, broad-based and increasingly tied to data and AI work that commands investor attention. The guidance trajectory gives the company credibility on execution. The next leg of the story, however, depends on proving that growth can eventually lift margins rather than merely sustain them. Doing so while managing a healthcare slowdown, a leadership transition and a more leveraged balance sheet is the test that a 31% rally now requires.
Read our earnings preview for ExlService Holdings, Inc.: https://www.earningswhispers.com/article/EXLS/20756
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-08 | |
| Oct-07 | |
| Sep-30 | |
| Sep-09 | |
| Sep-02 | |
| Aug-20 | |
| Aug-18 | |
| Aug-18 | |
| Aug-12 | |
| Aug-03 | |
| Jul-29 |
