UniQure Must Prove AMT-130 Filings Are On Track After A 36% Slide
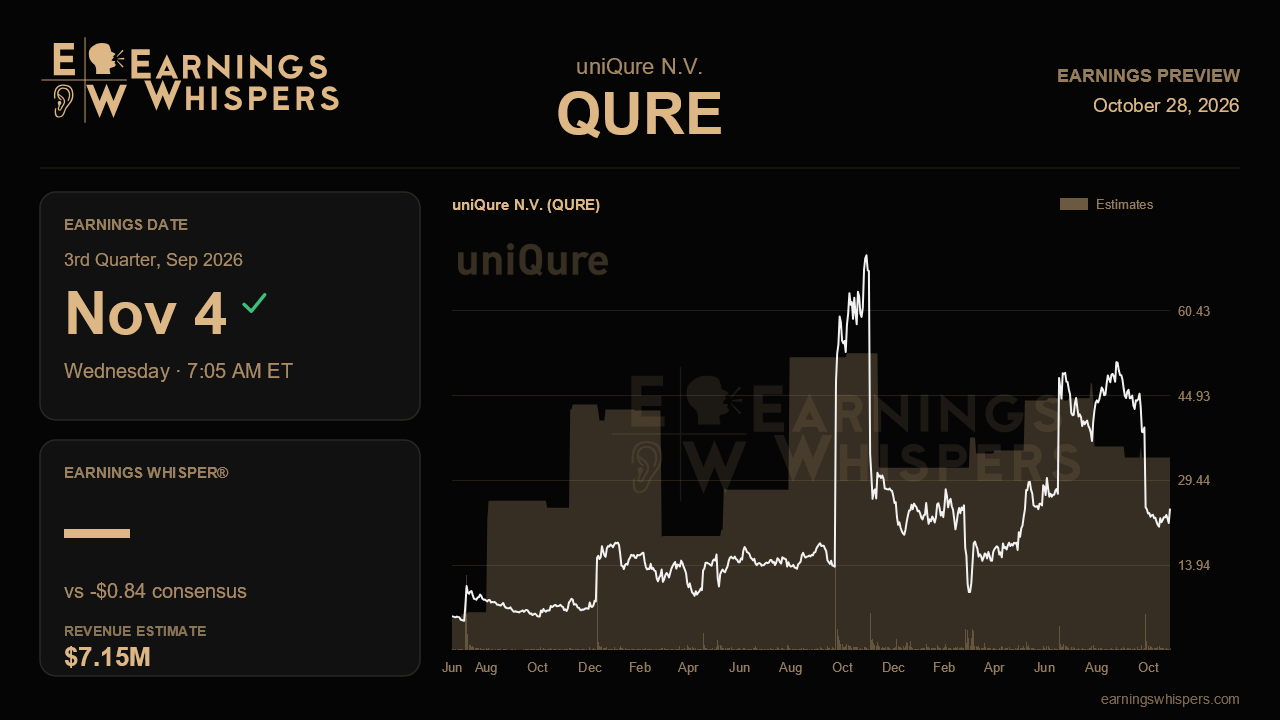
Three months ago, uniQure delivered one of the more dramatic regulatory turnarounds in recent biotech memory. The FDA had steered its Huntington's disease gene therapy, AMT-130, toward a lengthy sham-controlled Phase 3. Then a June Type B meeting produced alignment that three-year data could reasonably support an accelerated-approval filing. Management said both the US BLA and the UK marketing application were on track for the third quarter. The stock has since fallen 36%, trailing the S&P 500 by roughly 40 percentage points. That gap between an improving story and a punishing tape is what makes the November 4 premarket report worth close attention.
The headline numbers matter less than usual. Consensus calls for a loss of $0.84 per share, a 39% improvement from the $1.38 loss a year earlier and well narrower than last quarter's $1.22. Revenue is expected at about $7.2 million, nearly double the year-ago $3.7 million and up from $5.8 million in the second quarter. That revenue is license income, not product sales, so a beat or miss on the top line says little about AMT-130's commercial prospects. The narrower loss is also worth checking against spending. SG&A climbed to $17.4 million last quarter from $13.5 million a year earlier as the company hired for a launch. Further increases would be consistent with the renewed sense of commercial urgency management described, not a red flag.
The real test is whether the regulatory timeline held. The cleanest validation would be confirmation that the BLA and the MHRA submission both went in during the quarter as promised. Next would be FDA acceptance of the filing, or at least clear visibility on when acceptance should come. The four-year Phase 1-2 dataset was slated for September, covering high-dose patients at three years and both dose cohorts at four years. How management frames that durability evidence within the filing will shape the review narrative.
The overhangs management flagged last quarter are arguably more important now. The FDA wants the randomized, standard-of-care controlled confirmatory study to be well underway, and possibly fully enrolled, by the time of any accelerated approval. Yet design and sample size were still unsettled in the summer. Concrete progress would ease a major execution worry: a finalized protocol, site activation, or first patients dosed. Continued vagueness would challenge the idea that approval timing is in uniQure's hands. An expected advisory committee adds another variable, and any guidance on its timing would help frame the review calendar.
The balance sheet is the least likely source of trouble. Cash stood at $810.3 million at the end of June after a follow-on offering, and the runway was extended into 2030, explicitly covering the confirmatory trial and launch. Reaffirming that runway as spending ramps would support the case. Secondary items include whether the paused mid- and high-dose Fabry cohorts for AMT-191 have regained FDA clearance, and any update on the epilepsy program AMT-260, whose higher-dose data are due in the first half of 2027.
Sentiment has warmed noticeably, with bullish readings well above where they sat before the last report. Even so, the stock tells a more skeptical story. At $24.28 it sits below its 200-day moving average near $29.59 and much closer to its post-earnings low of $20.33 than its $51.72 high. In short, the market has given back most of the regulatory euphoria. The central question is whether uniQure can show that its filings are in, its confirmatory trial is moving, and its accelerated-approval path remains intact. If it can, the selloff looks overdone. If timelines have slipped, the market's caution may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-27 | |
| Sep-16 | |
| Sep-02 | |
| Sep-02 | |
| Sep-02 | |
| Jul-30 |
