Chemed Beats As VITAS Acceleration Carries The Quarter, But Roto-Rooter Margins Keep Slipping
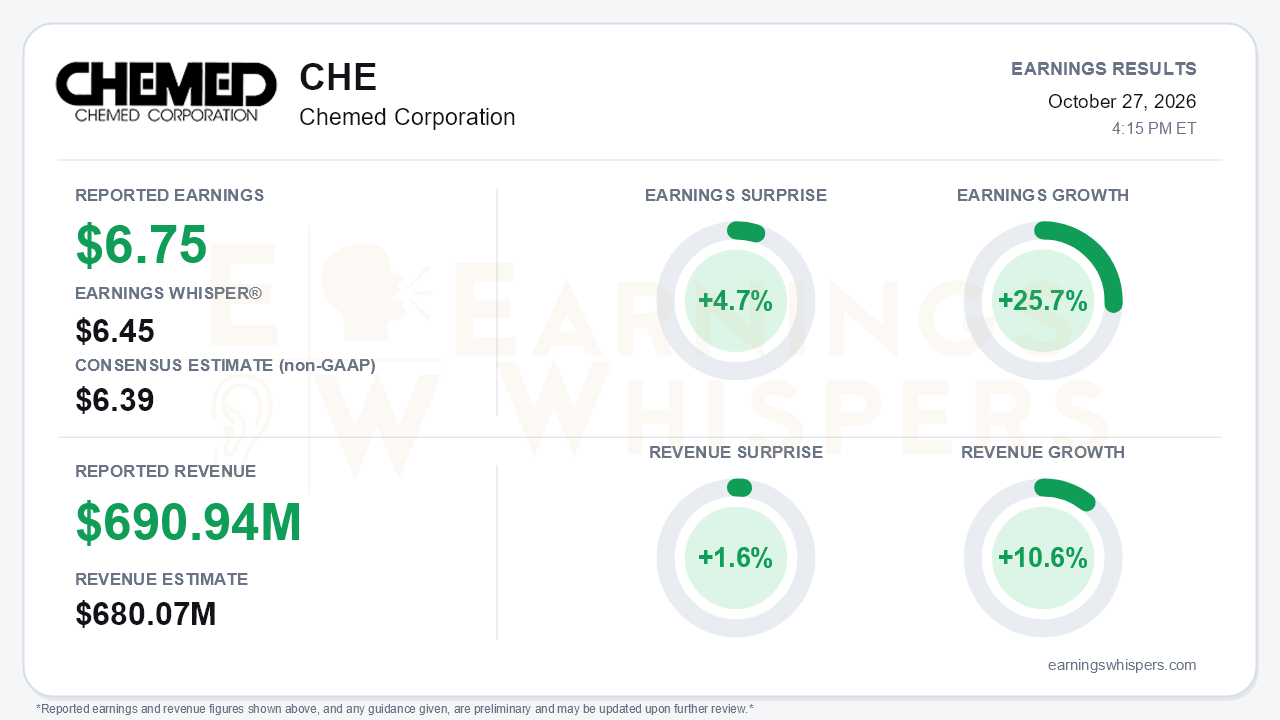
Chemed delivered a clean beat that was driven almost entirely by one segment. Adjusted EPS of $6.75 topped the $6.39 consensus by 4.7% and cleared the $6.45 Earnings Whisper number. Earnings grew 25.7% year over year. Revenue of $690.94 million rose 10.6% and beat the $680.07 million consensus by 1.6%. Management now expects full-year adjusted EPS at or slightly above the high end of its $25.00-$25.75 range. That range had already been raised three times this year. The central tension is plain: VITAS is accelerating on nearly every measure, while Roto-Rooter is buying revenue growth at the expense of margins.
The quality of the beat deserves some scrutiny. Part of the EPS growth came from below the operating line. Diluted share count fell about 9% to 13.1 million after Chemed repurchased 1.235 million shares over the past year. Those buybacks were partly funded with debt: the company now carries $236 million of long-term debt, compared with none a year ago, and interest income fell from $2.6 million to $0.3 million. Medicare Cap also helped. The cap accrual dropped to $0.8 million from $6.1 million in the prior-year quarter, adding roughly 85 basis points to VITAS revenue growth. GAAP diluted EPS was $5.45, up 22.2%, and absorbed $7.0 million of legal settlements. Still, the operating improvement is real. Consolidated income from operations rose about 29% to $96.4 million.
VITAS is the story. Revenue grew 12.2%, compared with 11.9% in Q2 and just 3.1% in Q1. Average daily census rose 9.4% to 24,428, a sharp acceleration from 6.1% in Q2 and 2.2% in Q1. Adjusted EBITDA excluding cap jumped 31.4% to $92.5 million. The margin reached 20.2%, up from 18.2% in Q2 and 16.8% in Q1, and above the 19-19.5% full-year guide set in July. The Florida combined program closed its cap year with a cushion of more than $34 million, and management expects no Florida limitation in 2027. The softer spots are worth flagging:
- Admissions growth slowed to 7.2% from 9%.
- Contractual allowances roughly doubled to $7.7 million as state and federal audits put about $12-14 million of revenue under review.
- Uncollectibles ticked up to 1.2% of revenue from 0.9%.
- Nurse wage inflation is outpacing reimbursement.
Roto-Rooter is where bears have legitimate ammunition. On the top line, demand looks healthy:
- Revenue rose 7.5%, with same-store sales up 5.5%, well above the 3-3.5% full-year guide.
- Residential growth improved to 5.2% from 1.7% in Q2.
- Commercial growth reached 9%.
- Water restoration pricing turned positive at +2.8% after multiple quarters of decline.
But adjusted EBITDA fell 2.5%, and the margin compressed 213 basis points to 20.6%. That marks a third straight quarter of erosion, from 22.5% in Q1 to 21.1% in Q2, and leaves the segment below its unchanged 21.5-22.5% full-year guide. Paid leads now account for about 60% of the mix, up from 53.4% in Q1, as competitors bid up lead costs. Marketing spend rose $4.3 million and fuel added $1.4 million, and management expects both headwinds to persist into Q4.
The forward catalysts cut both ways. The $62.5 million California franchise reacquisition brings total 2026 reacquisitions to $96 million and adds new Sacramento and San Diego branches. Over time, this strategically extends the owned-branch footprint. In the near term, management said the California territories should contribute $30-35 million of 2027 revenue but less than $4 million of EBITDA, diluting margins for 12-18 months. Another smaller franchise deal has been signed, and an HVAC service-line addition was floated. Management also signaled it wants to stop updating guidance quarterly. After a year of serial raises, that could reduce a visible source of positive revisions.
The market setup is more complicated than the surprise implies. Investor sentiment remained negative but improved, moving from -0.195 to -0.102. That is a modest thaw, not a conversion. Shares closed at $509.09, down 2.6% from the $522.94 open after the July report, so a strong earnings run has not translated into price progress this quarter. The stock does sit about 10.3% above its 200-day moving average of $461.36, indicating the longer uptrend remains intact. The Earnings Whispers trend readings lean negative, with price trend neutral and AVWAP negative. Notably, Chemed repurchased stock at $528.24 per share in Q3, above where it trades now.
The bottom line is that Chemed's beat-and-raise rests on a VITAS recovery that is now firmly established, with census, revenue and margins all accelerating and the Medicare Cap overhang largely cleared. The offset is a Roto-Rooter margin trend that is still moving the wrong way. Lead costs, fuel and dilutive franchise integrations are likely to keep pressure on that segment into 2027. Until Roto-Rooter's profitability stabilizes, investors are effectively underwriting a hospice-driven earnings story, which helps explain why the shares have stalled despite consistently better numbers.
Read our earnings preview for Chemed Corporation: https://www.earningswhispers.com/article/CHE/20747
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 8 hours | |
| 10 hours | |
| 11 hours | |
| Oct-27 | |
| Oct-15 | |
| Oct-01 | |
| Sep-16 | |
| Sep-08 | |
| Aug-06 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-01 | |
| Jun-08 |
