BXP Beats And Raises For A Third Straight Quarter As Pricing Power Emerges, But Rates And A Muted 2027 Outlook Keep Investors Skeptical
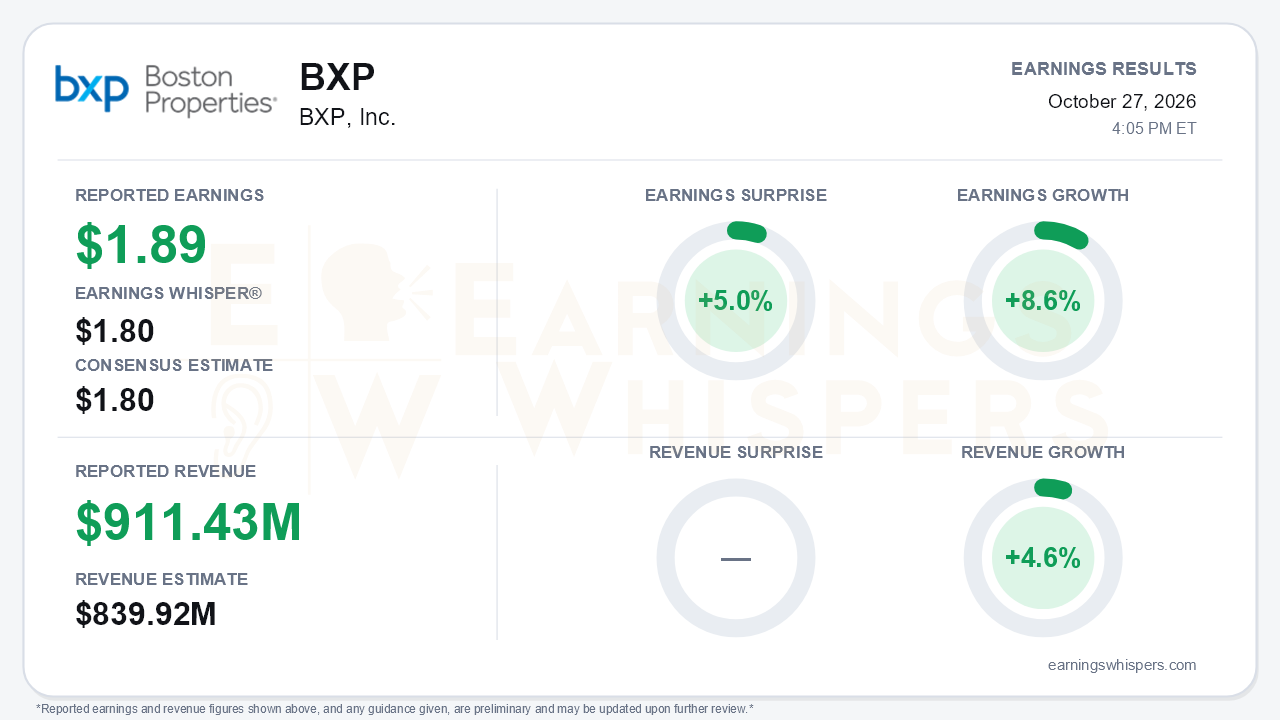
BXP delivered the kind of quarter office bulls have been waiting for. Funds from operations of $1.89 per share beat the $1.80 consensus and Earnings Whisper number by 5.0%. Revenue of $911.43 million topped the $839.92 million estimate by 8.5%. FFO grew 8.6% year over year, well ahead of the nine-month pace of $5.25 versus $5.09, so per-share growth accelerated in the third quarter. Revenue rose a steadier 4.6%. Management lifted the full-year FFO midpoint by another $0.05 to $7.06-$7.08, the third consecutive raise from an initial range of $6.88-$7.04. That is the central tension. The operating story is clearly improving, while the stock has been moving the other way, with investors focused on interest rates and a 2027 outlook management framed only as modest growth.
The quality of the beat is mostly solid but deserves some scrutiny. GAAP EPS of $0.71 swung from a $0.77 loss a year ago. That swing is less a sign of underlying improvement than a comparison against last year's $68.9 million in impairments and $145.1 million in joint-venture impairment charges. GAAP EPS also beat guidance by $0.20, largely because of $10.4 million in gains on the sales of Sumner Square and 1330 Connecticut Avenue. The FFO beat of $0.08 versus guidance came from better portfolio performance, which is the more meaningful signal. Even here, roughly $0.04 of the operating-expense benefit was timing that shifts into the fourth quarter. Earlier bond issuance will also add about $0.02 of net interest expense.
The call showed a real change in the business. Occupancy rose 100 basis points to 89.4%, the fourth straight quarterly gain, up from 86.7% at year-end 2025. That already exceeds the 89% year-end target, and management now expects about 90% for 2026 and 91% for 2027. The leased rate of 91.9% points to roughly 1.1 million square feet of future commencements, with about half expected before year-end. The discussion pipeline jumped to 2.8 million square feet from 1.7 million in the second quarter. The bigger development is that pricing power is now an explicit growth driver:
- Market rents are rising and concessions are falling.
- Mark-to-market improved about 10% over two quarters.
- Leasing spreads came in at +6.5% gross and +9.3% net.
- Salesforce Tower market rents are now 30-60% above expiring rents, up from the 30-40% cited last quarter.
Same-property NOI guidance rose again to 2.35%-2.75%.
Catalysts are substantial. Google's 206,000-square-foot lease at 500 North Capitol backfills a departing tenant two years early. At 343 Madison, BXP sold a 10.6% stake above its cost basis and closed a $1.2 billion construction loan. The project is 56% leased, up from 50%, and its expected yield has moved toward the top of the 7.5%-8% range. Disposition proceeds reached $1.37 billion. A pending sale of a 55% interest in Times Square Tower would hit the $1.9 billion target well ahead of 2028. Management also expects cash flow quality to improve in 2027 as free rent burns off and leasing costs decline.
Bears have legitimate ammunition, though:
- **2026 leasing costs:** Leasing capital and transaction costs are now projected at about $550 million, more than double the $220-250 million guided in the fourth quarter. That weighs on 2026 cash flow.
- **2027 FFO headwinds:** About $0.08 of dilution from asset sales, plus roughly $0.06 more if Times Square Tower closes. The GM Building refinancing will roll off a 3.6% rate. Capitalized interest ends as residential projects deliver. Termination income is expected to normalize from about $24 million toward $15 million.
- **Funding costs:** The new 10-year notes carry an effective yield of about 6.16%.
- **Tone on capital markets:** Management sounded more cautious. It cited a roughly 30-basis-point rise in the 10-year Treasury, expected real estate repricing, and equity capital being pulled toward AI investment.
- **Weak pockets:** West Los Angeles and Colorado Center remain soft, and leasing spreads were negative in Boston's urban edge (-28% at Quarry) and San Francisco CBD.
The market has leaned toward that cautious read. Shares fell 13.4% from $70.33 at the open after the July report to $60.89. That leaves the stock about 2% below its 200-day moving average of $62.14. Investor sentiment moved from roughly neutral at -0.01 to a clearly negative -0.26, a meaningful deterioration heading into the print. Price and AVWAP trend readings are both negative, consistent with a stock that has been sold despite steadily improving fundamentals.
The bottom line is that BXP's quarter strengthened the operating case. Occupancy is ahead of plan, rents are turning higher, the leasing pipeline is expanding, and guidance keeps moving up. The open question is whether that momentum can outrun rising rates, heavy leasing costs and known 2027 dilution. Investors entered the report skeptical. The fundamentals argue the skepticism is increasingly about the cost of capital rather than demand for BXP's buildings.
Read our earnings preview for BXP, Inc.: https://www.earningswhispers.com/article/BXP/20745
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-01 | |
| Sep-29 | |
| Sep-16 | |
| Sep-15 | |
| Sep-10 | |
| Aug-17 | |
| Jul-31 | |
| Jul-30 | |
| Jul-29 |
