BrightSpire Capital Misses As Growth Plan Gives Way To Liquidity Preservation And Dividend Coverage Slips Again
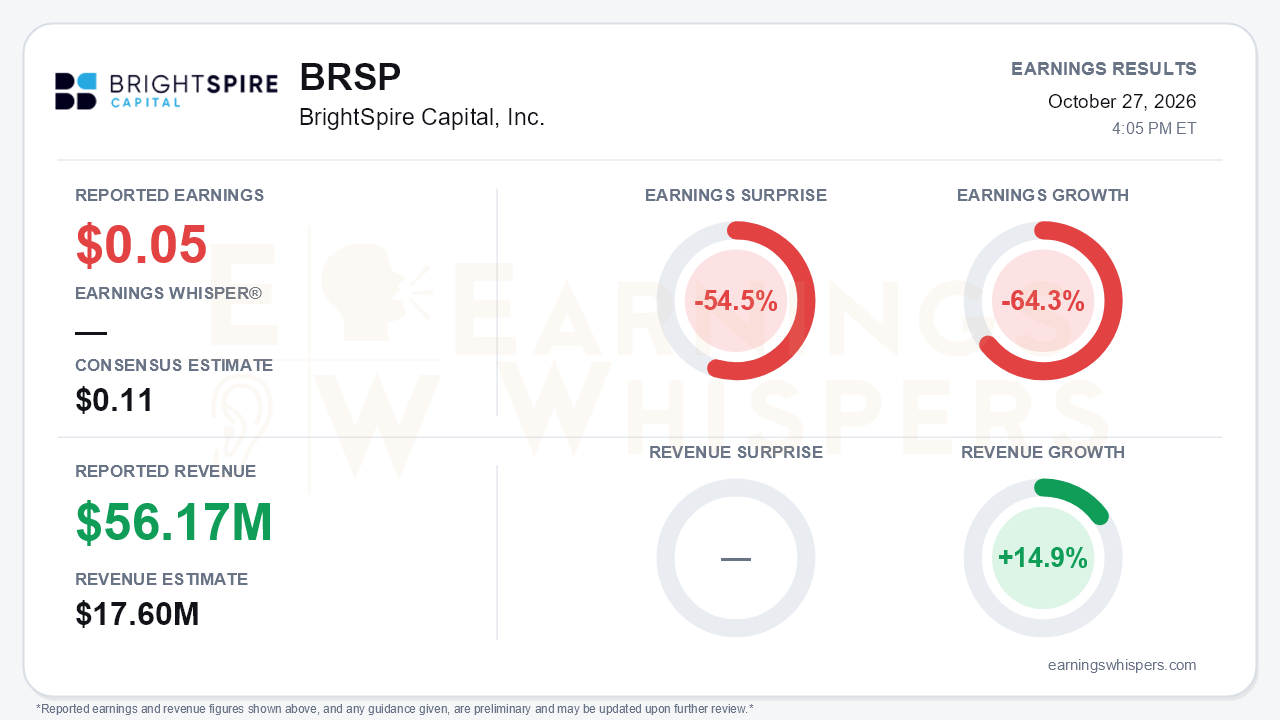
BrightSpire Capital (NYSE: BRSP) reported third-quarter earnings of $0.05 per share, well short of the $0.11 consensus, a 54.5% miss, and down 64.3% from a year ago. Revenue of $56.17 million beat the $17.6 million consensus by 219.1% and grew 14.9% year over year. For a commercial real estate lender, though, the revenue beat says little about earnings power. The real story is a strategic retreat. Management dropped its $3.5 billion year-end loan book target, pushed dividend coverage out again with no new date, and moved from expansion to preserving liquidity. That is the central tension: the balance sheet is cleaner and better financed, but the earnings path that was supposed to support the dividend has slipped further away.
The quality of the quarter deserves scrutiny because the company's own measures tell different stories. GAAP net income attributable to common stockholders was $46.9 million, or $0.37 per share. Nearly all of that came from a $60.3 million gain on the sale of the Albertsons triple-net lease distribution centers, the company's largest asset. Distributable Earnings fell to $0.08 from $0.12 in the second quarter after $7.5 million of specific reserves. Adjusted Distributable Earnings edged up to $0.14 from $0.13 but still trailed the $0.16 quarterly dividend. The Albertsons gain lifted GAAP book value to $7.08 from $6.81. Undepreciated book value, however, kept falling, to $7.87 from $8.10 in Q2, $8.24 in Q1 and $8.44 at the end of 2025. Excluding the one-time gain, the underlying earnings trend is weakening.
The operating picture is mixed rather than broken. Originations were solid at $272 million of committed capital, with another $66 million closed or in execution after quarter end. The loan book reached about $3.1 billion, up from $2.9 billion in Q2 and roughly 30% higher year over year. The fifth CLO, and second of 2026, closed as promised. About two-thirds of loan financing is now non-recourse and not marked to market, a company record. Liquidity rose to $181 million from $131 million. On the call, however, management guided the fourth-quarter loan book to flat or only modestly higher, effectively deferring the roughly $4 billion mid-2027 goal, with new lending expected to resume in Q1 2027. The CEO's tone shifted from Q2's "full speed ahead" to "take our cues from the market."
The reasons for that shift are the key risks. The 10-year Treasury yield reached about 5.37%, nearly a 100 basis point move since June 30. That is above the 5% level the CEO had flagged in Q2 as concerning, and he warned that cap rates could expand if yields approach 5.5%. CLO AAA and warehouse spreads widened by 10 to 15 basis points, some property sales were repriced or pulled, and management cited concerns over financing for AI and hyperscaler projects spreading into credit markets. Credit quality also slipped:
- Two related Blue Bell, Pennsylvania office loans were downgraded to risk rank 4 ahead of maturity.
- A third retail triple-net property went into receivership, with a $3.4 million impairment.
- The general CECL reserve rose to $107 million, or 332 basis points, from $100 million in Q2 and $87 million in Q1.
- Management said pipeline quality has deteriorated and that it is widening multifamily spreads.
There was real progress on problem assets. Two multifamily REO properties in Mesa and Fort Worth were sold, and the Santa Clara land parcel is being marketed. The Denver office watch-list loan was resolved, and the property behind the largest office loan is under contract. Recycling about $100 million of capital from the Albertsons sale at an estimated 150 basis points higher return on equity is the clearest path back toward coverage. That redeployment, however, now depends on market conditions.
The dividend coverage timeline is the credibility problem. Management targeted mid-2026 on the Q4 2025 call, year-end 2026 in Q1 and Q2/Q3 2027 in Q2. Now there is no date, and management cited a shortfall of 2 to 3 cents per quarter. Buybacks also slowed, to 2.1 million shares at $4.81 versus 3.8 million at $5.46 in Q2, and are now deprioritized despite the stock's deep discount to book value. Investors noticed. Earnings Whispers investor sentiment fell sharply, from roughly neutral at -0.01 after the prior report to -0.69. Shares have dropped 27.2% since the open following the July report, from $5.11 to $3.72, and sit about 30% below the 200-day moving average of $5.28. The price trend and AVWAP readings remain negative.
The bottom line is that BrightSpire traded growth for safety this quarter. Record non-mark-to-market financing, higher liquidity and steady REO and watch-list resolutions are real gains. Against them stand a missed earnings estimate, falling undepreciated book value, rising reserves, an abandoned loan book target and a dividend coverage date that has slipped once more. Bears have legitimate ammunition. Until lending resumes and Adjusted Distributable Earnings closes the gap to the $0.16 dividend, the stock's steep discount reflects doubt about how durable the payout is.
Read our earnings preview for BrightSpire Capital, Inc.: https://www.earningswhispers.com/article/BRSP/20743
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-09 | |
| Oct-01 | |
| Sep-21 | |
| Sep-14 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-06 | |
| Jun-15 | |
| May-26 | |
| Apr-30 | |
| Apr-28 |
