One Stop Systems Beats And Lifts Growth Outlook Again, But Cash Burn And A New ATM Keep The Stock Under Pressure
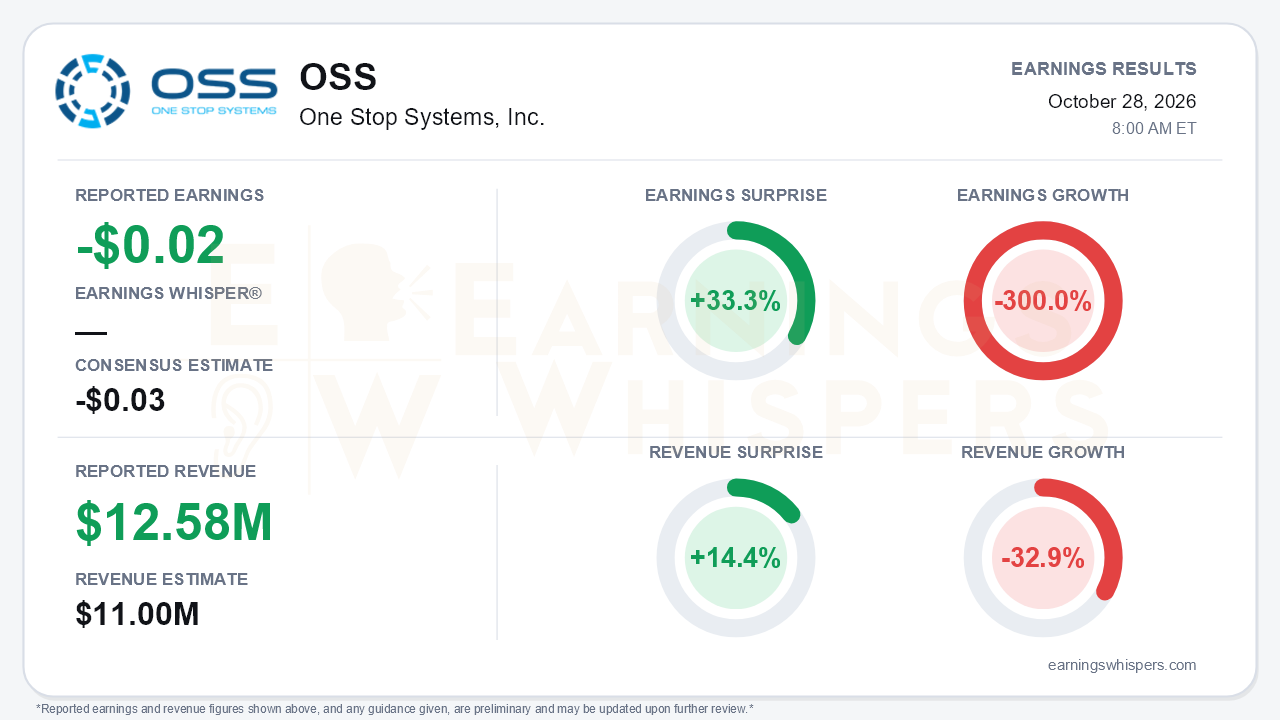
One Stop Systems delivered the kind of quarter that usually changes a narrative: a loss of $0.02 per share against a consensus estimate of -$0.03, a 33.3% earnings surprise, and revenue of $12.58 million that topped the $11.0 million consensus by 14.4%. Management followed with its second straight guidance raise, now calling for roughly 40% full-year revenue growth, or about $45 million, up from 25% to 30% last quarter and 20% to 25% earlier in the year. The central tension is that the growth story keeps getting stronger while the balance sheet gets thinner. Shares have fallen 43.9% since the open after the August report.
The growth comparisons need context. Earnings Whispers' normalized figures show earnings down 300.0% and revenue down 32.9% year over year. The company reports continuing-operations revenue up 35.9%, from $9.3 million to $12.6 million. The gap appears to come from the comparison base: the prior-year quarter included the Bressner business, sold in December 2025 and now reported as discontinued operations. That year-ago period produced $0.01 per share of consolidated net income, compared with a $0.02 GAAP loss from continuing operations this quarter. On the company's continuing basis, the business is growing quickly, though growth slowed from 62% in the second quarter and 55% in the first. Non-GAAP net income was $0.3 million, or $0.01 per share. Adjusted EBITDA was $0.3 million. Excluding $0.5 million of bad debt tied to a former customer's bankruptcy and $0.4 million of legal fees, it would have been about $1.2 million, or nearly 10% of revenue. Bears can fairly note that the GAAP operating loss widened to $0.8 million from $0.4 million, partly because stock-based compensation roughly doubled to $0.9 million.
The call made a credible case that demand is broadening. Commercial customers drove the quarter, led by:
- a medical imaging OEM serving breast cancer screening;
- a commercial aerospace in-flight entertainment program;
- initial deliveries to a new customer building autonomous energy nodes for specialized data centers.
These sales complemented continued defense strength. Gross margin of 42.6% fell 300 basis points from a year ago on mix but improved sharply from 39.1% in the second quarter. Full-year margin guidance rose to 40% to 42% from about 40%. Adjusted EBITDA guidance is now quantified at $0.5 million to $1.0 million. Management said all 2026 guidance is already in backlog and described momentum as accelerating. The company now supports 14 multi-year programs, compared with one three years ago.
Forward catalysts are meaningful but unproven. The Gen5 4UP Max expansion system qualified with a tier-one global enterprise computing platform provider, which opens a broader enterprise AI and data center channel. Management expects several multimillion-dollar orders to close in the fourth quarter. It also cited potentially transformative opportunities of $100 million or more over three to four years, which are explicitly excluded from guidance. Several risks offset that pipeline:
- Year-to-date book-to-bill of 1.46x is still healthy but has moderated from about 1.8x in the first quarter and 1.7x in the second.
- The guidance implies a lower fourth-quarter gross margin on lower-margin production and customer-funded development work.
- Long lead times for memory, switch chips and GPUs are expected to extend into 2027.
- Army program timing remains undefined.
The balance sheet is where bears have the strongest case. Continuing operations used $12.4 million of cash over nine months. That figure includes the $6.25 million legal settlement and a $7.8 million inventory build, and $5.6 million of milestone collections slipped from the third quarter into October. Cash and short-term investments fell to $18.9 million from $31.4 million at the end of the second quarter. Management now expects slightly negative full-year operating cash flow. The newly established at-the-market equity program signals possible dilution, which matters more with the share price this depressed.
Investor sentiment improved meaningfully into the report, rising from -0.09 to 0.35. Price action, however, has been brutal. At $6.76, the stock sits 40.3% below its 200-day moving average and 53.1% below its inter-earnings high of $14.42, set on August 17. It touched a period low of $5.73 on October 26, two days before the release, so it entered earnings near the bottom of its range. The trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative.
The bottom line is that OSS answered the demand question convincingly, with record revenue, a second consecutive guidance raise, and a tier-one enterprise qualification that widens its market. Funding remains the open question. Until fourth-quarter orders close, collections normalize and the cash decline slows, the ATM program and shrinking cash balance will compete with the growth story for investors' attention.
Read our earnings preview for One Stop Systems, Inc.: https://www.earningswhispers.com/article/OSS/21649
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-12 | |
| Oct-08 | |
| Sep-16 | |
| Sep-16 | |
| Aug-18 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-21 | |
| Jun-23 |
