MGP Ingredients Beats Lowered Bar On Cost Control, But Q4 Ramp And Refinancing Test The Reaffirmed Outlook
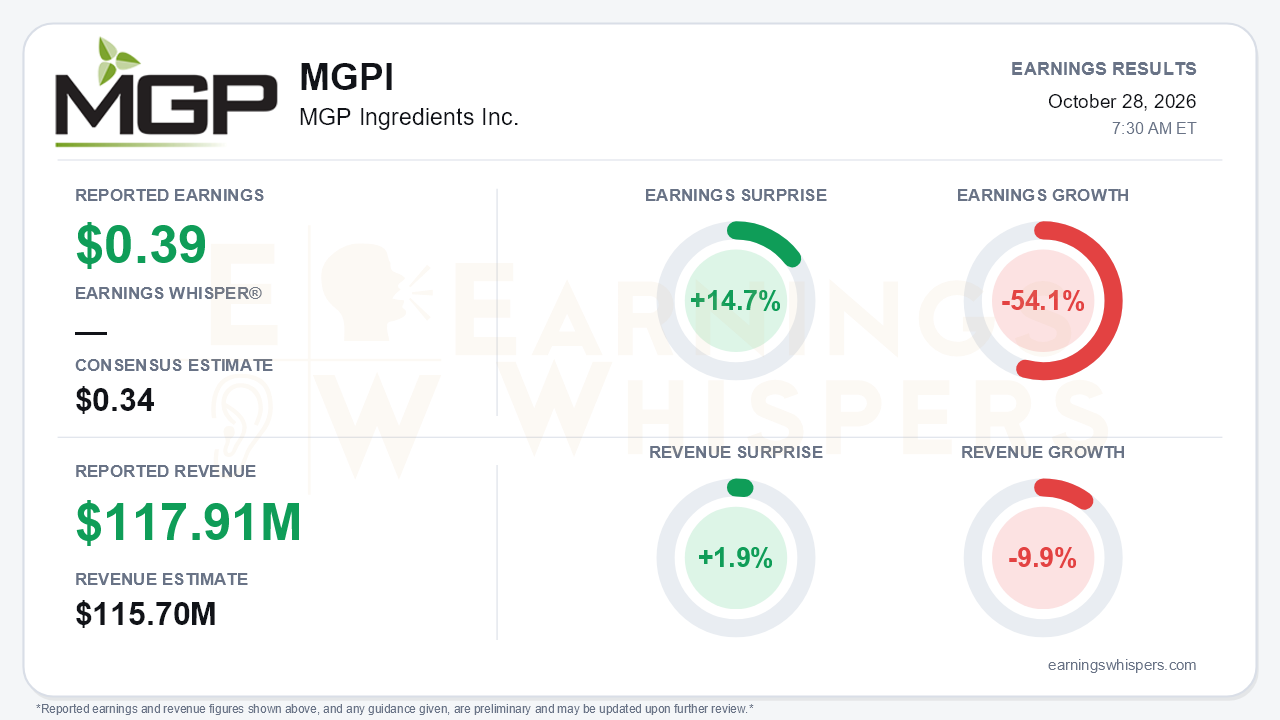
MGP Ingredients delivered a cleaner quarter than its sliding share price implied, but the beat came from cost discipline and cash generation rather than any recovery in the core businesses. Adjusted EPS of $0.39 topped the $0.34 consensus by 14.7%, and revenue of $117.91 million beat the $115.7 million estimate by 1.9%. Those beats sit against steep declines: earnings fell 54.1% from a year ago and revenue dropped 9.9%. On a GAAP basis, EPS was $0.32 versus $0.71. Management reaffirmed full-year sales guidance of $480 million to $500 million, adjusted EBITDA of $90 million to $98 million, and adjusted EPS of $1.50 to $1.80. The central tension is that the company beat its own internal targets while segment margins and distilling demand kept deteriorating.
The quality of the beat deserves scrutiny. Consolidated gross margin fell roughly 350 basis points to 34.3%, down from 37.4% in the second quarter. Adjusted EBITDA fell 33% to $21.5 million, below the second quarter's $27.6 million. Every segment lost gross margin. Branded Spirits slipped 280 basis points to 50.2% on bottling maintenance and contractor costs. Distilling Solutions fell to 32.4% from 38.7% in the prior quarter. Ingredient Solutions collapsed to just 6.0% from 10.3% a year ago, hurt by higher waste starch costs and an extended plant shutdown. What held the quarter together was below the gross line: lower advertising spend, agency consolidation savings, and strong cash generation. Third-quarter operating cash flow reached $31.9 million, debt fell $28.4 million, and net leverage of 3.6x came in better than planned.
The call preserved pockets of a credible growth story inside the weakness:
- **Branded Spirits:** Penelope Bourbon grew 12%, extending a run of 10% and 13% gains in the first two quarters. Mid-priced brands rose 6%, and six of ten core brands are now growing versus one a year ago. Excluding the private label "other" category, segment sales were flat despite distributor system cutovers. Segment operating income rose 3%.
- **Distilling Solutions:** White goods and co-products rose 32%. RTD and private label customers are now more than 25% of brown and white goods product sales, with that business up 90% year to date.
- **Ingredient Solutions:** Specialty protein sales rose 15%, the plant has run at roughly 90% utilization for three straight months, and the segment is fully booked.
Offsetting those positives, Premium Plus slipped 1% after growing 5% in the second quarter, and Yellowstone fell 23%. Brown goods sales dropped 47%, and price/mix turned negative after being favorable in the first half as the company matched prices on aged whiskey spot sales. Multinational customers for new distillate remain in a holding pattern, which limits visibility into 2027.
The headline label that guidance was "revised" conflicts with the release, which reaffirmed every consolidated target. The more accurate reading is that the totals held while the components shifted beneath them:
- Adjusted SG&A is now guided to about 16% of sales, versus roughly 18% in the initial outlook.
- Branded Spirits advertising and promotion was trimmed to 12% to 13% of segment sales, from 13% to 14%.
- The Ingredient Solutions margin outlook has fallen across the year, from mid-to-high teens to high-single or low-double digits.
- The low-20s Ingredient margin target for 2027 was not reiterated.
The guidance also implies a demanding fourth quarter. Year-to-date sales of $348.7 million imply fourth-quarter sales of roughly $131 million to $151 million. Year-to-date adjusted EBITDA of $64.1 million implies roughly $26 million to $34 million in the final quarter. Both are well above third-quarter levels, and the call flagged that Ingredient Solutions needs a sequential ramp of more than 30%.
Bears also have legitimate balance-sheet ammunition:
- Most or all of the $201 million in 1.875% convertible notes are expected to be put on November 16, with refinancing at higher rates. Quarterly interest expense has already roughly doubled year over year to $3.4 million.
- The credit agreement was amended to add back up to $20 million of receivable losses from specified customers through 2027.
- The company elected an elevated leverage-ratio period through the first quarter of 2027.
Management framed the covenant change as precautionary. Even so, it sits alongside a $2.1 million credit-loss provision taken earlier this year.
On the catalyst side, the rebrand takes effect November 2. The release identifies the new name as Sempreon, Inc. under the ticker CASK. The call analysis renders it as Sempriam/CASC, and the release should be treated as authoritative. Additional catalysts include a 10-year bourbon launch under the MGP brand, more than $3 million in annual agency savings, an initial insurance recovery for the 2025 equipment outage, and a hemp-alternative test through beer distributors in early 2027.
The market had already priced in a great deal of pessimism. Shares fell 23.4% from the opening after the July report to $15.32. That leaves the stock 16.8% below its 200-day moving average of $18.42 and 25% below the inter-earnings high. The stock did rebound 23.3% from a 52-week low of $12.42 set October 5, so it entered the report off its lows but deep in a downtrend. Investor sentiment improved modestly, rising from 0.035 to 0.109; expectations are slightly positive but far from enthusiastic. The Earnings Whispers trend readings are largely neutral, with only AVWAP positive, consistent with a stock that has stabilized rather than turned.
The bottom line is that MGP cleared a low bar through cost cuts, deleveraging, and cash flow while its margins, brown goods demand, and Ingredient profitability continued to erode. The reaffirmed guidance now depends on a fourth-quarter acceleration the third quarter did not foreshadow, and that ramp must arrive while the company refinances its convertible notes at higher rates.
Read our earnings preview for MGP Ingredients Inc.: https://www.earningswhispers.com/article/MGPI/20865
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-05 | |
| Sep-11 | |
| Sep-10 | |
| Sep-09 | |
| Sep-02 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 |
