STAG Industrial Matches On Core FFO And Raises Guidance A Third Time, But Slowing Per-Share Growth And Stalled Acquisitions Keep The Stock Under Pressure
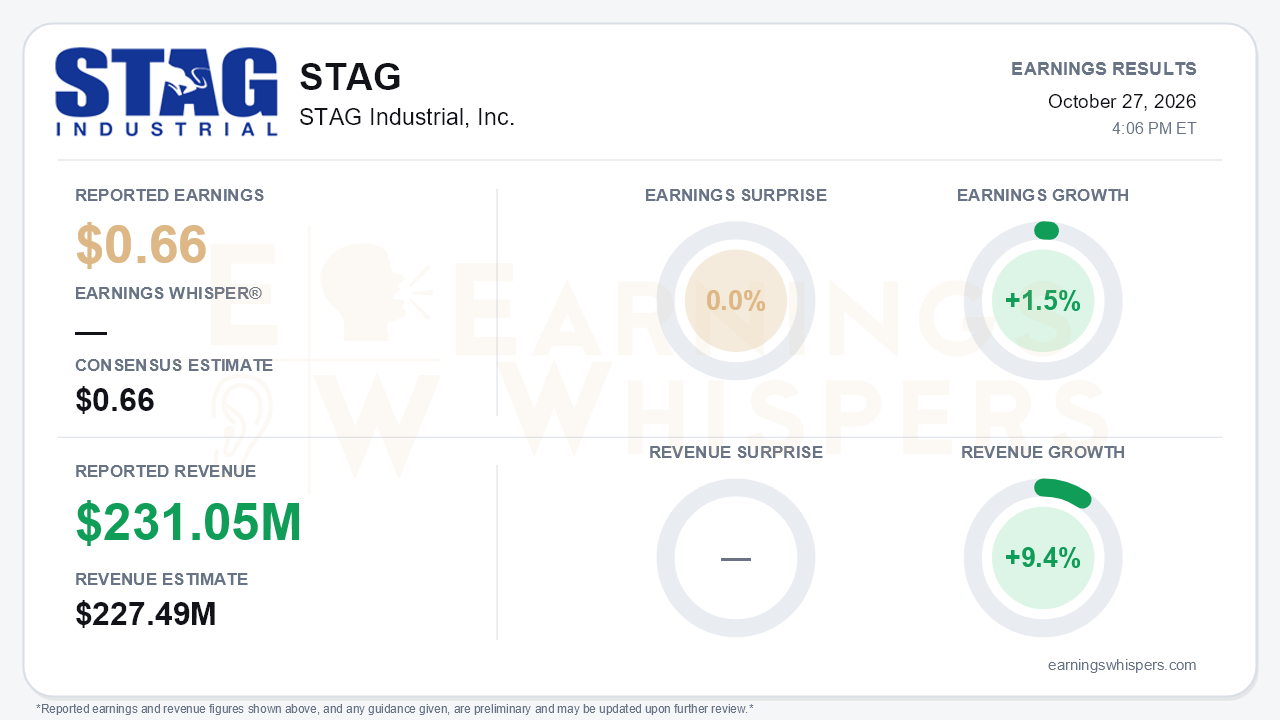
STAG Industrial delivered third-quarter Core FFO of $0.66 per share, exactly in line with consensus, on revenue of $231.05 million that beat estimates by 1.6%. Revenue grew 9.4% year over year, but per-share earnings rose only 1.5%. That gap is the central tension of the quarter. The property-level business is improving on nearly every operating measure. Management raised full-year guidance for the third consecutive quarter. Yet the earnings that reach shareholders are growing at a pace that has decelerated sharply, from 6.6% in the first quarter to 3.2% in the second and 1.5% now. Investors have been focused on that slowdown, and the stock has fallen accordingly.
The quality of the headline numbers deserves scrutiny in both directions. GAAP net income per share jumped to $0.37 from $0.26. That increase was driven largely by $24.2 million of gains on property sales, compared with just $2.2 million a year ago, so it overstates the underlying improvement. The non-GAAP picture shows where the leakage occurs:
- Cash NOI rose 10.1% and total Core FFO grew 4.1%.
- Interest expense climbed to $39.1 million from $31.7 million.
- G&A rose to $14.8 million from $12.2 million.
- A roughly 3% larger diluted share and unit count compressed per-share growth further. On a basic basis, Core FFO per share was flat at $0.66.
Same Store Cash NOI grew a healthier 3.5%. However, management acknowledged that the figure included a roughly 30-basis-point timing benefit tied to a First Brands-affiliated tenant, which will reverse in the fourth quarter.
The call preserved a credible organic growth story. Commenced cash leasing spreads accelerated to 23.8%, up from 19.8% in the second quarter and 20.9% in the first. Retention was 90.3%, well above the 75.8% year-to-date rate. Year-to-date credit loss has run at just 12 basis points, against an initial guide of 50. Management raised several 2026 targets:
- Core FFO guidance to $2.64-$2.66, from $2.61-$2.65.
- Cash same-store NOI growth to 3.5%-3.75%.
- Average occupancy to 96.75%-97.25%.
National absorption improved to roughly 75 million square feet. Data center-related leasing has reached 2.5 million square feet since 2025, about 30% of new leasing this year. That is an increasingly meaningful demand source.
The most important forward-looking development was the 2027 framework. Management has already addressed 40% of next year's leasing plan, up from 35% at the second-quarter report, at 12% cash spreads, or 17.5% excluding fixed-rate renewals. It expects roughly 15% spreads in 2027 and market rent growth of 2%-4%, versus about 1.6% this year. Combined with roughly 3% annual rent bumps, flat occupancy and 50 basis points of credit loss, that points to approximately 5% cash same-store growth. If delivered, that would be a clear step up from 2026.
External growth is moving the other way. Third-quarter acquisitions fell to $107.9 million from $287.1 million in the second quarter. Full-year acquisition guidance was narrowed to $530-$600 million, which implies little fourth-quarter activity as rate volatility pauses deal flow and retrades surface. Several other measures also moved against the company:
- Liquidity declined to $546 million, from $614 million in the second quarter and $806 million in the first.
- G&A guidance rose by $2 million at the midpoint.
- The 284,000-square-foot Reno North Valleys development remains unleased and is the largest lease-up risk in the pipeline.
Management framed the 25-35 basis points of cap rate expansion as a potential opportunity, particularly among stressed smaller developers. The new BBB rating from S&P, STAG's third investment-grade rating, improves its access to the public bond market.
The capital-allocation signals are notable. STAG sold forward equity this year at about $39 per share. With shares now at $36.18, the board authorized a new $250 million buyback, and management said it has no need for public bond or equity capital. That is an implicit statement that the stock trades below management's view of value. The market has not shared that view. Shares are down 9.8% since the open after the July report and sit about 4.5% below their 200-day moving average of $37.90. Investor sentiment remained negative and weakened modestly, slipping to -0.33 from -0.26. The Earnings Whispers price and AVWAP trend readings remain negative, consistent with sustained selling despite rising guidance.
The bottom line is that STAG's operating engine is accelerating, with rising spreads, low credit loss, three straight guidance raises and a believable path to roughly 5% same-store growth in 2027. Higher interest costs, share dilution and a stalled acquisition program are absorbing much of that strength before it reaches per-share results. Until Core FFO growth visibly re-accelerates, bears have legitimate ammunition. The improving leasing story alone has not been enough to change how the market is pricing the shares.
Read our earnings preview for STAG Industrial, Inc.: https://www.earningswhispers.com/article/STAG/20800
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-01 | |
| Aug-31 | |
| Aug-06 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-07 | |
| Jul-01 | |
| May-28 | |
| May-13 | |
| Apr-30 | |
| Apr-28 |
