OneSpaWorld Beats And Lifts The Floor On Guidance, But Slowing Top-Line Growth Keeps The Debate Alive
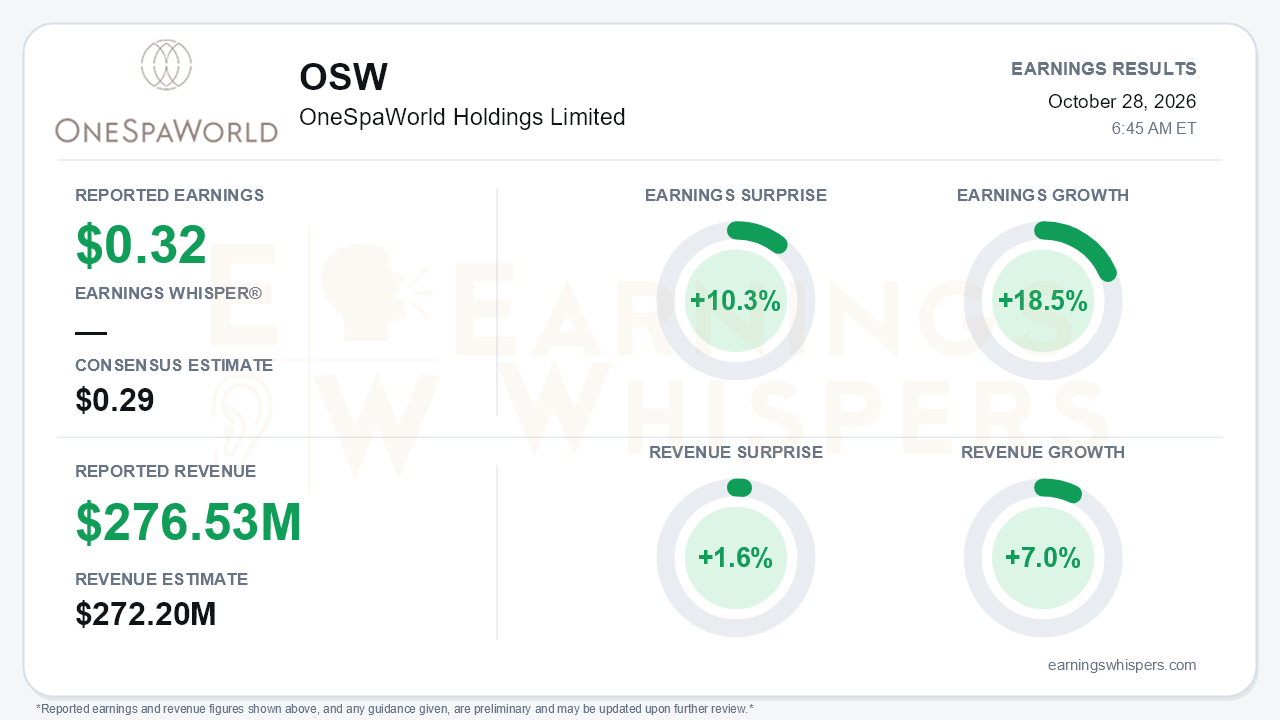
OneSpaWorld (NASDAQ: OSW) delivered another clean beat in the third quarter, reporting earnings of $0.32 per share against a $0.29 consensus, a 10.3% surprise. Revenue of $276.53 million topped the $272.2 million estimate by 1.6% and exceeded the top of management's own $268–273 million guide. Earnings grew 18.5% year over year, outpacing 7.0% revenue growth by a wide margin. That gap is the central tension in the story. Profitability and per-guest economics are improving, while headline revenue growth keeps slowing, from 13% in the first quarter to 9% in the second and 7% now. The fourth-quarter guide implies roughly 6% growth excluding exited operations.
The quality of the beat holds up reasonably well. The normalized $0.32 figure sits between GAAP diluted EPS of $0.28, up from $0.23, and the company's adjusted EPS of $0.34, up from $0.30. On every basis, the quarter was a record. Income from operations rose 14% to $30.0 million, and adjusted EBITDA grew 12% to $39.2 million. Earnings growing faster than sales came from mix rather than cost-cutting. Service revenue rose 9% while cost of services rose only 7%, producing a record 18.5% service margin. The 52% jump in administrative expense looks alarming but is largely a reclassification: UK and Italy reorganization costs shifted out of payroll and into third-party fees. Investors should also note that per-share growth got a lift from buybacks. Diluted shares fell to 101.9 million from 103.6 million, and the company repurchased $37.2 million of stock in the quarter alone.
Beneath the decelerating top line, the operating metrics actually strengthened. Average guest spend rose 3.3%, an acceleration from 1.2% in the second quarter and 2% in the first. Management attributed the gain to mix and retail attachment, not pricing. Pre-booked revenue grew 20%, up from 14% last quarter, and now represents 23.2% of service revenue versus 21.5% a year ago. Management set a target of roughly 30% over the next two to two-and-a-half years. Average weekly revenue per ship climbed to nearly $100,000 from $95,675. MediSpa, about 9.5% of revenue, is growing double digits. Management's tone on European and Caribbean demand was notably more confident than on the first-quarter call, when Europe softness was a concern. The slowdown in reported revenue owes much to the exit of Asia resorts, hotel closures that cut destination revenue by $1.4 million, and the UK/Italy product reorganization.
The guidance raise deserves a closer read. Fiscal 2026 revenue guidance moved to $1.033–1.038 billion and adjusted EBITDA guidance to $138–140 million. This is the third consecutive midpoint increase, and implied EBITDA growth stepped up to 13% from 10%. However, the top end of both ranges is unchanged; management raised the floor rather than the ceiling. The fourth-quarter outlook of $248–253 million in revenue and $32–34 million in EBITDA was characterized as in line. Several forward indicators also softened:
- Dynamic pricing, once framed for the back half of 2026, now looks like the fourth quarter of 2027 at the earliest.
- Remaining 2026 new-ship introductions were cut to two from three.
- Forward-booking growth eased to 18% from 20%.
- Management said AI is not transformative to revenue in the near term.
- The geopolitical and oil backdrop was still described as dynamic.
On the positive side, catalysts include the Azamara and Silversea renewals, Longevity Lounges approved for upcoming new builds, and added Caribbean capacity in 2027 that management called a "huge tailwind."
Capital returns were the other headline. The company completed its $75 million buyback, authorized a new $100 million program, and raised the quarterly dividend 25% to $0.0625. This is a clear signal of confidence in asset-light free cash flow. The balance sheet, however, is lean. Cash stood at $32.1 million against $70.5 million of debt, so the pace of buybacks will depend on continued cash generation.
The market setup is more complicated than the beat implies. Investor sentiment slid from essentially neutral (-0.01) to clearly negative (-0.27) heading into the report. Shares are down 6.8% since opening at $26.78 after the July report. The stock fell as low as $21.21 in early September before recovering to $24.95, about 17.6% above that low, 8.8% below the inter-earnings high, and 5% above the 200-day moving average. The Earnings Whispers trend signals are mixed: momentum and AVWAP are positive, but the price trend remains negative.
The bottom line is that OneSpaWorld is earning more from each guest and converting a slowing top line into faster profit growth and larger shareholder returns. Bears still have legitimate ammunition. Revenue deceleration, a delayed pricing lever, fewer new ships, and a guidance raise that lifted only the low end all argue that the next leg of growth must come from spend and mix rather than fleet expansion.
Read our earnings preview for OneSpaWorld Holdings Limited: https://www.earningswhispers.com/article/OSW/21014
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| Oct-21 | |
| Oct-21 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 | |
| Jun-30 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 | |
| Apr-22 | |
| Mar-31 | |
| Mar-05 |
