Axcelis Must Prove Its Raised Outlook Can Survive A Gross Margin Squeeze And A Sliding Stock
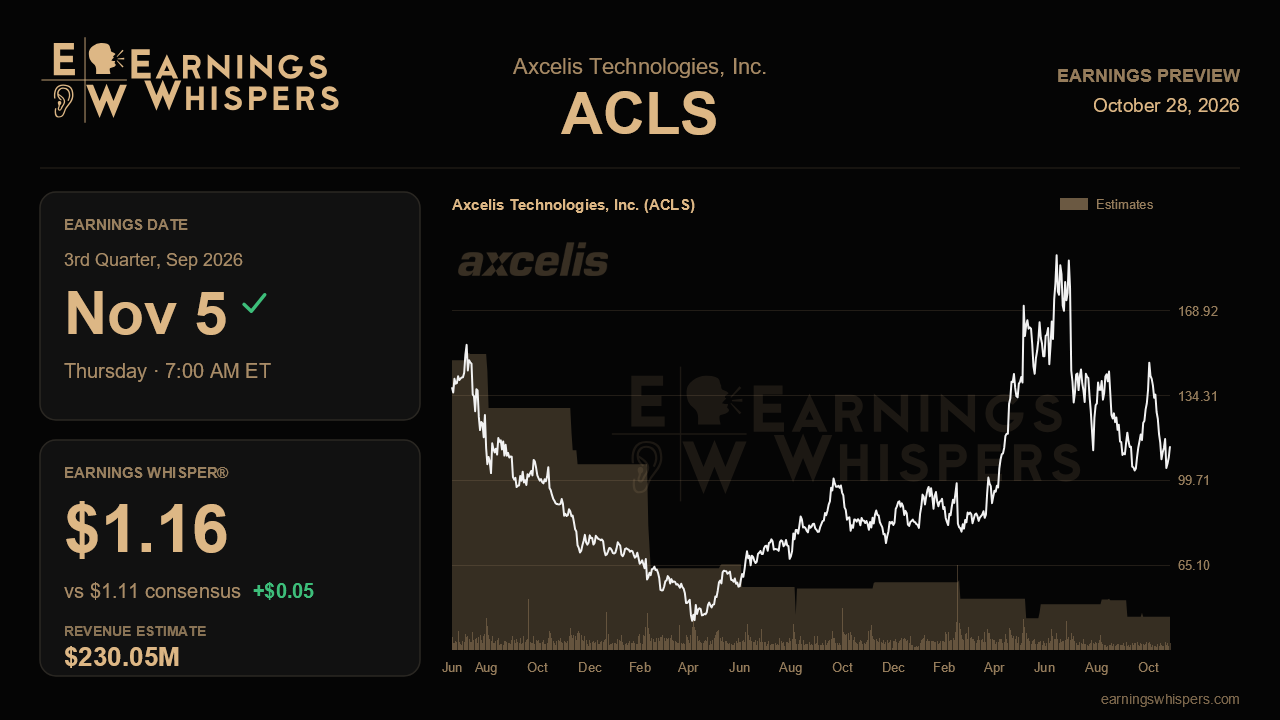
Three months ago Axcelis finally stopped telling investors that 2026 would look like 2025. After two straight calls reaffirming a roughly flat year, management raised its outlook to year-over-year growth, guided the third quarter well above where the Street had been, and even described 2027 as another growth year. The market's response since then has been unkind. The shares have fallen about 17% while the S&P 500 has gone essentially nowhere, which sets up the November 5 report as a test of whether the recovery story is real or whether investors were right to fade it.
The expectations bar sits squarely on management's own numbers. Consensus calls for non-GAAP earnings of $1.11 per share on revenue of $230.1 million, matching the company's guidance of roughly $1.11 and $230 million almost to the penny. Before that guidance was issued, analysts were at $1.03 and $215 million, so the Street has simply adopted the company's view rather than getting ahead of it. The Earnings Whisper of $1.16 is modestly higher, implying that a clean beat rather than an in-line print is what the more engaged investors expect. Revenue growth of about 7.7% from the year-ago $213.6 million is modest, but the sequential step up from $215.2 million in the second quarter is the more meaningful signal. Earnings are a different story: the year-ago quarter produced $1.06, so even hitting guidance means only slight per-share growth despite higher sales.
That gap points to the central swing factor, gross margin. Second-quarter gross margin came in at 42.7%, just shy of the 43% target and well below the 47.3% posted in the fourth quarter of 2025. Management blamed a richer mix of lower-margin memory tools and higher services costs. If power and general mature logic are truly recovering as described, the mix should tilt back toward more profitable products over time. A margin that holds steady or improves toward the mid-40s would suggest the recovery is broadening in a healthy way; another slip would raise the uncomfortable question of whether Axcelis is buying growth at the expense of profitability.
The demand evidence matters just as much. Management said power had moved from digestion into recovery, with first-half bookings above the two-year average and the second half expected to be stronger still. Two new silicon carbide customers in China and orders for high-energy channeling in superjunction devices were cited as proof. Silicon carbide revenue dipped in the second quarter on timing, so a rebound here would validate the timing explanation. Book-to-bill has hovered near one for three quarters, up from about 0.8 earlier in 2025, against a backlog of $452 million. Sustaining that ratio, or pushing above it, is the cleanest way to show that the raised second-half outlook is supported by orders rather than optimism. Follow-on orders from the North American memory customer and any traction for the new Purion H6 high-current platform would add texture, though memory is expected to remain lumpy and roughly flat with the first half.
Sentiment has cooled, with readings slipping further into bearish territory compared with the mildly negative tone ahead of the last report. The stock trades below its 200-day moving average and sits in the lower part of its post-earnings range, much closer to the low near $103 than the high near $150. Lingering uncertainty around the pending VECO merger and an interim CFO only add to the caution.
That skepticism lowers the hurdle in one sense, but the real verdict will come from the fourth-quarter outlook. If Axcelis confirms that the second half is tracking stronger than the first and that margins have stabilized, the improving narrative from last quarter stays intact. If the guide suggests the upswing is fading or margins keep eroding, the recent selloff will look like it was early rather than excessive.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Sep-21 | |
| Sep-14 | |
| Sep-09 | |
| Sep-08 | |
| Sep-04 | |
| Sep-01 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 | |
| Jul-28 |
