Artisan Partners Beats On Margin And Fee Rate, But $10.6 Billion In Outflows Keeps The Asset Base Shrinking
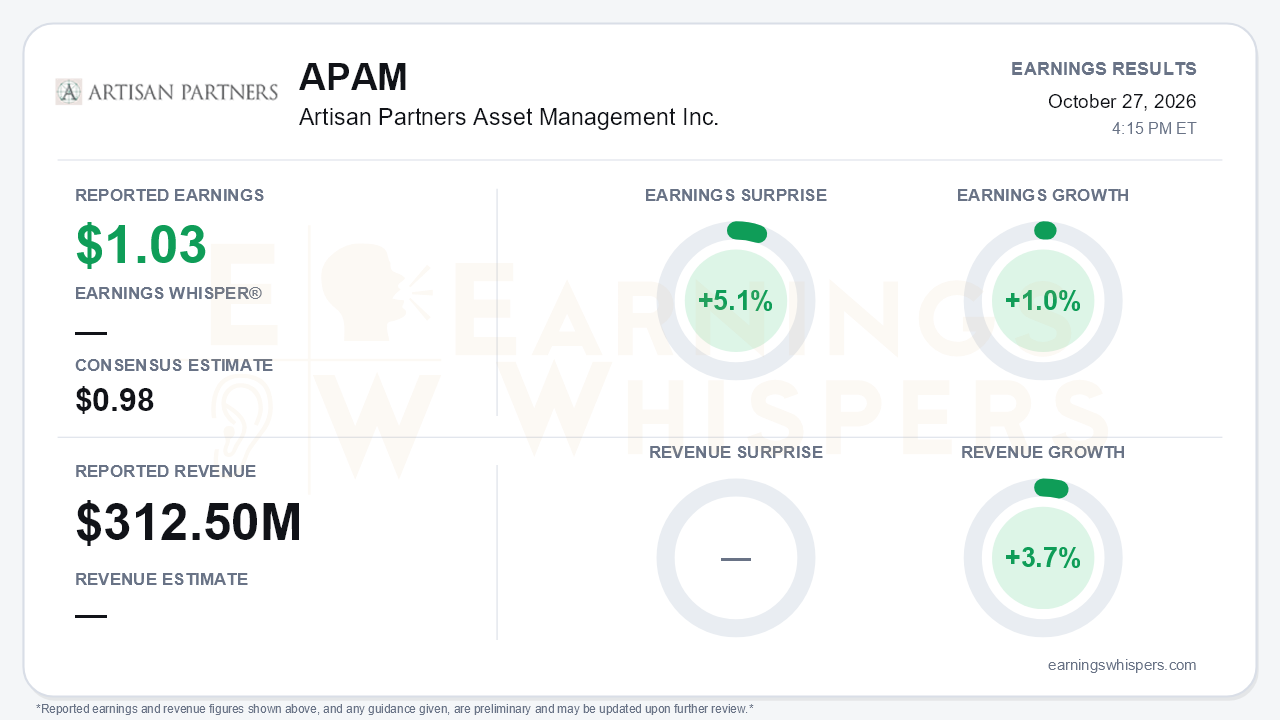
Artisan Partners (NYSE: APAM) delivered a clean headline beat for the September quarter. Adjusted earnings of $1.03 per share topped the $0.98 consensus by 5.1%, and revenue rose 3.7% year over year to $312.5 million. Beneath the beat, however, the franchise is losing assets. Net outflows reached $10.6 billion, nearly matching Q2's $10.5 billion, and ending AUM fell 8% sequentially to $169 billion from a record $183 billion. That is the central tension: Artisan is earning more on each dollar it manages while managing fewer dollars.
The quality of the beat deserves scrutiny. Margins did most of the work. The adjusted operating margin rebounded to 35.5% from 32.9% in Q2, lifting EPS from $0.94 sequentially. Revenue rose only about 1% from Q2 as average AUM slipped 1%. The year-over-year comparison shows clear deceleration. EPS grew just 1.0%, down from 13% growth in Q2. Revenue growth slowed to 3.7% from roughly 9% in each of the first two quarters. Margin was also down 70 basis points from a year ago, reflecting Grandview costs and higher employee and professional expenses. Management signaled confidence anyway, raising the quarterly dividend 10% to $0.88. Cash rose to $352 million, and the undrawn revolver was expanded to $150 million.
The outflow detail is more nuanced than the total suggests. Of the $10.6 billion, $7.8 billion was discrete:
- $1.9 billion from the US Value wind-down
- $5.9 billion from a single global value client rebalancing
That makes the quarter look less like broad-based attrition. But the $5.9 billion rebalancing prompted analyst questions about client concentration, and bears have legitimate ammunition. Short-term performance also weakened in International Value and Global Value, denting 1- and 3-year records that had been strong in Q2. As of October 26, firm AUM ahead of benchmark had recovered to 75% over one year and 84% over three years. The broader backdrop remains difficult, with ongoing institutional de-risking, active-to-passive shifts, and what management described as the narrowest market breadth since 2000.
The mix shift is the more constructive story, and it explains the rising fee rate. The fee rate climbed to 69 basis points, up from 68 in Q2 and 67 in Q1, and is guided to about 70 basis points in Q4 as low-fee mandates leave. Alternatives net inflows jumped to roughly $770 million from about $300 million in each prior quarter. Credit and alternatives combined now exceed $26 billion, or 15% of AUM. One caveat: credit inflows, while positive for a 17th straight quarter, slowed to about $290 million from roughly $700 million in Q2 and $800 million in Q1.
The call preserved a credible growth narrative built on new products and channels:
- ETF share classes of the Select Equity and Focus funds in Q4, at existing fee levels
- A public/private credit interval fund for wealth clients targeted for 2027
- The Grandview Fund 4 anchor close (Fund 3 was about $150 million)
- A higher-fee long-short strategy via the Sachem Head lift-out
- Two credit M&A opportunities and potential expansion into Europe and CLOs
Management said pipeline dollars are up meaningfully, though RFP counts were flat. Q4 performance fees are projected near last year's roughly $29 million. Offsetting that, Q4 starts from a lower AUM base and faces about $2.5 billion of non-reinvested fund distributions, versus $1.5 billion a year ago.
The market has treated the stock harshly. Shares closed at $33.20 as of the October 27 snapshot, down 20.8% from the $41.90 open after the July report and 13.6% below the 200-day moving average of $38.44. Price and AVWAP trend readings remain negative. Investor sentiment improved modestly, from -0.25 to -0.18, but stayed in negative territory. That suggests expectations are cautious and slightly less pessimistic, not that conviction has turned.
The bottom line is that Artisan beat on profitability and pricing power, not on growth. The rising fee rate, alternatives momentum, dividend increase and broadening product pipeline give the long-term mix-shift thesis real substance. But the asset base is still shrinking and year-over-year earnings growth has nearly stalled. Q4 begins with lower AUM and heavier distributions. Until flows in core value strategies stabilize, margin gains alone may struggle to offset a shrinking asset base.
Read our earnings preview for Artisan Partners Asset Management Inc.: https://www.earningswhispers.com/article/APAM/20737
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-13 | |
| Oct-09 | |
| Sep-10 | |
| Aug-17 | |
| Aug-11 | |
| Jul-28 | |
| Jul-28 | |
| Jul-14 | |
| Jul-10 | |
| Jun-05 | |
| May-11 | |
| Apr-30 |
