Garmin Crushes EPS Estimates And Raises Guidance A Third Time, But Flags A 2027 Margin Reset And Cuts Its Cash-Flow Outlook
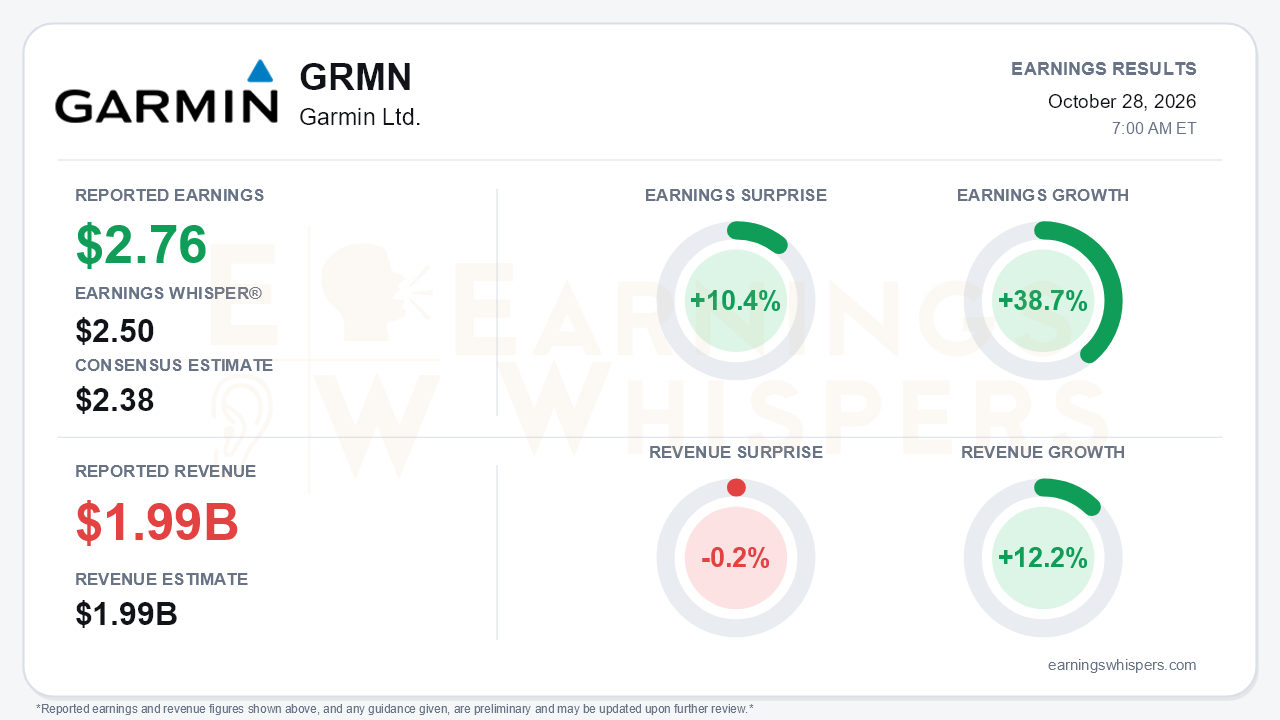
Garmin delivered a decisive earnings beat in the third quarter. Pro forma EPS of $2.76 topped the $2.38 consensus by 10.4% and cleared the $2.50 Earnings Whisper number by a comfortable margin, with earnings growing 38.7% year over year. Revenue rose 12.2% to a record $1.986 billion but came in 0.2% shy of consensus. Management raised full-year guidance for the third consecutive call, to roughly $8.15 billion in revenue and $10.80 in pro forma EPS. Yet the same call introduced the most consequential caveat of the year: management explicitly warned that higher memory costs will pull 2027 gross margin back to its historical range. That is the central tension. Garmin is printing peak margins while telling investors those margins are not the new baseline.
The quality of the beat deserves scrutiny. This was a margin story, not a revenue story. Gross margin expanded 420 basis points to 63.3%, and operating margin widened 500 basis points to 30.8%, lifting operating income 34% to $612 million. Favorable mix and lower product costs did real work, and every segment posted higher margins. However, roughly $33 million of refunds on previously paid tariffs, following $21 million in the second quarter, also flattered the gross line. The bottom line got additional help from a lower tax rate, which fell to 18.1% from 21.2% on 2025 U.S. tax legislation. That explains why EPS growth outpaced operating income growth. Strip out the nonrecurring tailwinds and the quarter is still very good, just less extraordinary than the 39% headline implies.
Beneath the consolidated numbers, the growth mix shifted. Outdoor was the standout, swinging from declines of 5% and 2% in the first two quarters to 20% growth on the fenix 9 launch, with 39% operating margins. Marine grew 16% on LiveScope 2. Fitness, the year's engine, is cooling: growth slowed to 16% from 25% in the second quarter and 42% in the first. Aviation decelerated to 5% from 8% and 18%. Auto OEM fell 20% as domain-controller revenue dropped, and management expects further decline in the fourth quarter before the Mercedes-Benz ramp in early 2027. APAC grew just 4% on China weakness, and management described the marine end market as slightly softer. Garmin is increasingly relying on new-product cycles rather than broad category tailwinds.
Those product cycles look credible. The screenless CIRQA band is running ahead of supply with a backlog. Product registrations outpaced sell-in, retailer holiday plans are strong, and Connect Plus subscriptions are beating expectations. The Thailand facility remains on track for first-quarter 2027 production and should add needed capacity. Aviation milestones, including more than 2,500 Autoland-equipped aircraft and 1,000 King Air G1000 retrofits, reinforce a durable franchise. Bears still have legitimate ammunition. Free cash flow guidance was cut to about $1.1 billion from $1.4 billion. Inventory has climbed to roughly $2.3 billion, and supplier prepayments are absorbing cash. Third-quarter free cash flow fell to $293 million from $425 million. Management also cited second-order AI-driven cost and supply pressure on circuit boards and cabling. The inventory build looks like a deliberate hedge against component inflation, which reinforces the message that costs are heading higher.
The guidance math carries its own signal. Full-year gross margin guidance of about 61% sits below the 61.8% achieved through three quarters, implying a fourth-quarter step down even before the 2027 memory headwind arrives. The implied fourth-quarter pro forma EPS of roughly $3.15 still points to a strong holiday period.
Investor sentiment improved only modestly, rising to 0.26 from 0.24. Expectations remain positive but restrained rather than euphoric. Shares entered the report at $289.34, up 10.5% since the open after the July report and about 14.5% above the 200-day moving average. Still, the stock sits 7.9% below the $314.28 52-week high set on August 10. The market has rewarded the earnings momentum without fully recovering the August peak, which reflects some hesitation about how long current margins can last. Momentum and AVWAP trend readings remain positive, while price trend is neutral.
The bottom line is that Garmin's operating execution and product pipeline justify the raised outlook, and the near-term holiday setup looks healthy. The investment debate has shifted, though. Investors are no longer asking whether Garmin can beat estimates. They are asking how much of 2026's record profitability survives a 2027 defined by memory-cost inflation, slowing fitness growth, and weaker cash conversion.
Read our earnings preview for Garmin Ltd.: https://www.earningswhispers.com/article/GRMN/20853
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 4 hours | |
| 6 hours | |
| 8 hours | |
| 11 hours | |
| 12 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 |
