Peapack-Gladstone Beats On Strong Operating Leverage, But A One-Time Tax Benefit And Tightening Capital Complicate The Quarter
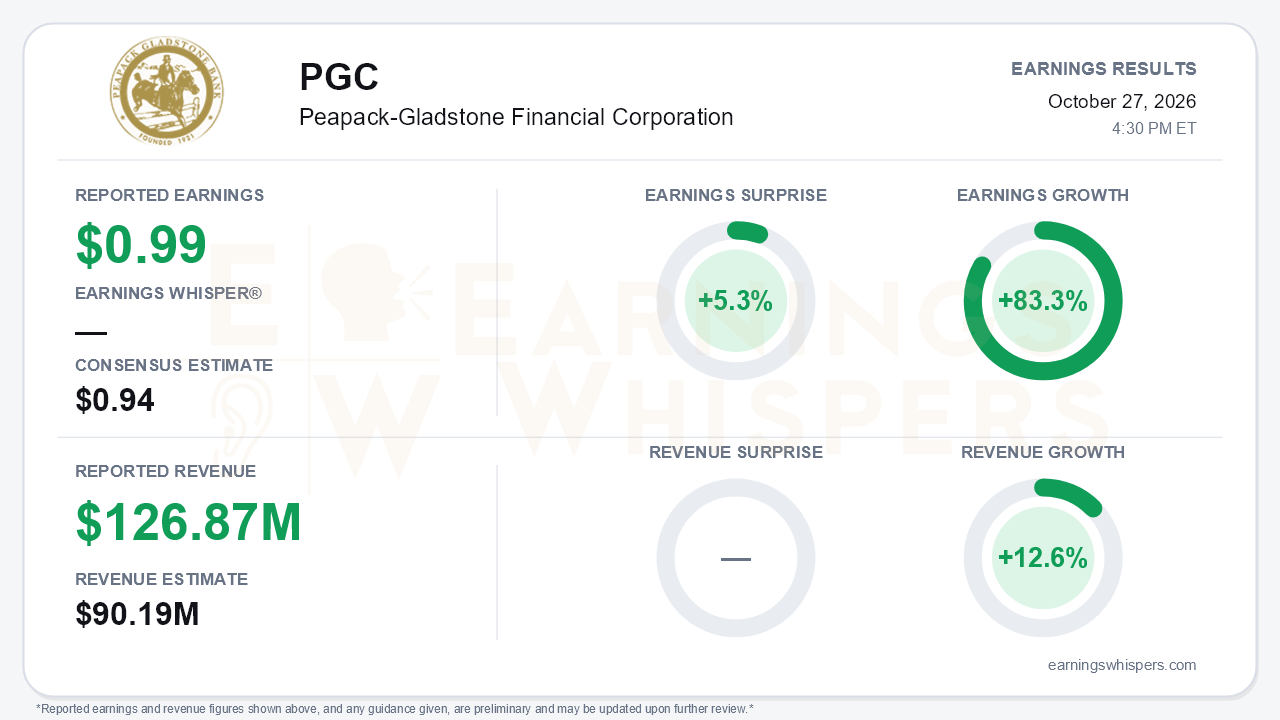
Peapack-Gladstone Financial (NASDAQ: PGC) reported third-quarter earnings of $0.99 per diluted share, beating the $0.94 consensus by 5.3% and rising 83.3% from a year ago. Operationally, this was the strongest quarter of the bank's private-banking buildout: record loan growth, another linked-quarter decline in expenses, and an improving credit picture. The quality of the beat still deserves scrutiny. The effective tax rate fell to 20.5% from 28.4% in the second quarter because of a discrete benefit of roughly $1.8 million from purchased production tax credits. By our math, that benefit was worth about nine cents per share, larger than the size of the beat. On a normalized tax rate, the quarter likely came in modestly short of consensus even as pre-tax earnings power clearly improved. That is the central tension.
The revenue comparison needs context. Earnings Whispers reports revenue of $126.87 million, 40.7% above the $90.19 million consensus and up 12.6% year over year. That figure corresponds to gross interest income plus noninterest income. The company's own total revenue measure, which nets out interest expense, was $87.5 million, up 24% and the tenth straight quarterly increase. On either basis, the driver is the same. Net interest income rose 6% sequentially and 33% year over year to $67.5 million, and net interest margin edged up to 3.34% from 3.32%, well above 2.81% a year ago. Operating expenses slipped to $55.1 million, pre-provision net revenue climbed to $32.3 million from $30.4 million, and the GAAP efficiency ratio improved for an eighth consecutive quarter to 63.03%. Return on average tangible common equity reached 11.41%, versus 6.59% a year ago.
The balance sheet story was even stronger than the income statement. Loans grew $403 million, a 24% annualized pace. That compares with $236 million in the second quarter and the roughly $300 million management had flagged. Loan closings reached $931 million, led by C&I and commercial real estate. Credit also turned in the right direction:
- Nonperforming assets fell to $57.8 million, or 0.68% of assets, from $72.2 million.
- Delinquencies, special mention and classified loans all declined.
- Net charge-offs eased to $4.7 million.
- Reserve coverage of nonperforming loans rose to 126%.
The provision of $8.5 million was mostly growth-driven, though $4.6 million went to specific reserves.
The call preserved a credible earnings-expansion narrative. Management extended its margin guidance of two to three basis points of quarterly expansion into 2027. It sized a back book of about $1.4 billion at roughly 3.90% that should reprice 150 to 200 basis points higher over two years. It also said pipeline visibility extends into early 2027. Return on assets is about 90 basis points now, with management targeting above 1% in early 2027 and a longer-term goal of 1.25% alongside a 14% return on equity. An enterprise AI rollout is intended to hold 2027 expense growth to mid-to-upper single digits. That is a step up from a roughly flat 2026, but it would still preserve operating leverage.
Bears have legitimate ammunition, however.
- **Funding:** The third-quarter pace was described as "abnormally strong," and growth should normalize toward the 200/200 objective. Funding is the pressure point. Short-term borrowings rose $206 million, noninterest-bearing deposits fell sequentially, and interest-bearing liability costs rose 10 basis points. Management acknowledged that a September Fed hike and a possible December move mean "higher for longer is not good for us."
- **Fees:** Fee income fell to $20.0 million from $22.1 million, and the run rate was guided down to about $21 million after the SBA gain-on-sale exit. Wealth revenue was flat at $17.3 million, and AUM/A slipped to $13.6 billion.
- **Capital:** Tangible common equity to tangible assets dropped to 7.60% from 8.10% in one quarter, and tangible book value per share was flat sequentially at $36.24. The company drew the remaining $20 million of convertible preferred and reinstated a discounted DRIP. Diluted shares now run about 1.3 million above basic, so growth is being partly funded with dilution.
Investors have turned noticeably cooler despite the beat. Earnings Whispers sentiment swung from a slightly positive 0.09 to -0.57, a sizable deterioration that suggests the tax-aided beat and capital actions are weighing more heavily than the loan growth. Shares, at $45.91, are up just 1.2% from the open after the July report. That stall comes even as the stock sits about 12% above its 200-day moving average, and the AVWAP trend reading remains positive. The market has given PGC credit for its longer-term improvement but little incremental reward this quarter.
The bottom line is that Peapack-Gladstone's core franchise is visibly maturing, with margins, efficiency, credit and loan growth all moving the right way and a margin runway extended into 2027. The headline beat was flattered by a non-recurring tax benefit, however, and the growth driving the story is consuming capital and leaning on costlier funding. Whether PGC can reach its 1% ROA target without further dilution or margin slippage from higher-for-longer rates is the question the next few quarters must answer.
Read our earnings preview for Peapack-Gladstone Financial Corporation: https://www.earningswhispers.com/article/PGC/20787
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-19 | |
| Oct-15 | |
| Oct-13 | |
| Oct-05 | |
| Sep-22 | |
| Sep-09 | |
| Sep-01 | |
| Aug-26 | |
| Jul-30 | |
| Jul-28 | |
| Jul-27 |
