Aemetis Must Prove Its EBITDA Turn Can Outrun A Thin Cash Cushion
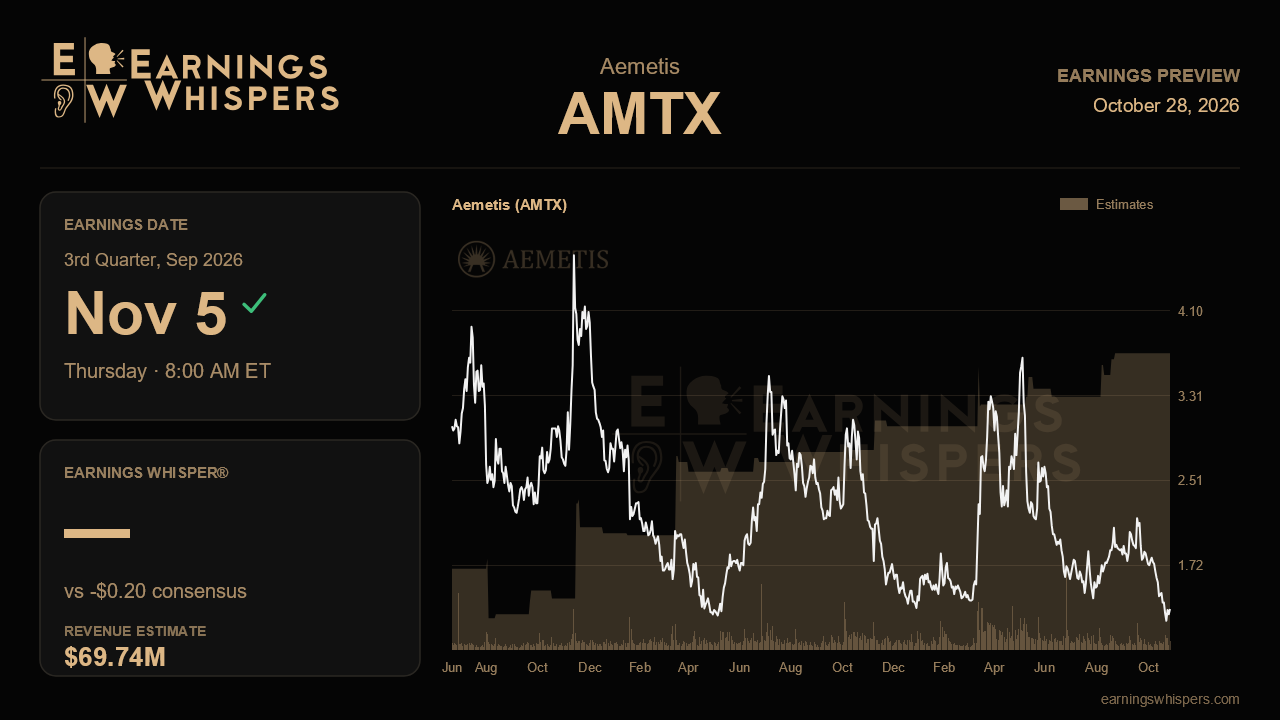
Last quarter Aemetis finally delivered the result bulls had been promising for years: positive adjusted EBITDA and positive operating income. The market's response since then has been anything but celebratory. The shares have fallen about 21% while the S&P 500 was flat, and that gap frames the third-quarter report due before the open on November 5. The question is no longer whether the core business can make money in a good quarter. It is whether the improvement can repeat and produce cash fast enough to matter for a balance sheet that ended June with roughly $1 million in the bank.
The Street's numbers point to a mixed setup. Consensus calls for revenue of about $69.7 million, up roughly 18% from a year ago and a solid step up from the $62.7 million reported last quarter. Yet the expected loss of $0.20 per share is wider than the $0.13 loss posted in the second quarter, even though it would still be a large improvement from the $0.37 loss a year earlier. Analysts, in other words, are modeling more sales but less profit than last quarter. That suggests they doubt the second quarter's margin strength, which leaned partly on $8.6 million of 45Z production credits, will fully carry over. Management offers no formal guidance, so the bar is set entirely by the Street, and it is not a demanding one on earnings.
The revenue step-up should get help from India. Biodiesel sales there dropped to just $2.5 million in the second quarter as state oil marketing companies worked through their tender process. Management then announced an allocation of more than 18 million liters, worth roughly $17 million, in early August. If that volume shipped during the quarter, India alone could account for much of the sequential revenue gain. A clean rebound would support management's claim that the start-stop ordering pattern is easing, and any early sales to private commercial customers would back up its talk of a new channel. Another quarter of thin India revenue would undercut both points and push the delayed India IPO further out.
In California, the evidence to watch is whether the gains in volume and spread hold up. Last quarter RNG volume rose 38%, ethanol volume rose 12%, ethanol prices rose 9%, and corn costs fell to $6.07 a bushel. Management also said two dairy digesters were weeks from completion and that a third corn oil unit would come online this fall, roughly doubling corn oil output. Signs of progress on the six LCFS pathways awaiting CARB approval, and on the MDR/MVR project slated for service at the end of 2026, would make the out-year cash flow story more credible. Gross profit that holds near last quarter's $13.8 million, rather than falling back toward first-quarter levels, would be the clearest sign that the turn is structural.
The bigger issues sit on the balance sheet and in Washington. The DOE correction to 45Z emissions rates, which could lift RNG credit value sharply and unlock catch-up cash for ethanol, remains pending, and management expressed only moderate confidence on its size and timing. The Third Eye debt refinancing is also unresolved. The July sale of 45Z credits brought in $17.6 million of net cash, so the quarter-end cash balance and any refinancing update may matter more than the earnings line.
Sentiment has turned more bearish than it was before the last report, and the stock sits at $1.31, well below its 200-day average near $1.97 and close to its post-earnings low of $1.18. That leaves room for relief if liquidity looks stable, but little cushion if it does not. The report's real test is simple. Aemetis needs to show that its operating improvement is turning into cash and financing progress, not just better adjusted EBITDA.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Sep-28 | |
| Sep-28 | |
| Sep-02 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 | |
| Jul-23 | |
| Jul-09 | |
| Jun-17 | |
| May-21 |
