Nabors Misses On GAAP EPS As Minority Interest And Taxes Absorb A Strong Operating Quarter; Free Cash Flow Outlook Nearly Quadruples
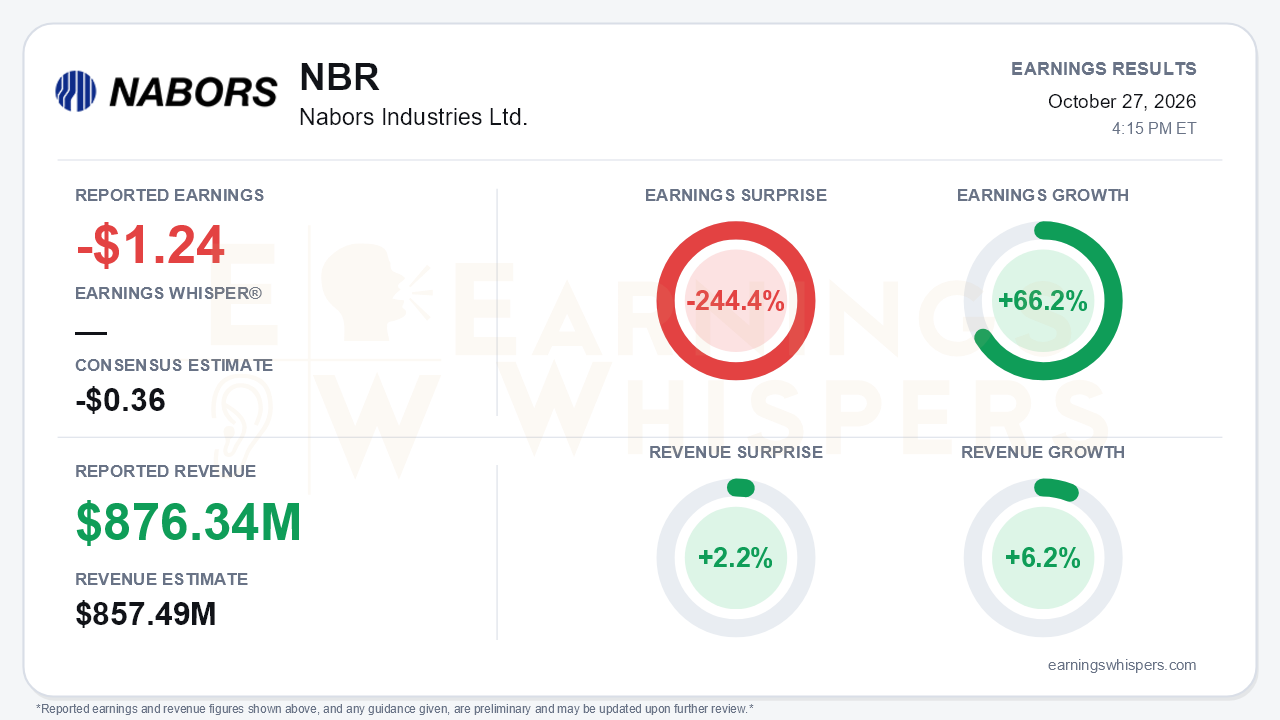
Nabors Industries delivered one of its cleaner operating quarters in some time, but very little of that reached common shareholders. The driller reported a third-quarter loss of $1.24 per share, far worse than the consensus estimate for a $0.36 loss, a 244.4% miss. Revenue of $876.34 million beat the $857.49 million consensus by 2.2% and grew 6.2% year over year. Earnings Whispers' normalized figures show earnings growth of 66.2% year over year. The reported GAAP comparison is distorted because the year-ago quarter included a $416 million gain on the sale of Quail Tools. Sequentially, the loss narrowed from $2.04 per share in the second quarter. That is the central tension. Adjusted EBITDA, margins, rig counts and cash flow all moved decisively higher, while the per-share bottom line remained deep in the red.
The EPS miss was not caused by weaker operations. Adjusted operating income jumped 40% sequentially to $85.8 million, and pre-tax income more than doubled to $36.4 million. The damage came below that line. Income tax expense was $20.4 million, more than half of pre-tax income. Another $27.1 million went to noncontrolling interests, largely tied to the SANAD joint venture in Saudi Arabia. A further $6.8 million accrued to the redeemable noncontrolling interest. Together, those items turned a $16 million net profit into an $18 million loss for common shareholders. Investors who value Nabors on EBITDA will see this as structural noise. Those focused on per-share earnings have a legitimate complaint: the capital structure keeps capturing value before it reaches the common stock.
At the operating level, the quarter was strong almost everywhere. Adjusted EBITDA rose nearly 11% sequentially to $246 million, and consolidated EBITDA margin widened about 100 basis points to 28.2%.
- **International:** Daily adjusted gross margin reached a record $19,060, up from $17,534 in the second quarter and well above the original full-year target of $18,500. Management guided to about $19,500 in the fourth quarter.
- **Lower 48 margin:** Daily margin topped $14,000. On the second-quarter call, management had expected the third quarter to be flat at $13,800. Fourth-quarter guidance is $14,500 to $14,700.
- **Lower 48 rig count:** The fleet averaged 72.8 rigs, compared with a full-year guide of 61 to 64 set early in the year. Leading-edge day rates have climbed into the mid-$30,000s, and contract coverage is heading toward about 55%.
- **Drilling Solutions:** EBITDA rose 10% to $44 million.
The cash story is the biggest change in the setup. Adjusted free cash flow was $75 million, compared with $12 million in the second quarter. Full-year guidance rose to $100 million to $110 million from $20 million to $30 million. Full-year EBITDA guidance of about $930 million sits at the top of the prior range, despite Saudi rig suspensions. Nabors redeemed $100 million of its 9.125% notes, and management expects 2027 cash interest to be at least $50 million below 2025 levels. Investors should note the source of the cash beat, however. The CFO attributed part of it to SANAD newbuild milestones shifting into later periods, and 2027 capital spending is expected to rise. Some of this year's free cash flow is timing rather than permanent savings.
Saudi Arabia is the clearest risk. SANAD received suspension notices on five rigs, part of 15 industry-wide, which management linked to regional hostilities and to drilling running ahead of completions. SANAD's rig count will fall from 56 to 52 by year-end, and the timing of a return is unknown. The 19th newbuild slipped to the first quarter of 2027. Fourth-quarter international guidance of 92 to 93 rigs is well short of the original plan of 96 to 98 rigs, with an exit at or above 101. Against that, the catalyst list lengthened:
- a fifth SANAD newbuild tranche, signed during the call, which takes the program to 25 rigs;
- a multiyear contract to return to Venezuela, with more than 20 additional rig opportunities being tracked there;
- an international pipeline that doubled to more than 80 rigs across 11 countries;
- a reiterated path to an annualized EBITDA run rate of roughly $1 billion entering 2027.
The market has not yet rewarded the operating progress. Shares at $81.32 are essentially unchanged, down 0.2%, from the $81.48 open after the July report. They sit 3.3% below the 200-day moving average of $84.08, and the Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment stayed positive but weakened meaningfully, falling from 0.33 to 0.12. Enthusiasm cooled even as guidance moved higher, likely reflecting the Saudi overhang and persistent GAAP losses.
The bottom line is that Nabors' quarter was far better than its headline EPS miss suggests. Margins hit records, Lower 48 activity beat expectations, and free cash flow guidance roughly quadrupled. The bear case rests on the gap between EBITDA and per-share earnings, on some of the cash beat being timing, and on unresolved Saudi suspensions. The bull case depends on the $1 billion run rate and deleveraging translating into equity value that minority interests and taxes do not absorb first.
Read our earnings preview for Nabors Industries Ltd.: https://www.earningswhispers.com/article/NBR/20777
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Sep-11 | |
| Aug-28 | |
| Aug-27 | |
| Aug-20 | |
| Jul-28 | |
| Jul-28 | |
| Jul-01 | |
| Jun-02 | |
| Apr-30 | |
| Apr-28 | |
| Apr-28 | |
| Mar-24 |
