Highwoods Beats And Lifts FFO Midpoint Again, But Cash NOI And Free Cash Flow Lag The GAAP Leasing Story
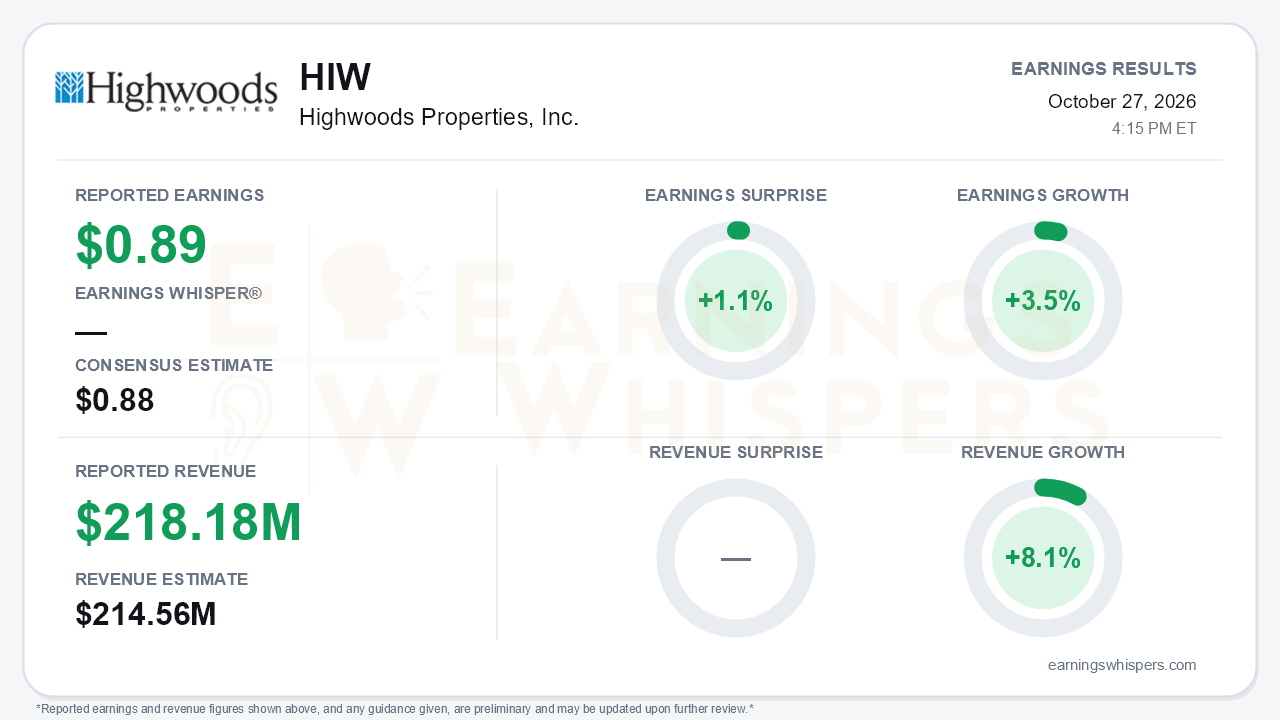
Highwoods Properties delivered a modest beat in the third quarter. It earned $0.89 per share against a $0.88 consensus, a 1.1% surprise. Revenue of $218.18 million topped the $214.56 million estimate by 1.7%. Revenue grew 8.1% year over year, more than twice the 3.5% earnings growth, which shows that top-line gains are not yet fully reaching the bottom line. The headline guidance description, a narrowing of the range, undersells what happened. The 2026 FFO outlook moved to $3.51-3.70 from $3.46-3.70. The range tightened only because the low end rose while the top stayed fixed. This is the third straight increase. The midpoint is now 6.5 cents above the initial $3.40-3.68 range, despite roughly 4 cents of extra dilution from asset sales. The central tension is that the GAAP and leasing metrics are accelerating sharply, while cash results are not keeping pace.
The leasing evidence is strong.
- Occupancy rose 130 basis points sequentially, nearly double the 70 basis point gain in the second quarter.
- The lease rate reached 90.1%, up from about 89% at year-end 2025.
- About 800,000 square feet of signed-not-commenced leases are in the backlog.
- GAAP rent spreads jumped to 29%, up from 20.9% in Q2, 19.4% in Q1 and the mid-teens in Q4. That is a clear acceleration, not a one-off.
- Management put the portfolio's cash mark-to-market at about +7%, compared with roughly flat a year ago, and said market rents are up about 10% year over year.
- The 23 Springs development is now 95% leased, up from about 75% at year-end.
The quality of the improvement deserves scrutiny. Same-property cash NOI rose only 0.2%, compared with 4.1% on a GAAP basis. Straight-line rent climbed to $14 million from $5.5 million a year ago, reflecting heavy free-rent packages. Cash rent spreads were 4%, up from 3.2% in Q2 but below 4.8% in Q1. Leasing capital spending has already exceeded $140 million this year. Management said free cash flow will not normalize until 2028 and described 2027 as only 'okay'. Bears therefore have legitimate ammunition. The leasing recovery is real, but it is expensive. Dividend coverage on a cash basis remains a multi-year project rather than a near-term payoff.
The call's tone moved further from defensive. In Q1, management was addressing AI-related worries about office demand. This quarter it described tenants scrambling for space and renewing three to five years before expiration. Retention on the next five quarters of expirations is tracking near 50%, above historical norms. Two forward signals cool the momentum, however:
- Management lowered the expected pace of new leasing to about 250,000 square feet per quarter, from a 300,000 target.
- It framed 2027 occupancy gains at roughly 100 basis points, compared with about 250 basis points this year.
The year-end occupancy range was narrowed to 87.0-88.0% with an unchanged midpoint.
The capital-allocation story is the more distinctive catalyst.
- Dispositions reached $386 million year to date at a sub-8% cap rate. That is nearly double the original target of about $200 million, and another $100-250 million is under contract for Q4.
- Joint-venture financings at 23 Springs and Midtown East returned roughly $99 million.
- Debt to EBITDA fell to 6.1x from 6.7x at the start of the year.
- Cash rose to about $280 million, and $33.5 million of unsettled forward equity is held as dry powder.
- Management now expects $100-400 million of development announcements, saying Dallas net rents of about $85-100 justify new construction.
The offsets are real. Asset sales dilute near-term results, and new development NOI will take two to four years to arrive. Higher interest rates are slowing transactions and raising return hurdles. No acquisitions have closed this year, and the low end of acquisition guidance was cut to zero after the Block 83 purchase shifted in timing.
The market has not rewarded the improving operating picture. Shares have fallen 14.8% since the open after the July report, from $34.99 to $29.82. They remain about 8.7% above the 200-day moving average of $27.44, so the longer-term trend has not broken down, but the stock has given back substantial ground. AVWAP trends remain negative. Investor sentiment fell from a mildly positive 0.13 to -0.37, a meaningful shift into negative territory heading into the report. Expectations were therefore subdued, which raises the bar for how investors interpret the cash-flow commentary.
The bottom line is that Highwoods delivered another guidance increase, accelerating GAAP spreads and occupancy, and a visibly stronger balance sheet. Those are the ingredients of a credible office recovery. However, the gap between 4.1% GAAP NOI growth and 0.2% cash NOI growth, the delay in normalized free cash flow until 2028, and slower expected leasing gains in 2027 explain why a skeptical market has sold the shares down. The fundamental story is improving faster than the cash flows that ultimately support the dividend.
Read our earnings preview for Highwoods Properties, Inc.: https://www.earningswhispers.com/article/HIW/20763
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 7 hours | |
| Oct-27 | |
| Oct-22 | |
| Sep-15 | |
| Sep-14 | |
| Aug-17 | |
| Jul-28 | |
| Jul-28 | |
| Jul-22 | |
| Jun-16 | |
| Jun-04 | |
| May-12 | |
| May-11 | |
| Apr-30 |
