Aspen Aerogels Must Prove Its First Positive EBITDA Guide Was More Than A Promise
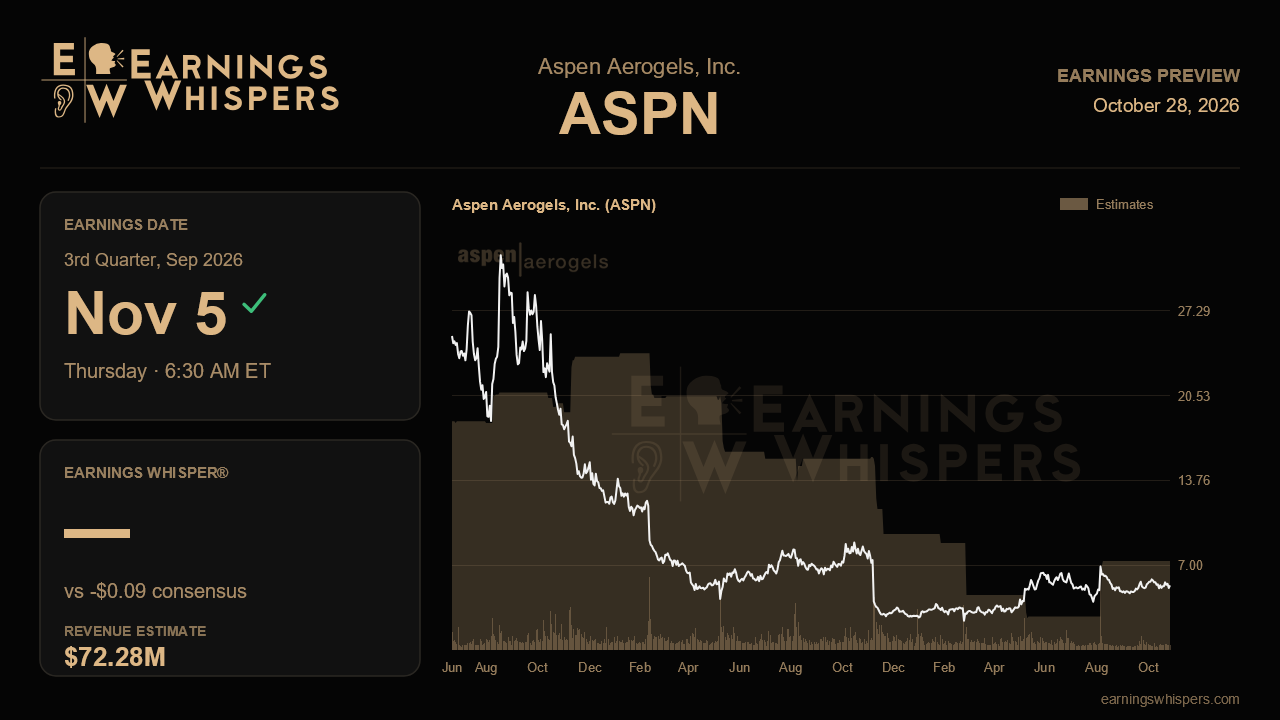
Aspen Aerogels heads into its third-quarter report with something it has not had in a long while: a guidance range that points to positive adjusted EBITDA. After a string of quarters in which management guided to losses at that level, the company told investors last quarter to expect $7 million to $15 million of adjusted EBITDA on revenue of $65 million to $80 million. That is a 30% to 60% sequential jump from the second quarter's $49.8 million, and the market has spent the intervening months treating the forecast with open skepticism. This report is where the turnaround narrative either earns credibility or loses it.
Wall Street has essentially adopted management's outlook wholesale. Consensus calls for a loss of $0.09 per share on revenue of $72.3 million, which sits almost exactly at the midpoint of the company's guidance for a loss of $0.07 to $0.11 per share. Analysts have moved a long way to get there; before the guide, they were looking for a loss of $0.16 on about $55 million in sales. Viewed against last year, the bar is modest: revenue would be roughly flat with the $73.0 million reported a year ago, while the per-share loss would be wider than the prior year's $0.06. The real comparison is sequential, since a midpoint result would cut the loss by more than half from the second quarter's $0.22.
The heavy lifting is supposed to come from energy industrial, which management expected to reach about $40 million, roughly double the second quarter's $20.4 million, on subsea and LNG project deliveries. That segment slipped 6% sequentially last quarter as Middle East conflict disrupted logistics and pushed demand into the third quarter, so a full recovery would confirm that the shortfall was timing rather than erosion. The other big swing factor is General Motors. Management assumed annualized GM production of 90,000 to 125,000 units, up from about 100,000 in the second quarter, and acknowledged that this assumption explains most of the width in the revenue range. With U.S. EV demand settling at only about 6% of sales, results near the bottom of the range would suggest that GM, not the industrial business, remains the company's Achilles heel.
Europe is the more encouraging thread. Management lifted its 2026 European thermal barrier outlook to $20 million to $30 million after generating about $11 million in the first half, already more than all of 2025, and set a 2027 target of $40 million to $60 million supported by a new Jaguar Land Rover award. Third-quarter European revenue that continues stepping up from $5.8 million would make the full-year range look conservative, while any flattening would raise questions about the 2027 doubling. Early commercial traction in battery energy storage would add a welcome third leg.
The East Providence plant explosion remains the asterisk. Management flagged $5 million to $10 million of incident costs this quarter, with insurance recoveries lagging by about a quarter and full capacity not expected until the first half of 2027. Cash use for working capital as European programs ramp also bears watching against the goal of holding roughly $63 million in net cash by year-end, particularly with the Plant 2 sale now pushed into 2027 after repeated delays.
Sentiment has swung from decidedly bearish before the last report to moderately bullish now, yet the shares have fallen about 26% since that release while the S&P 500 was flat. At $5.39, the stock sits above its 200-day average but much closer to its post-earnings low of $4.71 than its $8.10 high. That gap says investors doubt the guide more than they doubt the company. Delivering positive adjusted EBITDA inside the promised range, driven by a genuine energy industrial rebound rather than a lucky GM quarter, is the single result that would keep the inflection story intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Sep-18 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jun-03 | |
| May-14 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-23 |
