Seven Hills Realty Trust: Record Originations And Office Cleanup Collide With Delayed Dividend Coverage, First Losses And Thinner Spreads
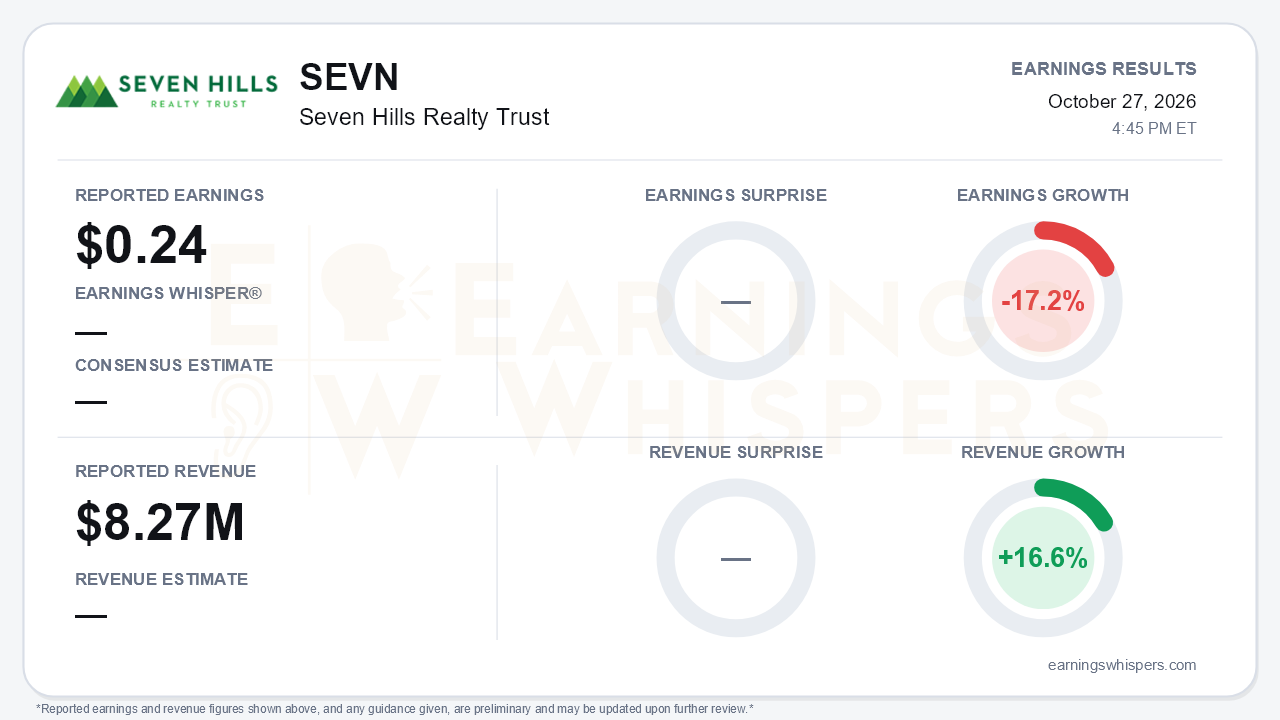
Seven Hills Realty Trust (NASDAQ: SEVN) reported third-quarter earnings of $0.24 per share on revenue of $8.27 million. Earnings fell 17.2% from a year earlier even as revenue grew 16.6%. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its trajectory rather than a beat or miss. That trajectory is split. Management delivered its best deployment quarter in nearly five years and made real progress shrinking its office book. It also pushed back the date when earnings should cover the dividend, booked the company's first realized losses, and cut the spread it expects on new loans. The central tension is that SEVN is growing the portfolio faster just as each new dollar is earning less.
The quality of the $0.24 figure deserves scrutiny. According to the call, the $0.24 is distributable earnings excluding realized losses. That landed at the midpoint of the 23-25 cent guidance range and above the 23 cents earned in Q2. Including the $1.5 million realized loss on the Dallas office loan, distributable earnings were 17 cents. The press release itself offered no financial detail beyond a pointer to the company's website, so the call carried the full burden of explaining the quarter. The year-over-year gap between revenue and earnings is consistent with what management described: a larger, more fully funded loan book generating more interest income, but at compressed spreads and with credit costs now showing up as realized losses rather than reserves.
Operationally, deployment was the standout. Originations reached $122.3 million, up from $75 million in Q2 and $67.5 million in Q1, and nearly all of it was funded at close. The office cleanup is equally tangible. The Dallas loan was resolved at roughly 97% of its $44.2 million balance, a $1.5 million loss against a $6.3 million CECL reserve. After quarter-end, the Carlsbad office loan was resolved at about 90% recovery, with a $2.6 million loss that was fully reserved. Office exposure has fallen from 24% at year-end 2025 to 13%, or 10% pro forma, and the CECL reserve dropped to 130 basis points from 190. Management guided Q4 distributable earnings to 25-27 cents excluding losses, with more than $120 million in diligence expected to close in the quarter.
The weakening threads are just as specific, and bears have legitimate ammunition:
- **Dividend coverage:** management pushed the timing from year-end 2026 to the first half of 2027, citing later loan closings.
- **Portfolio target:** the year-end goal has been cut on every call, from roughly $1 billion to about $900 million.
- **Spreads:** new deals are pricing at 145-165 basis points, and steady-state net spread is now guided to 160-180 basis points, versus 195 in Q1 and 186 at Q2.
- **Risk ratings:** the weighted average rating rose to 3.2 from 2.9. Carlsbad was downgraded to 5, and a Downers Grove office loan and a Fontana industrial loan moved to 4 ahead of near-term maturities.
- **Unresolved exposure:** a $23.5 million suburban Chicago office maturity is still outstanding.
Management also flagged rising long-term Treasury yields as slowing property sales and prompting other lenders to reprice or step back. That backdrop could help SEVN's origination volume while further squeezing borrowers.
The forward catalysts are largely about capacity. Management said each $100 million of net portfolio growth adds about 4 cents per quarter, and roughly $220 million closes the gap to the dividend. The Citibank facility has been extended to September 2028, leaving no facility maturities until 2028. A Yardley REO monetization targeted for early-to-mid 2027 could free about $40 million more. The 2027 portfolio target is $1.0-1.1 billion, with leverage rising from 1.4x to above 2x. That plan is credible, but it is a leverage-driven path to coverage executed at narrower spreads. Investors also expect a further roughly 11-cent realized loss in Q4.
The market has been unforgiving. Shares sat at $6.25 heading into the report, down 22.0% since the open following the July release and 22.6% below the 200-day moving average of $8.07. Management noted the stock trades at about 44% of book, with no buyback planned and book value per share declining. Earnings Whispers investor sentiment remained negative and weakened, moving from -0.31 to -0.41. Price and AVWAP trend readings are likewise negative, reflecting persistent selling pressure rather than any pre-report optimism.
The bottom line is that SEVN executed well on the parts of the business it controls. Originations are accelerating, office exposure is shrinking, and losses are coming in at or below reserves. But the goalposts on dividend coverage and portfolio size keep moving, and the economics of new lending are thinning. Q4 closings and the first-half 2027 coverage target are now the tests that matter.
Read our earnings preview for Seven Hills Realty Trust: https://www.earningswhispers.com/article/SEVN/20796
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-08 | |
| Oct-05 | |
| Sep-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-09 | |
| Jun-30 | |
| Jun-10 | |
| Jun-09 | |
| Jun-01 | |
| May-21 |
