RenaissanceRe Beats On Operating EPS, But The Story Is Shifting From Underwriting To Investment Income
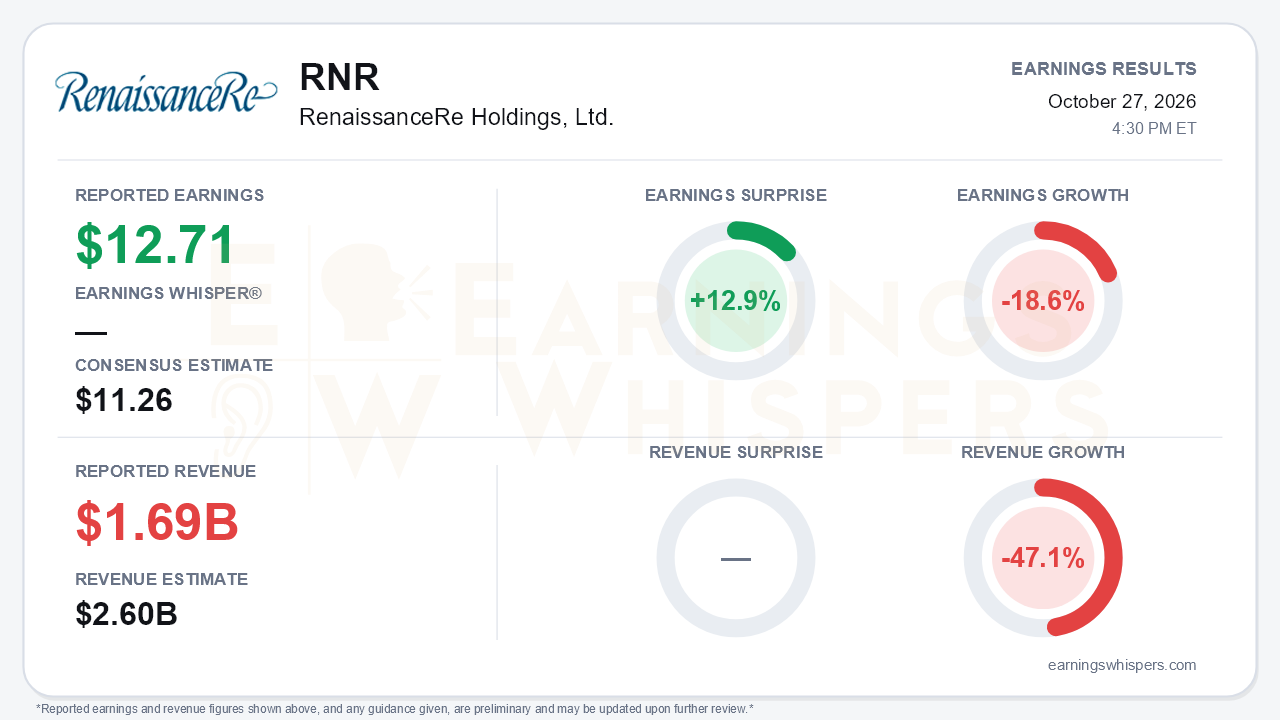
RenaissanceRe delivered operating earnings of $12.71 per share for the third quarter, topping the $11.26 consensus by 12.9% despite absorbing three large loss events. Operating earnings still fell 18.6% from a year ago, and on a GAAP basis the company posted a net loss of $4.02 per share, compared with net income of $19.40 a year earlier. Revenue of $1.691 billion missed the $2.60 billion consensus by 34.9% and fell 47.1% year over year. The central takeaway is that the beat was real, but the earnings engine is changing. Underwriting momentum is fading while higher yields and buybacks do more of the work.
The gap between GAAP and operating results comes almost entirely from the bond portfolio. Mark-to-market losses totaled $879.8 million, including $899.6 million on fixed maturity-related investments as market yields rose. Because those losses run through total revenues, they explain most of the headline revenue shortfall. They also pushed the annualized GAAP return on equity to (6.0)% and cut book value per share 1.9% sequentially to $259.61. Management said about $763 million of the losses was retained, leaving roughly $16 per share in unrealized fixed maturity losses. That figure could reverse if rates ease.
The underwriting picture is softer than the 79.7% combined ratio suggests. The Middle East War, the Ras Laffan LNG explosion and the Colombian earthquake added 9.3 points to the consolidated ratio and cost common shareholders about $111.5 million. Property still produced a 32.4% combined ratio, but that result leaned on $265 million of favorable prior-year development. Casualty and Specialty ran at 110.6%, or 109.5% adjusted, well above management's high-90s guidance. Other measures also weakened:
- Underwriting income dropped to $426 million from roughly $600 million in each of the prior two quarters.
- Operating income has slipped every quarter this year, from $591 million to $548 million to $513 million.
- Fee income declined to $81.7 million from $101.8 million as performance fees absorbed the DaVinci losses.
The call made the cyclical turn more explicit. Management's casualty tone grew more cautious. U.S. general liability rates of roughly 8-10% are no longer keeping pace with loss trend of 10-12%, a clear change from the 'rate keeping up with trend' framing earlier in the year. The response is shrinkage. Casualty retention fell to about two-thirds from roughly 75%, net premiums written dropped 19%, and fourth-quarter Casualty and Specialty earned premium guidance was trimmed to about $1.2 billion. That number was roughly $1.4 billion when the year began. Property catastrophe rates are expected to decline again at the January 1, 2027 renewals, and catastrophe bond competition could weigh on top layers. U.S. catastrophe demand growth is also slowing to single-digit billions, down from management's estimate of roughly $15 billion earlier in the year. Bears have legitimate ammunition here.
The offset is a meaningful investment-income tailwind. The release shows the portfolio yield to maturity at 5.8% with a 3.5-year duration, up from 4.8% and 2.6 years at year-end. On the call, management cited 6.0% and 4.2 years for the retained portfolio. Investors should read those as different bases rather than conflicting figures. Retained net investment income rose to $315 million, and management guided to about $325 million for the fourth quarter. That would put full-year retained income above $1.25 billion, with further growth expected into 2027. Specialty lines hit by this year's losses, including marine, energy, political violence and aviation, are expected to see rate increases at January 1. Capital return is also accelerating. The company bought back $310.1 million of stock in the third quarter at an average of $323.46 per share and another $143.8 million through October 23, and it expects that faster pace to continue through year-end.
Investors have been treating the stock better than the underwriting cycle might imply. Earnings Whispers sentiment improved from -0.17 before the prior report to roughly neutral at 0.00. That is a notable shift, though not an outright embrace. Shares stood at $341.22, up 5.4% since the open following the July report and about 10.4% above the 200-day moving average of $308.97. Price and AVWAP trend readings are positive, consistent with a market that has been rewarding capital return and yield leverage rather than penalizing the softening pricing environment.
The bottom line is that RenaissanceRe beat operating expectations with a quarter whose quality is mixed. Reserve releases and investment income held up the numbers while current-year underwriting, fees and premium volume all weakened. Management preserved a credible earnings story built on higher yields and aggressive buybacks. However, the outlook now depends more on rates and capital management than on underwriting margins, and both casualty adequacy and catastrophe pricing are moving the wrong way heading into 2027.
Read our earnings preview for RenaissanceRe Holdings, Ltd.: https://www.earningswhispers.com/article/RNR/20790
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 9 hours | |
| Oct-27 | |
| Oct-05 | |
| Jul-29 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-02 | |
| May-14 | |
| May-06 | |
| Apr-30 | |
| Apr-28 | |
| Apr-28 | |
| Apr-01 |
