BCE Faces Back-Half Proof Test As Churn Gains Meet Heavy AI And Fiber Spending
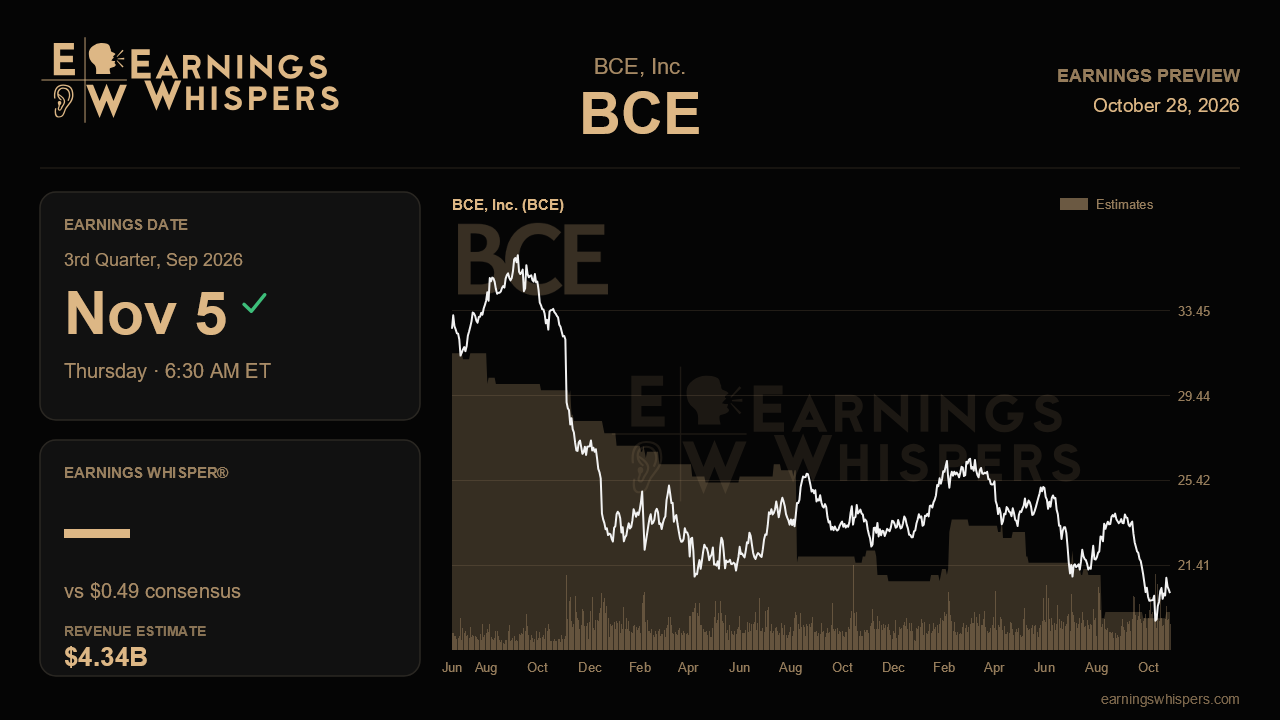
BCE heads into its third-quarter report with an odd disconnect. Last quarter management sounded more confident than it has in some time, pointing to the lowest wireless churn in three years, a sharp rebound at Bell Media and a cleaner balance sheet. The stock has gone the other way, falling about 9% since that report while the S&P 500 was essentially flat. The November 5 release, due before the open, needs to show whether the operating improvement is durable enough to outweigh a spending-heavy second half.
The Street is not asking for much on the headline numbers. Consensus calls for earnings of $0.49 per share, down roughly 14% from $0.57 a year ago, on revenue of $4.34 billion, a 1.2% decline. That would be a modest step up from last quarter's $0.47 but a contraction year over year. Management reaffirmed its 2026 outlook of $1.78 to $1.90 in earnings per share and $17.687 billion to $18.387 billion in revenue. The full-year consensus of $1.85 sits just above the midpoint of the earnings range, while the $17.92 billion revenue estimate falls in the lower half of the sales range. In other words, analysts expect BCE to protect profits through cost discipline more than through top-line growth. That fits the 40 basis point margin gain to 46.1% in Canadian telecom last quarter, when operating costs fell 4.7%.
Wireless is the first test. Postpaid churn improved from 1.49% to 1.34% to 1.02% over three quarters, and holding near that level would confirm that the gain reflects real customer loyalty rather than one quiet quarter. The weak spots are pricing and growth. ARPU was still slightly negative last quarter, management would not say when it turns positive, and an analyst flagged activation fee rolloff as a possible third-quarter headwind. Postpaid net adds also slipped year over year in a less promotional market. Low churn paired with shrinking ARPU would suggest BCE is trading price for stability. Stable or improving ARPU would make the call's upbeat tone look justified.
Media and Ziply carry the second-half story. Bell Media revenue jumped 8.9% on World Cup viewership, and Crave reached 5.1 million subscribers. The question now is how much of that holds as the tournament effect fades. At Ziply, the U.S. fiber business, management accepted a lower margin, which fell to 40.6% from 43.6%, in exchange for record residential additions of 99,600. Revenue stayed flat as a wholesale contract re-rate absorbed those gains. This quarter should start showing subscriber growth turning into revenue. A fourfold rise in permit submissions from April to June set up a build ramp that should begin appearing in the numbers now.
The cash picture may be the biggest swing factor for a stock this sensitive to its balance sheet. About $1.3 billion of 2026 Saskatchewan AI Fabric capital spending shifted into the third and fourth quarters, so free cash flow will look heavier even with no change to construction. Offsets include further tenant prepayments beyond the roughly $100 million already received toward about $400 million in setup fees, the last $400 million or so of the $7 billion divestiture target, and progress toward Winnipeg's data center launch. Leverage holding near 3.7x despite the spending would ease a key concern.
Sentiment has edged from mildly bearish to mildly bullish, but the chart shows little enthusiasm. At $20.09, shares sit well below the 200-day average of $23.50 and near the bottom of a post-earnings range of $18.68 to $23.94. That entire range is lower than the prior quarter's. The bar is therefore low but not trivial. BCE needs to show that churn gains are holding without further ARPU erosion and that rising capital spending is producing contracted revenue rather than simply adding to debt.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Oct-14 | |
| Sep-29 | |
| Sep-15 | |
| Sep-03 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-31 | |
| Jul-22 | |
| Jul-07 | |
| Jul-06 |
