Carlyle's Fundraising Super Cycle Faces A Seasonal Test After 26% Stock Slide
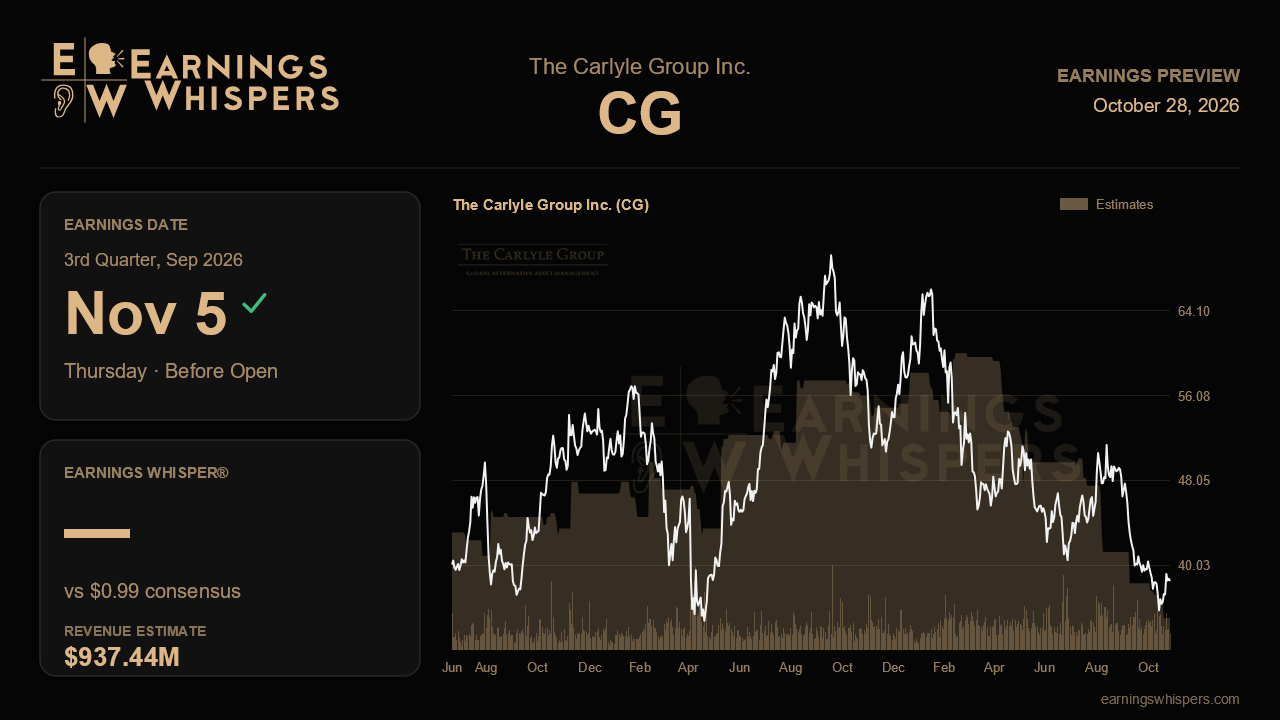
Carlyle enters its third-quarter report with an unusual disconnect. Its last quarter was the strongest in years by nearly every operating measure, yet the stock has fallen about 26% since then while the S&P 500 barely moved. The market is effectively betting that the June quarter was a high-water mark. Management, which warned that the third quarter tends to be lighter on transactions, will now have to show that a seasonal dip is just that and not the start of a fading cycle.
The Street has already priced in some cooling. Consensus calls for distributable earnings of $0.99 per share, down from $1.07 last quarter and only about 1% above the $0.98 earned a year ago. That is essentially flat performance year over year. Revenue is expected near $937 million, roughly 182% above the year-ago figure, but reported revenue at an alternative asset manager swings heavily with performance allocations, so that headline growth says less about underlying momentum than fee-related earnings do. Carlyle does not give quarterly guidance, and its only explicit targets are multi-year: $200 billion of inflows, $1.9 billion of fee-related earnings and more than $6 of distributable earnings per share by 2028, all of which were reaffirmed last quarter.
The most important line to watch is fee-related earnings, which hit a record $358 million last quarter. Much of that jump came from a record $111 million in transaction and capital markets fees, roughly double the prior quarter, plus a record $89 million in fee-related performance revenue tied to wealth and AlpInvest. Management explicitly cautioned against annualizing the capital markets haul, so a step down there would be expected. The real test is what is left underneath. If fee-related earnings hold well above the roughly $300 million run rate of earlier quarters even as transaction fees normalize, that would validate the claim that recurring management fees from a broad fundraising push are lifting the earnings base. A slide back toward $300 million would suggest the record was mostly a one-off.
Fundraising is the second pillar. Carlyle posted record first-half organic inflows of $30 billion and said essentially all of its flagship funds will be in market over a two-year window. Evidence that the US buyout Fund 9, launched with a $5 billion anchor, is gathering commitments would support the super cycle narrative, as would continued growth in evergreen wealth assets, which reached $20 billion. Progress toward closing the second Unum reinsurance block, expected to add about $5 billion of credit assets later this year, matters too. On the risk side, any renewed redemption pressure in the wealth credit vehicle that management described as abating, or signs of portfolio stress from the energy price shock tied to the Strait of Hormuz, would undercut the confident tone. With fee-related margins held near 47% by deliberate reinvestment, there is little cushion if revenue softens.
Sentiment has soured markedly, with readings moving from about 8% bearish ahead of the last report to roughly 33% bearish now. The stock, at $38.53, sits well below its 200-day moving average of $47.67 and closer to its post-earnings low of $35.41 than to its high above $52. That setup lowers the bar in one sense, because a merely steady quarter could ease fears, but it also means a weak fundraising or fee print could reinforce the view that the cycle has peaked.
Ultimately, the report hinges on whether Carlyle's recurring fee base has genuinely stepped up. If management fees and fundraising keep climbing while transaction income normalizes, the June record looks like a new floor in the making and the selloff looks overdone. If earnings slip back toward earlier levels, the market's skepticism about the super cycle will have found its evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-15 | |
| Oct-05 | |
| Sep-29 | |
| Sep-24 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-10 | |
| Sep-10 | |
| Sep-04 | |
| Sep-03 | |
| Sep-03 | |
| Aug-19 |
