CareCloud Must Prove Its Back-Half Ramp Is Real After A Bruising Quarter
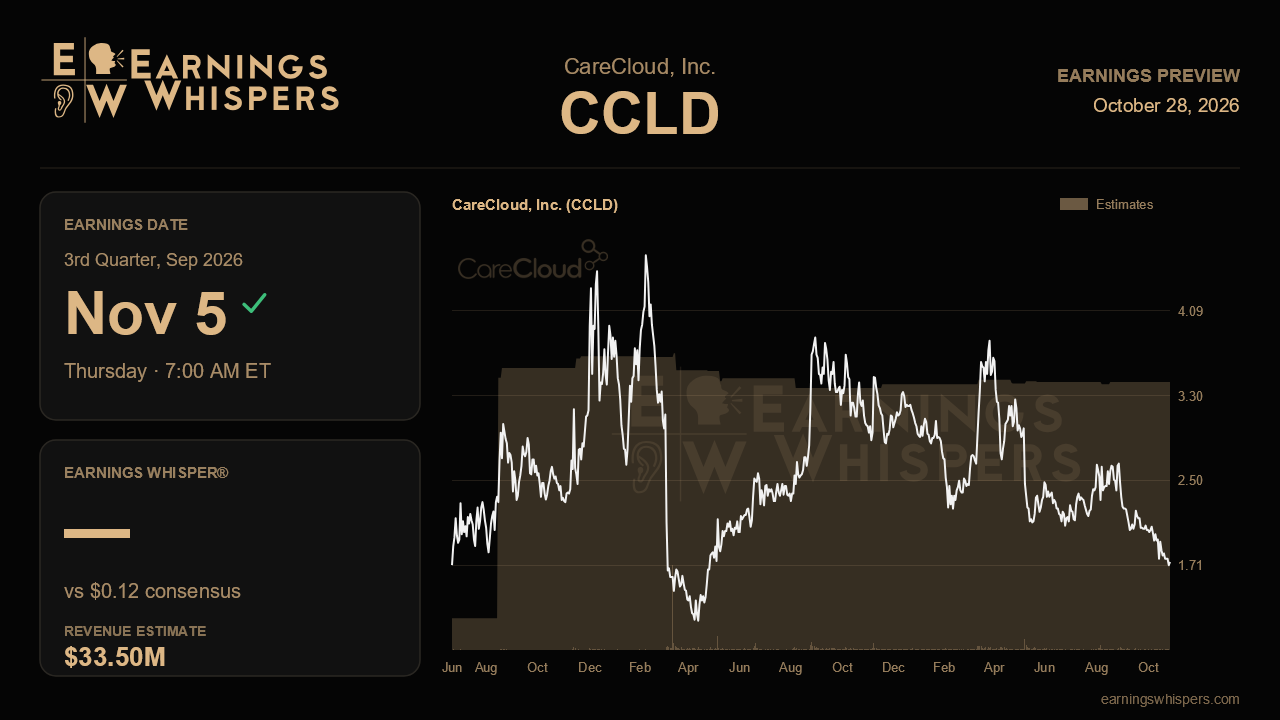
CareCloud heads into its third-quarter report with a simple problem: management told investors the year would be won in the back half, and this is the first quarter that has to show it. After a celebratory stretch of raised targets and record cash generation, the second-quarter call was shorter, more defensive and focused on explaining away margin pressure. The company now needs to show that its revenue run rate and profitability can climb at the same time, and the stock's slide suggests few are willing to take that on faith.
The Street is looking for earnings of $0.12 per share on revenue of $33.5 million, which would be 20% EPS growth and roughly 7.8% revenue growth from a year ago. That revenue growth is modest next to the 22% pace CareCloud posted at its fourth-quarter 2025 peak. The more telling comparison is sequential. Revenue was $31.9 million last quarter, and management said it needs $33 million to $34 million per quarter in the second half to hit its targets. Consensus sits right in the middle of that band. EPS is expected to double from last quarter's $0.06, so the estimate depends on margins recovering, not just on a modest revenue bump.
The full-year math raises the stakes. CareCloud reaffirmed revenue guidance of $128 million to $132 million, and consensus of about $131.5 million sits near the top of that range. With first-half revenue of roughly $63 million and a $33.5 million third quarter, the Street is effectively counting on a fourth quarter near $34.8 million, above last year's record. Management's GAAP EPS outlook of $0.20 to $0.23 also compares with a consensus near $0.36. That gap likely reflects a different earnings basis rather than a straight disagreement, but it shows how much the bar depends on cost leverage arriving on schedule.
Several things would validate the recovery story. This should be the first full quarter of contribution from Empower Healthcare and Compliance Partners, the compliance and defense services business that closed in mid-May. A visible lift from that deal, along with early signs of the referral flow its president has historically brought in, would help explain a jump toward $33 million or more. The sales force is now about three times its year-ago size and fully ramped, and management has pointed to it as a driver of cross-selling into the MedSphere hospital base. If that larger team is not producing visible wallet-share gains by now, the expense becomes harder to justify. On margins, the key question is whether the heavy spending to fix MedSphere's tech debt is tapering as implied. Falling amortization on acquired intangibles should help reported earnings, but a clean beat needs operating improvement, not just accounting relief.
The risks are just as concrete. Any sign that integration and remediation costs are persisting would undercut the doubling in EPS the Street expects. Investors will also want reassurance that the March cybersecurity breach at CareCloud Health stayed contained and that insurance is covering its costs. The AI platform talks with private equity groups and a large PE-backed client are worth watching, but they were unsigned last quarter. Unless management can point to a signed deal, they remain optionality rather than earnings support.
The market has already passed judgment on last quarter's tone. Shares have fallen about 21% since the last report while the S&P 500 was flat. At $1.74 the stock sits just above its post-earnings low of $1.70 and well below its 200-day moving average of $2.50, in a range that has shifted noticeably lower than the prior quarter's. Sentiment is mildly bearish and unchanged from three months ago. That combination lowers the bar for a relief move but leaves little patience for another explanation-heavy quarter. The central issue is whether CareCloud can reach the $33 million to $34 million revenue level while showing margins have turned the corner. Do both, and the back-half narrative survives. Miss either, and the near-high-end full-year consensus will look exposed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Sep-29 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 | |
| Jun-08 | |
| Jun-05 | |
| May-26 | |
| May-21 | |
| May-18 | |
| May-11 | |
| May-07 |
