Americold's First Post-JV Quarter Tests Whether Its Occupancy And Pricing Rebound Can Last
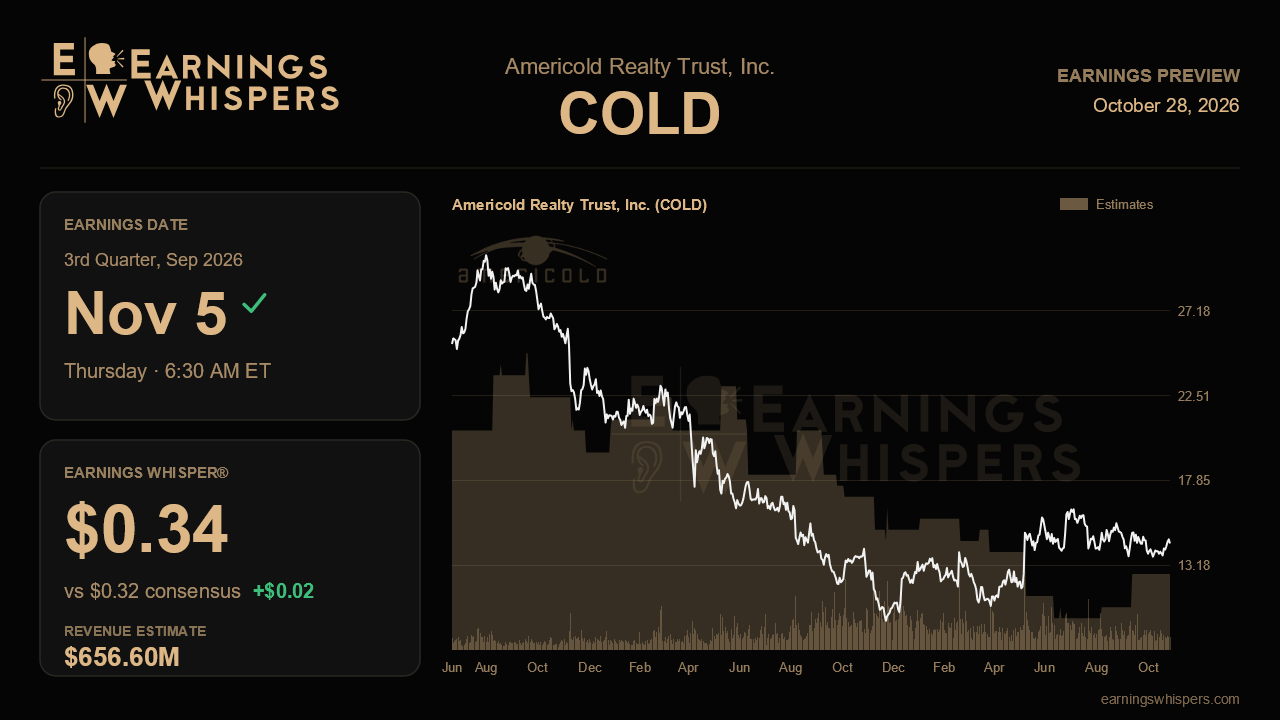
Americold Realty Trust spent most of the past year playing defense, so its second-quarter report felt like a turning point: occupancy and pricing beat plan, full-year guidance went up, and the long-awaited EQT joint venture cleared regulators. The market has not bought the story. Shares are down 6.2% since that report while the S&P 500 was essentially flat. The third-quarter release, due before the open on November 5, is the first real test of whether the improvement was durable or a one-quarter bounce.
The Street is looking for earnings of $0.32 per share on revenue of about $656.6 million. That would be down from $0.35 last quarter and a year ago, with revenue off about 1.1% year over year. The Earnings Whisper of $0.34 sits a bit above consensus, a sign that some investors expect another modest beat. The more interesting gap is in the annual numbers. Management now guides 2026 FFO to $1.26 to $1.32 per share, up from $1.20 to $1.30, yet full-year consensus is $1.23, below the bottom of the new range. Either analysts doubt the raise will hold, or estimates have not fully absorbed the dilution from the EQT deal. A quarter that clearly supports the guided range could force estimates higher.
The EQT transaction makes this quarter unusually messy. The $1.3 billion, 70/30 venture was expected to close in the third quarter. It should fund roughly $1.1 billion of debt paydown, about a quarter of total debt, and cut leverage by around three-quarters of a turn toward the sub-6x target. The cost is about $0.05 of 2026 dilution and a sizable drop in consolidated revenue and NOI. Clean disclosure on closing timing, interest savings and pro forma leverage will matter as much as the headline numbers. The same goes for any update on the Lancaster and Plainville wind-down after last quarter's $298.8 million impairment.
The operating story is where the narrative will be confirmed or challenged. Last quarter physical occupancy rose about 200 basis points sequentially and roughly 300 basis points year over year. Storage and handling pricing both turned positive, a sharp reversal from an original plan for blended declines of 100 to 200 basis points. Management also raised its economic occupancy outlook to a range of up 100 to down 200 basis points and now sees same-store revenue slightly positive, versus an early-year expectation of a 2.5% decline. Confirmation would look like occupancy holding its gains into the seasonal harvest period, the roughly 860-basis-point gap between physical and economic occupancy narrowing further, and pricing staying positive. Warning signs would include renewed price cutting by capital-constrained rivals, more tenants renewing fixed commitments at lower pallet counts, or a gap that stops shrinking.
Demand is the other variable. Management said plainly that its outlook does not depend on a recovery, citing food inflation, cautious consumers and excess distribution capacity. That makes the newer savings programs important: the $25 million Fit for Purpose SG&A initiative on top of the existing $30 million indirect labor program. Progress there would show the margin story does not depend on volumes.
Sentiment is still slightly bearish and almost unchanged from last quarter, so expectations do not look stretched. The stock, at $14.37, sits above its 200-day moving average of $13.77 and near the middle of its post-earnings range of $13.33 to $15.61. That is neither a breakout nor a breakdown. The decisive question is whether Americold can show that occupancy and pricing momentum survived the quarter as it absorbs the JV dilution. If it can, the gap between consensus and guidance becomes the catalyst. If not, the skepticism already in the stock will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-05 | |
| Aug-31 | |
| Aug-26 | |
| Aug-20 | |
| Aug-19 | |
| Aug-18 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-27 | |
| Jul-08 |
