Canadian Natural Faces Turnaround Drag And Fading SCO Premium After Record Quarter
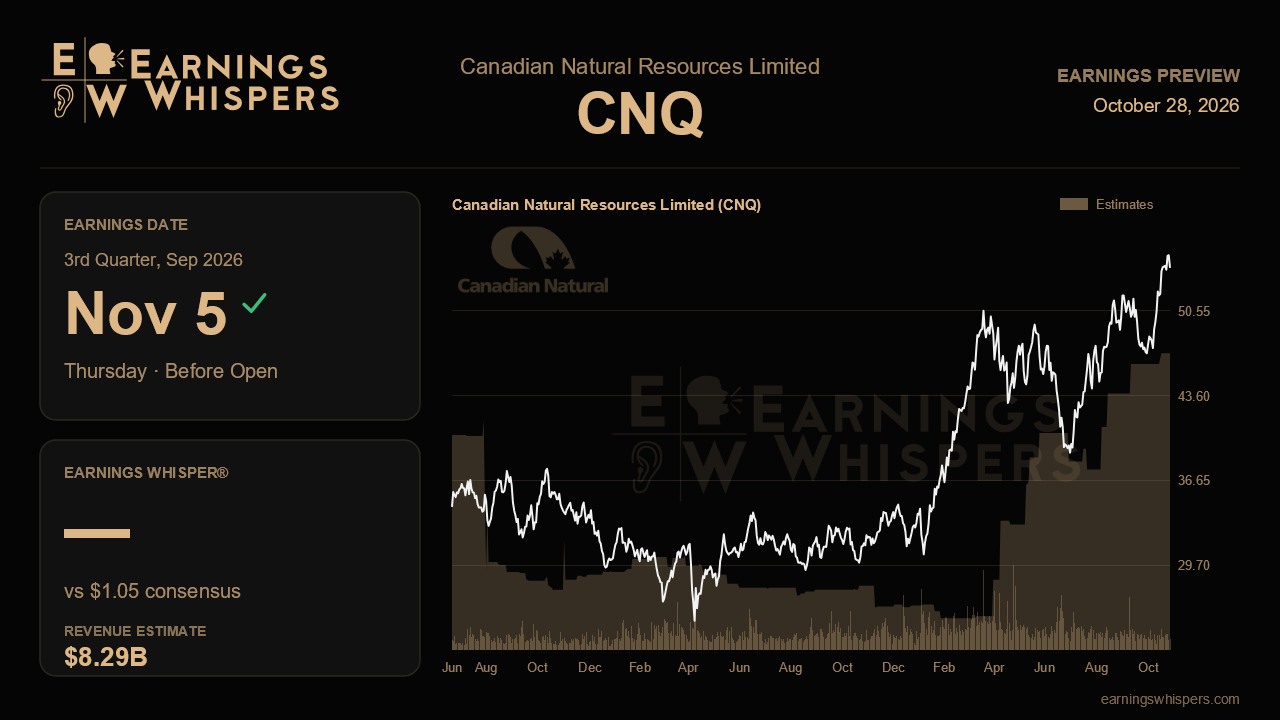
Canadian Natural Resources heads into its third-quarter report with an unusual setup: the Street expects earnings to fall sharply from the prior quarter, yet the stock is trading near its highs. That is not a contradiction so much as a test. Management told investors last quarter that the record results would not repeat in a straight line, citing a planned Horizon turnaround and a synthetic crude premium likely to drift back toward parity with WTI. The question for this report is whether the slowdown looks like the scheduled pause management described or something that weakens the momentum story.
Consensus calls for earnings of $1.05 per share on revenue of about $8.29 billion. That is a big step down from the $1.58 and $12.43 billion posted last quarter, but compared with a year ago it still looks healthy. Earnings are expected to rise roughly 69% from $0.62, while revenue is projected to grow only about 3%. That gap matters. It implies analysts expect most of the year-over-year gain to come from margins and cost control rather than higher sales, which fits a company that has kept pushing volumes higher while holding operating costs at industry-leading levels.
The operating backdrop management laid out last quarter was strong. Full-year production guidance has been raised twice this year, most recently to a range of 1.637 million to 1.682 million barrels of oil equivalent per day, and the second quarter delivered record corporate output near 1.677 million. Oil sands mining and upgrading ran above nameplate at 106% upgrader utilization, and Jackfish produced well above its rated capacity. The key piece of evidence this time is whether volumes outside the turnaround held steady enough to keep the annual guidance intact. Reaffirming the raised range despite Horizon downtime would validate the narrative. Trimming it, or describing a longer or costlier turnaround than planned, would challenge it.
Pricing is the other swing factor. The second quarter benefited from a synthetic crude premium of more than $8 per barrel over WTI, up from about $5 the quarter before, supported by strong diesel demand. Management explicitly guided investors to expect that premium to fade. A premium holding above parity would be upside to a cautious consensus, while a slide toward or below parity would mostly confirm what is already in the numbers. Investors should also check progress on net debt, which fell to $14.5 billion last quarter. Getting closer to the $13 billion level that shifts all free cash flow to buybacks, a milestone management has pointed to for early 2027, would matter more to the investment case than a few cents of earnings.
The market has already rewarded the story. Shares are up about 18% since the last report while the S&P 500 is roughly flat, and at about $54 the stock sits within 3% of its post-earnings high of $55.50 and well above its 200-day moving average near $45.60. Sentiment has also shifted from slightly bearish going into last quarter to modestly bullish now. That combination raises the bar. A clean quarter could push the stock through its recent high, but a stretched setup leaves less room for disappointment.
The biggest open question may not be in the quarterly figures at all. Major growth projects, including the Jackfish expansion, Pike II and further mining growth at Albion and Horizon, remain on hold until the definitive agreements under the trilateral MOU with Alberta and Ottawa are finalized, which management targeted for this fall. Any update on that timeline will shape whether Canadian Natural is seen as a disciplined cash machine or a company ready to grow again. If the turnaround stays on schedule, guidance holds and the regulatory path looks clearer, the improving narrative from last quarter remains firmly intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-06 | |
| Sep-23 | |
| Sep-15 | |
| Sep-11 | |
| Sep-10 | |
| Sep-06 | |
| Aug-26 | |
| Aug-26 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-27 |
