GEO Group's Detention Rebound Faces Proof Test After Third Straight Guidance Raise
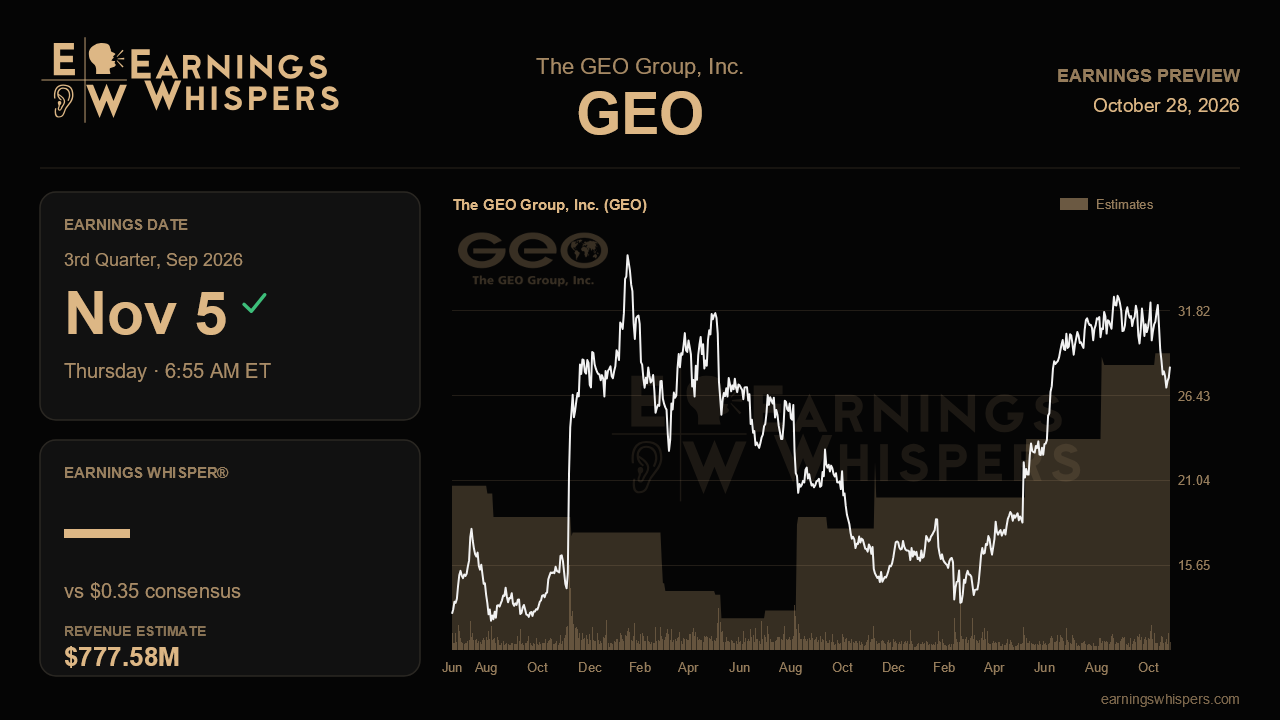
GEO Group enters its third-quarter report with an odd disconnect. Management has raised its full-year outlook three quarters in a row, detention populations have bounced back after a funding scare, and two sizable new ICE contracts are in hand. Yet the stock has slipped about 9.5% since the last report while the S&P 500 was essentially flat. The release, due before the open on November 5, needs to show that the post-shutdown recovery management described in the summer actually carried through the quarter.
Wall Street expects earnings of $0.35 per share on revenue of $777.6 million. That would be a 40% jump in earnings and 14% revenue growth from a year ago, which is strong by any standard for a government services contractor. The Street has also moved up to meet management. Analysts were near $0.30 before GEO guided to $0.35 to $0.37 for the quarter, and consensus now sits at the low end of that range. Revenue expectations fall comfortably inside the $755 million to $805 million guide, just shy of the midpoint. One detail stands out. Consensus implies earnings slightly below the $0.37 posted last quarter even as revenue rises about $45 million sequentially. That leaves room for an upside surprise if margins hold, but it also suggests analysts are allowing for startup costs or a mix shift that could dilute profitability.
The most important operating test is detention census. ICE populations at GEO recovered to roughly 24,000 last quarter after dipping near 21,000 during the shutdown. Management also pointed to a 20% population surge in the six weeks after the Secure America Act restored ICE and CBP funding. If that momentum held through September, the quarter should land at or above the top of guidance. If census stalled, the summer optimism will look more like a one-time rebound than a trend. The electronic monitoring business is the second swing factor. Total ISAP participants have been stuck around 180,000 to 184,000 for about two years, but the move toward ankle monitors, which rose to about 54,000 from 42,000 at the start of the year, has lifted segment margins without any volume growth. Continued gains in that mix would support the margin story even if counts stay flat.
Several loose ends from the last call also deserve updates. The Bighorn and Rivers reactivations, worth roughly $165 million in combined annual revenue starting in early 2027, should be moving through preparation, and any sign of cost overruns or timing slippage would matter given ICE is reimbursing the capital outlay. The lowered capital spending plan of $135 million to $145 million, with 2027 below $100 million, is a free cash flow promise that should show up in the numbers. Skip tracing produced no revenue last quarter, so any restart would be a welcome bonus. The Florida managed-only contracts, already pushed to mid-2027, carry risk of further delay. The biggest wildcard remains a potential sale of facilities to ICE. Management sounded more confident last quarter, but there was still no definitive agreement or timeline, and progress here could reshape how the market values the company.
Sentiment has cooled noticeably, with bullish readings roughly halving from the prior quarter, though still positive. The shares trade at $28.27, comfortably above the 200-day moving average near $24 but in the lower half of the post-earnings range between about $26 and $33. That is a skeptical setup for a company that keeps raising its numbers.
With three raises already banked, an in-line quarter alone may not reverse the stock's slide. The real question is whether GEO can show that detention demand and monitoring margins are building toward 2027 rather than peaking. A fourth increase to the $1.27 to $1.32 full-year range, or concrete progress on a facility sale, would reaffirm the narrative. Merely reiterating guidance would leave doubts about whether the recovery has already run its course.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 15 hours | |
| Oct-28 | |
| Oct-19 | |
| Oct-15 | |
| Oct-06 | |
| Oct-05 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 | |
| Jul-13 | |
| Jul-09 | |
| Jun-20 | |
| May-23 | |
| May-23 | |
| May-06 |
