1-800-Flowers Heads Into Its Seasonal Trough With Liquidity, Not Losses, As The Real Test
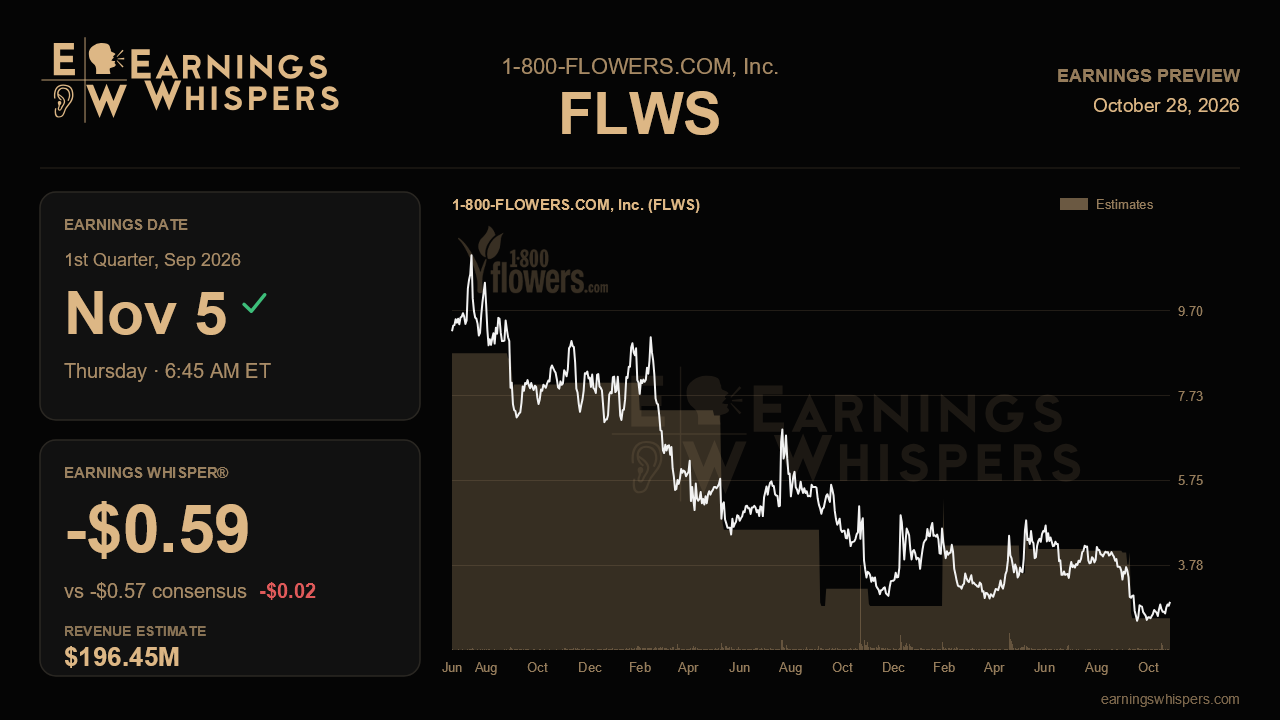
For most retailers, the September quarter is a throwaway: a seasonally quiet stretch before the holidays that rarely moves the story. For 1-800-Flowers, it carries unusual weight. The company exited fiscal 2026 with just $11 million in cash against $139 million of term debt, an amended credit facility with covenant relief, and Guggenheim Securities hired to explore debt or equity raises and possible sales of brands and hard assets. The fiscal first-quarter report is the first look at how that balance sheet holds up while the business spends to build holiday inventory, and it may be the first update on whether the strategic review has produced anything concrete.
The Street expects a loss of $0.57 per share on revenue of about $196.5 million. That would be a 31% narrower loss than last year's $0.83, but on sales down 8.7%. In other words, analysts are betting that cost cuts do the heavy lifting while the top line keeps shrinking. The whisper number sits a bit lower at a $0.59 loss, a small gap that suggests the more engaged crowd is not leaning toward an upside surprise. The bigger disconnect is on the full year. Management guided fiscal 2027 revenue to roughly $1.43 billion, a mid-single-digit decline, while consensus still sits near $1.48 billion. Analysts are above the company's own outlook, and an 8.7% drop in the first quarter would make even management's number dependent on a meaningful improvement later in the year. If revenue lands near consensus, expect pressure for the Street to come down toward guidance.
The operational case rests on a few green shoots from last quarter. The original $50 million cost-savings target was reached ahead of schedule, with another $15 million to $20 million identified. BloomNet returned to modest growth after several quarters of decline. Third-party marketplaces such as Amazon, DoorDash and Instacart were growing at double- to triple-digit rates while staying contribution-margin positive, and average order value rose 5.5% last year. Validation this quarter would look like BloomNet holding positive, marketplace growth continuing, and order value gains partly offsetting a transaction count that fell 17.6% in fiscal 2026. A narrower revenue decline than the fourth quarter's 12.9% drop would be the clearest sign that stabilization talk was not premature.
Margins are the swing factor. Last quarter's gross margin benefited from a roughly $7 million tariff refund that will not repeat, while management flagged rising flower and cocoa costs and fuel surcharges on outbound shipping. Fiscal 2027 adjusted EBITDA guidance of $10 million to $15 million also absorbs about $12 million of added incentive pay. If gross margin slips meaningfully year over year, the cost savings may merely be refilling holes rather than creating leverage, which would challenge the earnings recovery embedded in that 31% improvement.
The market is not giving the company much benefit of the doubt. Shares have slipped 2.3% since the last report while the S&P 500 gained 1.5%, and at $2.92 the stock trades well below its 200-day moving average of $3.66. It sits in the middle of a $2.37 to $3.37 post-earnings range that is entirely beneath the prior quarter's $3.31 to $5.09 band, a sign of a lower valuation regime rather than a basing pattern. Sentiment has cooled as well, with bullish readings easing from 39.2% to 34.4% ahead of the report.
Ultimately, this quarter hinges less on whether the loss is a few cents better or worse than forecast and more on whether 1-800-Flowers can show it has the runway to finish its turnaround. Investors need to see controlled cash burn, a credible financing or divestiture path, and evidence that revenue declines are narrowing toward the guided pace. Deliver those, and the cost program starts to look like a foundation. Miss on them, and the conversation shifts further from transformation toward survival.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-19 | |
| Oct-15 | |
| Sep-30 | |
| Sep-29 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 | |
| Aug-19 | |
| May-07 | |
| May-06 | |
| Apr-23 | |
| Apr-15 |
