First Advantage Must Prove Its Base Revenue Turn Can Outlast Tougher Comparisons
First Advantage enters its third-quarter report with something it lacked for most of the past two years: a genuine growth story inside its existing customer base. Base revenue, the business it earns from established clients, swung to growth of 6.7% last quarter after sitting flat in the first quarter and shrinking in the quarters before that. The question now is whether that turn was the start of a durable recovery or a high-water mark, because management has already signaled that headline growth will cool in the back half of the year.
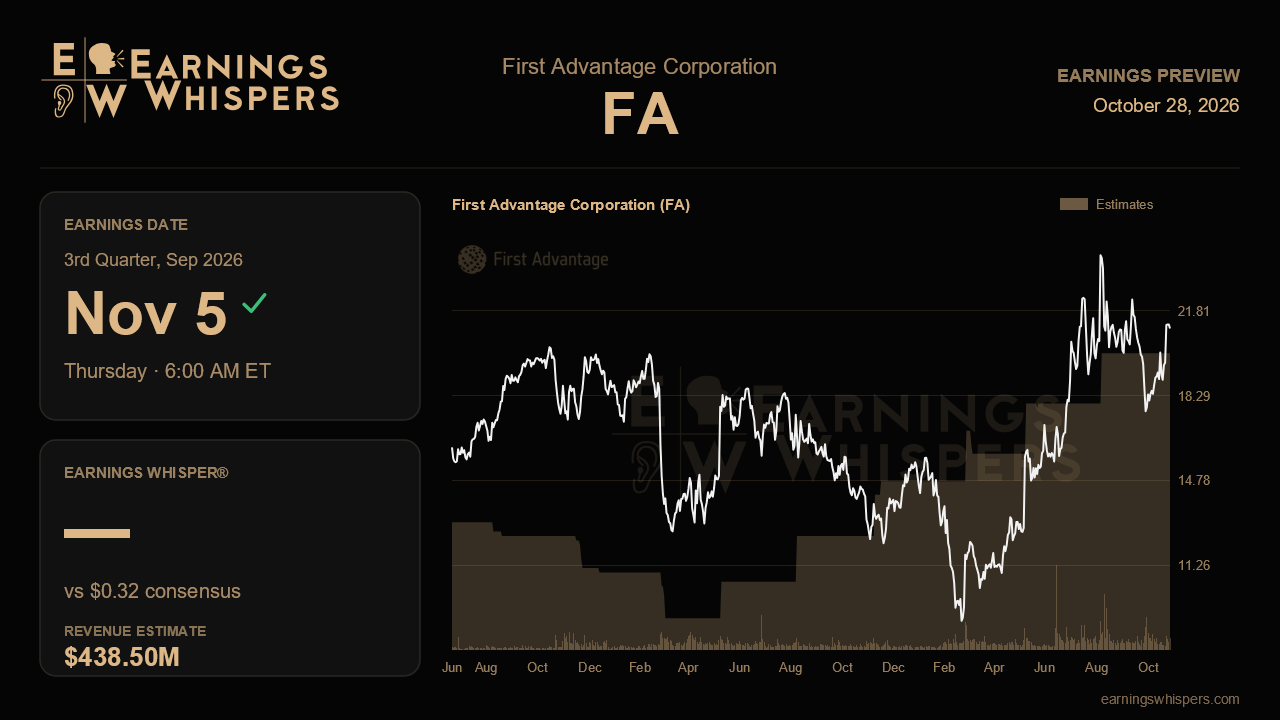
Wall Street expects earnings of $0.32 per share on revenue of $438.5 million when the company reports before the open on November 5. That revenue figure implies growth of about 7.2% from a year ago, a solid but unspectacular pace, and it sits below the $448.8 million posted last quarter. Earnings would be modestly below the prior quarter's $0.33 but comfortably above the $0.27 earned a year earlier. Full-year expectations look conservative relative to the company's own outlook. After raising guidance last quarter, management now calls for adjusted earnings of $1.23 to $1.29 per share on revenue of $1.67 billion to $1.71 billion. The consensus of $1.23 per share sits right at the bottom of that range, and the $1.68 billion revenue estimate lands in the lower half. Analysts, in other words, have accepted the raise but have not leaned into it.
That caution traces directly to the tone of the last call. Management guided the third quarter's base business to slightly positive growth, an upgrade from its earlier framing of flat to down 2%, but it also trimmed its fourth-quarter revenue growth view to low-to-mid single digits from mid-to-high single digits. The reason is arithmetic more than demand: the fourth quarter of 2025 grew 12%, with new logos and upsell contributing 17%, and those large go-lives are now fully in the comparison. Some new wins are also taking longer to implement and will slip into early 2027. A third-quarter print that clears the slightly positive base bar with room to spare would validate the idea that underlying demand is improving even as reported growth slows. A base number that slides back toward zero would suggest the second quarter benefited from one-time activity.
That distinction matters because roughly half of last quarter's base growth came from customers rescreening workforces as they reshape their labor pools. Such projects can be lumpy. Evidence that upsell and cross-sell held near the 8% pace of recent quarters, that retention stayed around 97%, and that digital identity products kept lifting package sizes would show growth resting on something sturdier than episodic rescreening. Margins are another checkpoint. Management guided adjusted EBITDA margins roughly flat with the second quarter, a step back from the higher second-half ramp it once described, so any slippage would sting. Progress on Sterling integration synergies, which are slated to be fully actioned by year-end, also bears on the 2027 earnings setup. India, about 3% of revenue, is a minor but visible soft spot tied to Middle East tensions and fuel prices.
Sentiment has improved, moving from clearly bearish heading into last quarter to essentially neutral now. The stock has not shared that enthusiasm, slipping about 4.9% since the last report while the S&P 500 was flat. At $21.08, shares trade well above their 200-day moving average of $16.24 but roughly 16% below the post-earnings high of $25.15, suggesting investors bought the guidance raise and then took profits as the deceleration message sank in.
The central test is whether the base business keeps growing as the easy comparisons disappear. If it does, and management holds or nudges up its full-year range, the Street's bottom-of-range estimates look too low. If base growth fades, the inflection narrative will look more like a single strong quarter than a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Sep-02 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-21 | |
| Jul-16 | |
| Jul-15 | |
| Jun-11 |
