Evergy's Third Quarter Tests Whether Data-Center Momentum Can Become Its Next Signed Contract
Evergy heads into its third-quarter report with a story that has grown more ambitious for four straight calls, and a summer quarter that should show whether the earnings are keeping pace. The Kansas and Missouri utility has stacked up data-center supply agreements, lifted its load-growth and rate-base outlooks, and expanded its capital plan. Last quarter, though, it mostly held steady. That makes this report less about whether the vision exists and more about whether the next concrete step arrives on schedule.
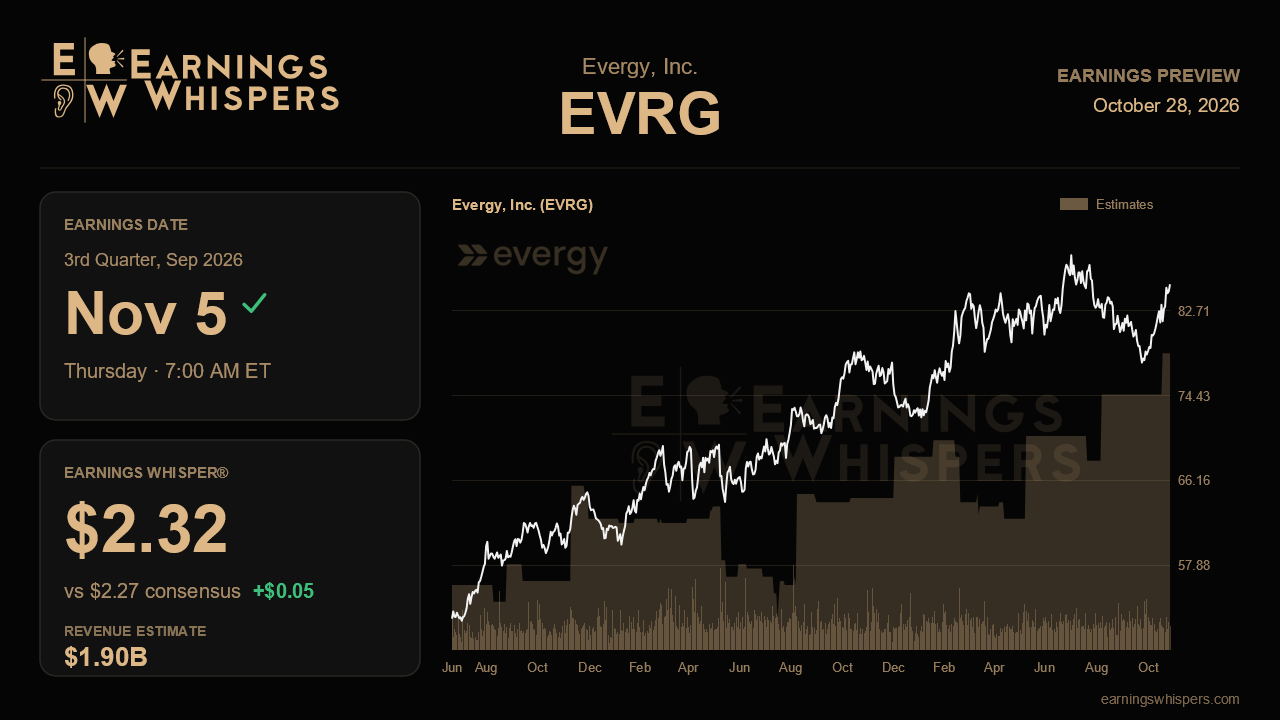
Wall Street expects earnings of $2.27 per share on revenue of about $1.90 billion. Results are due before the market opens on November 5. That would mean roughly 12% profit growth from the $2.03 earned a year ago, on revenue up about 5%. For a regulated utility, that is a strong showing. The third quarter is Evergy's biggest by far because of summer cooling demand, so this report carries an outsized share of the full-year result. The Earnings Whisper sits at $2.32, a bit above consensus. That suggests some investors expect upside, likely helped by the industrial and commercial strength management highlighted in the spring. The gap is modest, but it does raise the bar beyond a simple in-line print.
Management has reaffirmed full-year guidance of $4.14 to $4.34 per share. The $4.25 consensus sits essentially at the $4.24 midpoint. That placement matters given recent history. Fiscal 2025 adjusted earnings of $3.83 fell short of the guidance midpoint because of mild weather and soft industrial demand. A strong third quarter would put that miss further behind the company and make the midpoint look safe. A weather-driven stumble in the peak quarter would revive questions about how much of the plan rests on factors management cannot control.
The operating evidence to look for builds directly on the second-quarter call. Weather-normalized demand was up 3.3% through midyear, with commercial up 4% and industrial up 6.2% as Panasonic's battery plant ramped. Sustaining those gains would support the 7% to 8% retail load-growth target through 2030. The bigger catalyst is the pipeline:
- **Signed agreements:** Evergy now has five signed agreements totaling roughly 2.5 gigawatts of steady-state peak load.
- **Expansion potential:** Expansion opportunities at existing sites doubled to 2.0 to 2.5 gigawatts.
- **Tier 2 prospects:** A separate group of 1 to 2 gigawatts involves new customers who have secured land and signed letters of agreement.
- **Next contract:** Management said it was highly confident of signing at least one more agreement in 2026.
An announcement, or clear evidence that one is close, would validate the roughly 12% rate-base growth outlook and the plan for more than 8% annual earnings growth from 2028. Silence on new contracts would not break the thesis, but it would make the steady escalation look more like a plateau.
The risks are largely regulatory and political:
- **Missouri Metro rate case:** Hearings began in October, so any commentary on settlement or staff positions bears watching.
- **Kansas politics:** A proposed data-center moratorium became an issue in the governor's race. Management played it down, and updates on how that debate is evolving will matter.
- **Equity funding:** The company had priced $425 million of its $700 million to $900 million equity need through forward sales. Progress there shows how smoothly it is funding the larger capital plan.
- **Customer bills:** Planned filings for new gas, solar and storage capacity will draw scrutiny as residential rates in Missouri West climb faster than inflation.
Expectations appear measured rather than euphoric. Sentiment is mildly bearish but improved from the prior quarter. The stock has gained about 0.7% since the last report while the S&P 500 was roughly flat. At $85.30, shares sit above the 200-day moving average and within a fraction of the post-earnings high of $85.56, effectively testing a breakout. They remain below the prior quarter's peak near $88.62. A clean beat, paired with a contract signing or firm signs of one, could push the stock through that resistance.
The central question is whether Evergy can turn a strong pipeline into signed load while delivering a summer quarter solid enough to protect its guidance midpoint. If both happen, the data-center growth story keeps building. If neither does, the latest quarter of reaffirmation starts to look like the pause before expectations cool.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-15 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 | |
| Jun-29 | |
| May-08 | |
| May-07 | |
| May-07 | |
| Apr-16 | |
| Apr-14 | |
| Mar-30 | |
| Mar-03 | |
| Feb-21 |
