Liberty Capital Must Show Quintillion Deal Can Offset Margin Squeeze During Peak Spending Year
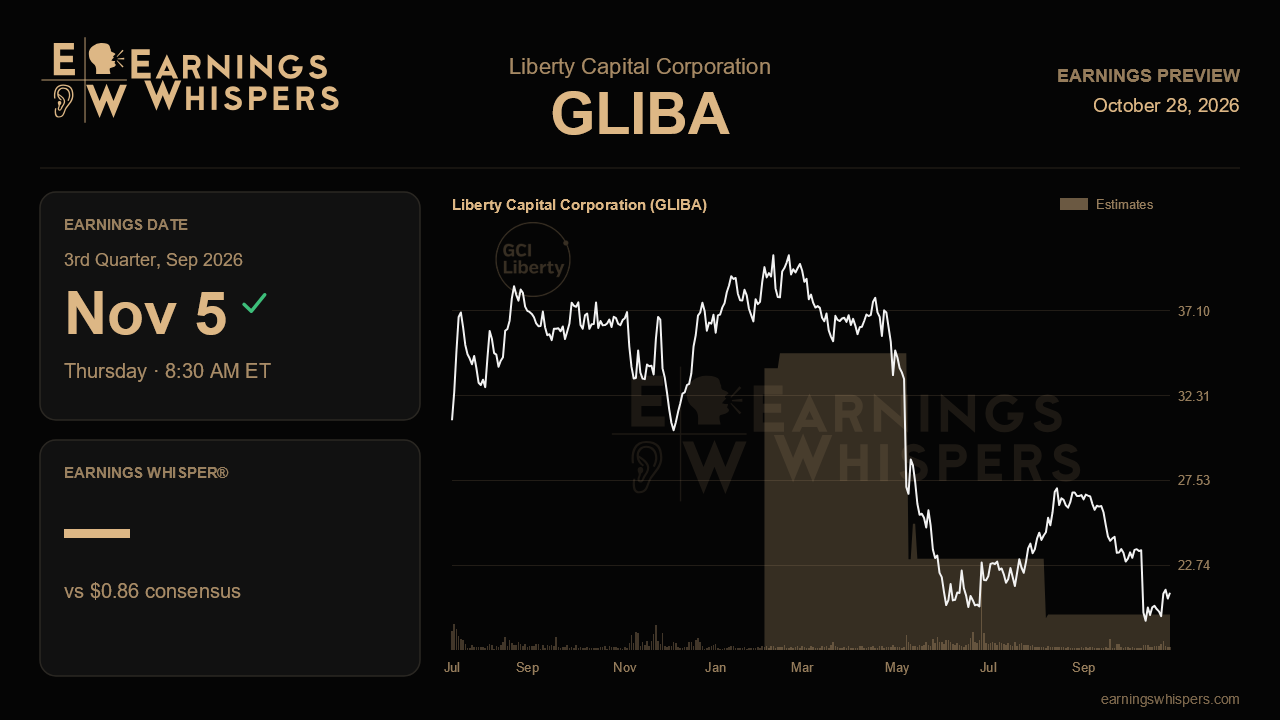
Liberty Capital heads into its November 5 report with a story that sounds better than its numbers. On the prior call, its first under the new name, management laid out a dividend, a leverage target and quantified synergies from the quintillion fiber acquisition. Meanwhile, adjusted EBITDA, business margins and free cash flow kept sliding. The stock has sided with the numbers so far, falling 13.3% since that report while the S&P 500 was flat. This quarter should help show which side is right.
The Street expects earnings of $0.86 per share, an 81.9% drop from $4.76 a year ago. That comparison sounds alarming, but the year-ago figure was far out of line with the company's usual run rate, so the headline decline says little about the operating business. A better yardstick is the $0.40 earned last quarter. Against that, the consensus implies a meaningful step up. Revenue has been remarkably steady, at about $261 million last quarter versus $257 million a year earlier, and management has described the year as stable rather than a growth year. Without a fresh guidance update, the main question is whether profitability can stop deteriorating, not whether the top line can surprise.
Quintillion is the swing factor. Management said the deal should add roughly $50 million to $55 million of adjusted EBITDA this year including synergies. It also targeted about $20 million in run-rate savings over two years, half of that in the first twelve months, and said the deal would add to free cash flow in year one. This report should offer some of the first evidence on whether that contribution is showing up. Last quarter's EBITDA of $96 million was down 11% from a year earlier, extending a string of declines. A stabilization, or ideally a return to year-over-year growth, would support management's argument that the drag was temporary. Another decline would make the synergy math look more distant.
Margins are the other test. Business gross margin fell to 75.5% from 77.3% the prior quarter and roughly 80% for last fiscal year. The causes were about $9 million in higher distribution costs, part of it from restored quintillion service, plus pricier circuits tied to network upgrades. Once quintillion is owned rather than leased, some of that cost should reverse into savings. Any sign of margin recovery would carry weight. On the consumer side, wireless net additions climbed to about 2,100 from 1,000, and bundling deepened, with 42% of broadband customers also taking wireless. The weak spot is organic broadband, which still lost about 500 subscribers last quarter. Starlink remains a live competitive threat in rural Alaska, so a quarter of flat or positive organic broadband would be more meaningful than another acquisition-aided gain.
Cash flow matters for a newly minted dividend payer. Trailing free cash flow fell to $59 million as capital spending peaks near $290 million this year. Net leverage at GCI rose to 2.8x, just under the roughly 3x long-term target. A $60 million annual dividend is easily covered if management's forecast of a 2027 cash ramp holds. With leverage near the ceiling, though, any slippage in spending discipline or EBITDA would draw scrutiny.
Sentiment has softened from 33.1% bearish ahead of last quarter to 13.8% bearish now, so skepticism has eased even as the stock has fallen. At $21.19, shares sit well below the 200-day moving average of $29.13 and closer to the post-earnings low of $19.30 than the high of $27.79. That leaves a low bar for relief but little patience for another soft quarter. In the end, the narrative holds only if quintillion starts to reverse the EBITDA and margin slide. Without that, the capital-return pitch rests on promises about 2027 rather than proof in 2026.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-08 | |
| Aug-06 | |
| Aug-06 | |
| Jul-14 | |
| Jul-14 | |
| May-21 | |
| May-11 | |
| May-06 | |
| Apr-22 | |
| Apr-20 | |
| Apr-20 | |
| Mar-06 |
