Hope Bancorp Narrowly Misses On EPS As Margins Expand, But Post-Manubank Guidance Cuts And Rising Delinquencies Complicate The Story
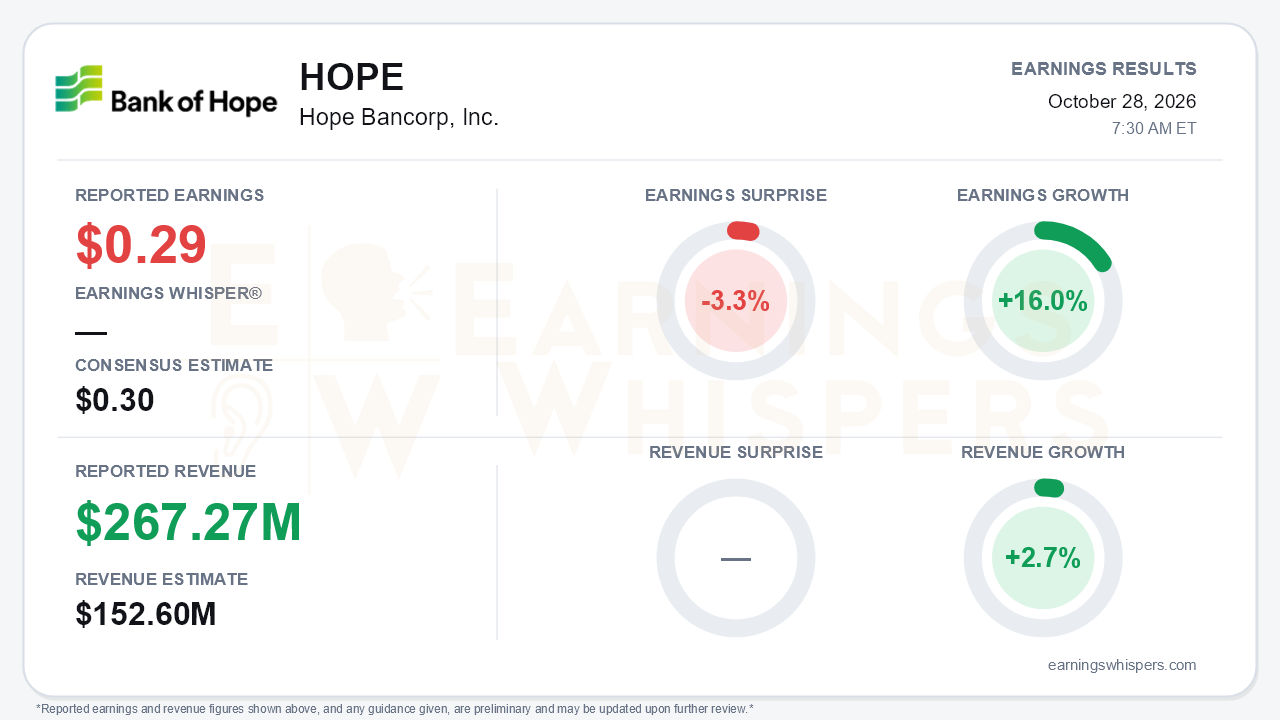
Hope Bancorp (NASDAQ: HOPE) reported third-quarter earnings of $0.29 per share excluding merger-related costs, a penny below the $0.30 consensus and a 3.3% miss. Earnings still grew 16.0% from a year ago, and GAAP EPS rose to $0.28 from $0.26 in the second quarter. The narrow miss is less important than the shape of the quarter. Hope's organic franchise improved again, with wider margins, lower funding costs and better operating leverage. Management's first full-year outlook that includes the MANUBANK acquisition, however, trimmed several key targets. That is the central tension: the bank is executing better while the deal arithmetic looks somewhat less generous than investors were promised.
The revenue comparison needs context. Earnings Whispers recorded revenue of $267.27 million, 75.1% above the $152.6 million consensus and up 2.7% year over year. That figure reflects gross interest income plus fee income. The company's own net revenue measure, net interest income plus noninterest income, was $157.5 million, up 7% sequentially and 11% from a year ago. That measure is the closer match to how the consensus appears to be framed, so the outsized revenue surprise mostly reflects a difference in definitions rather than a blowout. On the underlying numbers, the quarter was solid:
- **Net interest income** rose 5% sequentially to $135.4 million.
- **Net interest margin** widened six basis points to 3.02%, up from 2.90% in both the first quarter and late 2025.
- **Loan yields** rose to 5.78%, while total deposit costs slipped to 2.58%.
- **Noninterest income** jumped 17% to $22.1 million. Customer fees and SBA gains helped, but $3.1 million came from gains on other loan sales, which flatters the run rate.
- **Efficiency** improved, with the adjusted efficiency ratio falling to 63.6% from 65.2%.
- **Pre-provision net revenue** rose 11% sequentially and 21% year over year.
The call shifted attention to the forward picture. MANUBANK closed October 1, roughly a quarter ahead of earlier modeling assumptions. Hope received about $307 million in cash and roughly $2.6 billion of deposits at a 2.22% cost, with no deposit premium. Pro forma, time deposits fall to about 33% of the mix. Management also raised its cost-save estimate to more than 40% of MANUBANK's $136 million expense base and pointed to a roughly $90 million loan discount that should support purchase-accounting accretion over about two years. Several targets moved the wrong way, though:
- **PPNR growth guidance** for 2026 fell to 23-25% from 25-30%, a range management had held for three straight quarters.
- **Year-end loan growth** guidance dropped to about 15% from about 20%.
- **Revenue growth guidance** narrowed to 16-18% from 15-20%, below the "higher end" framing offered earlier in the year.
- **Full cost saves** slipped to 2028 because of core conversion timing, so near-term expenses should run above expectations.
- **The acquired loan book** came in near $2.2 billion, versus about $2.5 billion at announcement, and Hope sold the low-yielding $0.2 billion SBA piece at par.
Capital and credit give bears legitimate ammunition. CET1 drops roughly 200 basis points to about 10.2% after the close. Higher long-term yields cut AOCI by $59 million, pushing the tangible common equity ratio down to 9.28% from 9.58% and tangible book to $13.55 per share. Headline credit looked benign: net charge-offs fell to 0.19% and nonperforming assets eased to 0.57%. Beneath that, accruing loans 30-89 days past due more than tripled to $65.3 million from $19.0 million. Most of the increase was in commercial real estate, which climbed to $54.5 million from $15.9 million. The call did not dwell on this, but early-stage delinquencies deserve close monitoring. On the positive side, management noted that 48% of loans are straight variable and another 27% hybrid. That positions the book for the expected 2027 rate hikes, though management also expects deposit betas to accelerate with each further hike.
Investor sentiment soured heading into the report, swinging from a mildly positive 0.15 to a negative -0.25. That is a meaningful shift and suggests expectations were already being reset. The stock has held up better than the mood. Shares closed at $14.12 before the release, up 3.9% from the open after the July report and about 10% above the 200-day moving average. They sat roughly 3% below the $14.59 52-week high set in mid-August and well off the $13.00 low hit on the day MANUBANK closed. The Earnings Whispers trend signals lean constructive, with momentum and AVWAP positive while price trend is neutral.
The bottom line is that Hope delivered a better quarter than the one-cent miss implies, with margin expansion, operating leverage and cleaner funding all moving in the right direction. The investment case now rests on MANUBANK, and the first integrated outlook delivered lower growth targets, delayed savings, thinner capital and a smaller acquired loan book. Investors are being asked to accept slower near-term payoff in exchange for a stronger deposit franchise and rate leverage in 2027. Whether the jump in commercial real estate delinquencies proves temporary will matter as much as the deal math.
Read our earnings preview for Hope Bancorp, Inc.: https://www.earningswhispers.com/article/HOPE/20856
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-01 | |
| Sep-02 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-20 | |
| Apr-29 |
