Provident Financial Misses On Provision Build As Its Margin Tailwind Begins To Fade
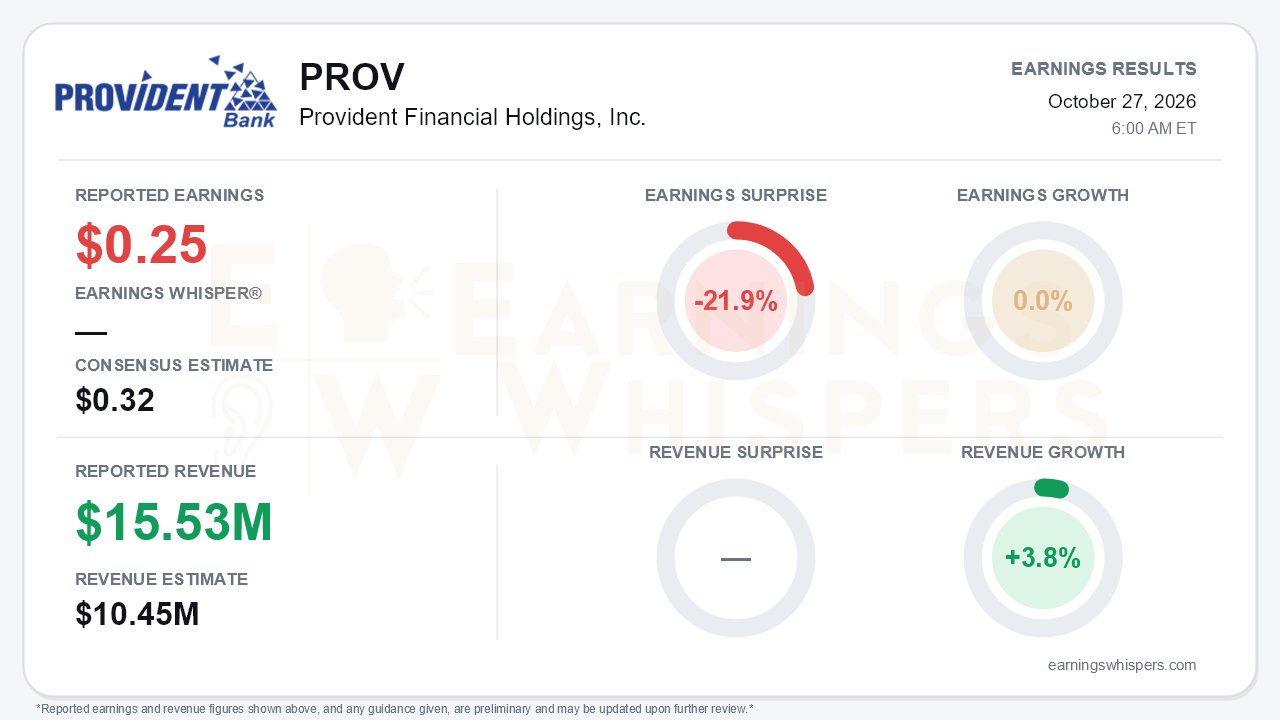
Provident Financial Holdings (NASDAQ: PROV) reported fiscal first-quarter earnings of $0.25 per share, missing the $0.32 consensus estimate by 21.9% and coming in flat year over year. Earnings also fell sharply from $0.35 in the June quarter. Revenue of $15.53 million beat the $10.45 million consensus by 48.6% and grew 3.8% from a year ago. That beat should be read with caution, though. The reported figure appears to reflect gross interest income plus fee income, while the consensus figure looks closer to a net revenue measure. Net interest income of $9.77 million plus $804,000 of non-interest income lands much nearer the estimate. The more important story is not the miss itself but what sits beneath it: a reserve build, a flattering one-time item in the margin, and clear signs that the funding-cost tailwind behind the past year's improvement is running out.
The miss was largely a provisioning event. Provident recorded a $777,000 provision for credit losses, compared with a $95,000 recovery in the prior quarter and a $626,000 recovery a year ago. Management attributed the build mainly to higher rates extending the expected life of the loan portfolio, not to borrower stress. Non-interest income also fell $479,000 sequentially because the prior quarter included a Visa share-conversion gain.
On a pre-provision basis, the core engine looks healthier:
- Net interest income rose $459,000 sequentially and $840,000 year over year.
- Non-interest expense slipped to $7.62 million.
- The efficiency ratio improved to 72%, from 73% last quarter and 78% a year ago.
The year-over-year comparison also benefited from a much lower effective tax rate, 27.8% versus 38.5%, driven by stock-based compensation benefits. Without that, the flat EPS result would have looked weaker.
The headline net interest margin of 3.32%, up 11 basis points sequentially and 32 basis points year over year, extends a steady climb from 3.00% a year ago. The call made clear, however, that roughly 10 basis points came from a $307,000 special FHLB dividend. Adjusted for that item, the margin was about 3.22%, essentially flat against 3.21% in the prior quarter, after 8 basis points of expansion in the June quarter. Management's framing of funding costs has also shifted over recent quarters:
- Two quarters ago, maturing funding was expected to reprice lower.
- Last quarter, the expectation moved to comparable rates.
- Now management expects maturities to reprice somewhat higher and described the downward repricing benefit as largely behind it.
Roughly $104.9 million of wholesale funding maturing at 3.94% is expected to reset upward. Deposit costs are already rising, with the average cost up to 1.47%, while core transaction balances fell $11.3 million in the quarter. Management guided to smaller margin expansion in the December quarter. That is the central tension: the reported margin trend looks strong, but the underlying expansion has nearly stalled.
There are still credible offsets:
- About $116 million of adjustable-rate loans reprice roughly 65 basis points higher, to 7.21%, in the December quarter. That is a meaningful tailwind, though smaller than the prior quarter's $133 million at 79 basis points.
- New production is coming on at 6.19%, against a 5.43% portfolio yield.
- Lower payoffs helped net loan growth reach about $4 million.
Originations, however, dipped to $45.4 million. Management softened its outlook from the upper end of its $29–46 million range to simply within the range, citing holiday seasonality. Credit remains pristine on the surface, with non-performing assets of $504,000 (0.04% of assets) and no charge-offs. Classified assets did rise to $4.1 million from $2.5 million, as substandard loans nearly doubled, a detail worth monitoring even at small absolute levels.
Capital return remains a pillar of the story. The company repurchased 86,431 shares at an average of $18.30, below book value of $20.24, and maintained its $0.14 quarterly dividend. A new 5% buyback was approved in October. Total capital returned equaled about 158% of net income, which underscores how modest earnings are relative to payouts. The bank's Tier 1 leverage ratio also fell to 9.25% from 10.30% during the quarter. It remains well capitalized, but capacity is not unlimited.
Investor sentiment was essentially unchanged, edging up to 0.40 from 0.39 and remaining moderately positive. Shares sit at $18.20, up 4.1% since the open after the July report and about 6% above the 200-day moving average of $17.17, yet still below book value. The Earnings Whispers trend readings are mixed, with price trend neutral and AVWAP negative, suggesting the stock's recent progress has been steady rather than forceful.
The bottom line is that Provident's miss was driven more by a reserve build than by operating deterioration, and pre-provision profitability and credit quality remain solid. But the quarter's margin strength was partly borrowed from a one-time dividend, funding costs are turning against the bank, and origination guidance was trimmed. Loan repricing and buybacks below book value provide support, but the easy margin gains appear to be over.
Read our earnings preview for Provident Financial Holdings, Inc.: https://www.earningswhispers.com/article/PROV/21002
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-01 | |
| Aug-05 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-23 |
