Fortive Beats And Raises Again As Core Growth Accelerates, But Buybacks And A Soft Healthcare Segment Temper The Quality Of The Quarter
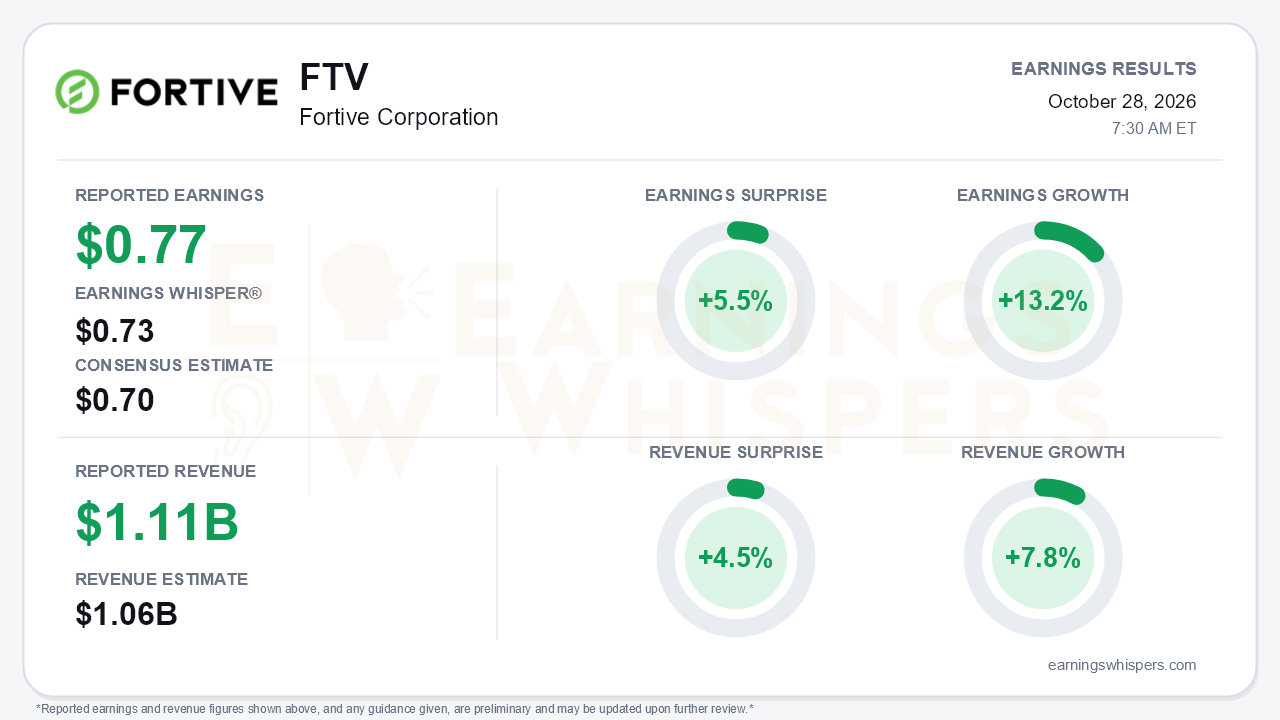
Fortive (NYSE: FTV) delivered another quarter of accelerating revenue and a second consecutive guidance raise. Adjusted earnings of $0.77 per share topped the $0.70 consensus by 5.5% and cleared the $0.73 Earnings Whisper number. Revenue of $1.108 billion beat the $1.06 billion consensus by 4.5%. Revenue grew 7.8% year over year, and core growth reached 7.2%, extending a clean progression from roughly 3% in Q4 2025 to 5.3% in Q1 and 6.7% in Q2. Earnings growth tells a different story. Adjusted EPS rose 13.2%, down sharply from 28% in Q2 and 25% in Q1 as comparisons toughened. That is the central tension: the top line is accelerating while per-share earnings growth is decelerating and increasingly dependent on capital allocation.
The quality of the beat deserves scrutiny. Adjusted net earnings rose only about $7 million, to $235.4 million. Diluted shares fell from 333.4 million to 303.9 million, so the roughly $2.3 billion of cumulative buybacks, about 13% of shares, did much of the work behind the 13% EPS gain. Net interest expense also climbed to $38.8 million from $25.4 million as long-term debt rose to $3.51 billion, which partly offset stronger operating profit. On the positive side, management did not flatter adjusted results with one-time gains. It excluded an $18 million IEEPA tariff refund, worth $0.06 per share, from adjusted EPS. The 62.9% jump in GAAP EPS to $0.57 largely reflects lapping roughly $38 million of separation-related charges from the year-ago quarter rather than a step change in profitability. Adjusted EBITDA grew 9.5%, and margin expanded a modest 50 basis points to 30.6%.
Beneath the headline, the two segments are moving in opposite directions. Intelligent Operating Solutions was the engine:
- **Growth:** core revenue rose 9.1%, up from 7.4% in Q2.
- **Profitability:** adjusted EBITDA grew 13.6%, and margin widened 120 basis points to 35.8%.
- **Fluke:** orders accelerated again, with book-to-bill above 1. Management said data center demand is limited by its supply of specialized sales talent rather than by customer appetite.
- **Other businesses:** ServiceChannel and Gordian accelerated, and gas detection grew sequentially.
- **Geography:** EMEA returned to growth after declining in Q2.
Advanced Healthcare Solutions went the other way. Core growth slowed to 3.1% from 5.3% in Q2. Adjusted EBITDA fell 4.8%, and margin compressed 230 basis points, about 100 basis points of which reflected lapping discrete prior-year benefits. Management did describe U.S. hospital capital spending as stable to improving. Consolidated gross margin slipped 80 basis points to about 63%, the third straight quarter of mix-driven pressure from lower-margin ServiceChannel pass-through revenue and emerging-market consumables.
The guidance raise was substantive. Fortive lifted full-year adjusted EPS guidance to $3.10 to $3.14, from $2.95 to $3.05, implying about 15% growth at the midpoint. Other targets moved up as well:
- Full-year core growth is now expected just above 5%, versus about 4% in Q2 and 2% to 3% at the start of the year. That is ahead of the company's 3% to 4% medium-term framework.
- Reported revenue is now expected just above $4.4 billion.
- EBITDA margin expansion is guided to the midpoint of the 50 to 100 basis point range.
The company also raised its quarterly dividend 17% and launched products including iNet Insights and ServiceChannel's AI-enabled R2 release. Bears still have legitimate ammunition. The outlook implies roughly flat Q4 core growth, given a 150 basis point selling-day headwind and a tougher comparison. Component, memory and freight inflation is rising, although price/cost remains positive. China remains choppy. The expected tariff refund was cut to $5 million to $10 million from $20 million to $25 million, and full-year net interest expense was nudged up to about $145 million.
Investor expectations have improved but remain cautious. Earnings Whispers sentiment rose from -0.26 at the prior report to -0.08, a meaningful improvement that still leaves investors slightly negative on balance. The shares followed a similar arc. The stock peaked at $62.75 on the day of the July report and slid to $54.13 by September 10. It then recovered to $61.62, essentially flat (-1.0%) from the post-report open, 1.8% below the quarter high and 5.3% above its 200-day moving average. Fortive therefore entered this report near the top of its range after a full rebound, which raises the bar for an incremental reaction. The Earnings Whispers trend signals are mostly positive, with sequential growth the notable neutral reading.
The bottom line is that Fortive's growth story is gaining credibility. Core growth has accelerated through four straight reported quarters, IOS is firing, and guidance keeps moving higher. The earnings picture is less pristine than the beat implies. Share reduction is carrying a large share of EPS growth, AHS is losing momentum, gross margin remains under mix pressure, and the guide points to a flat fourth quarter. Investors are paying for acceleration. The next test is whether IOS strength and Fluke's order momentum can carry into 2027 once the buyback tailwind and easy comparisons fade.
Read our earnings preview for Fortive Corporation: https://www.earningswhispers.com/article/FTV/20848
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 9 hours | |
| 11 hours | |
| 12 hours | |
| 16 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-15 |
