Essex Misses The Whisper By A Penny Or Five, But A Surging 2027 Earn-In And Northern California Rent Gains Matter More
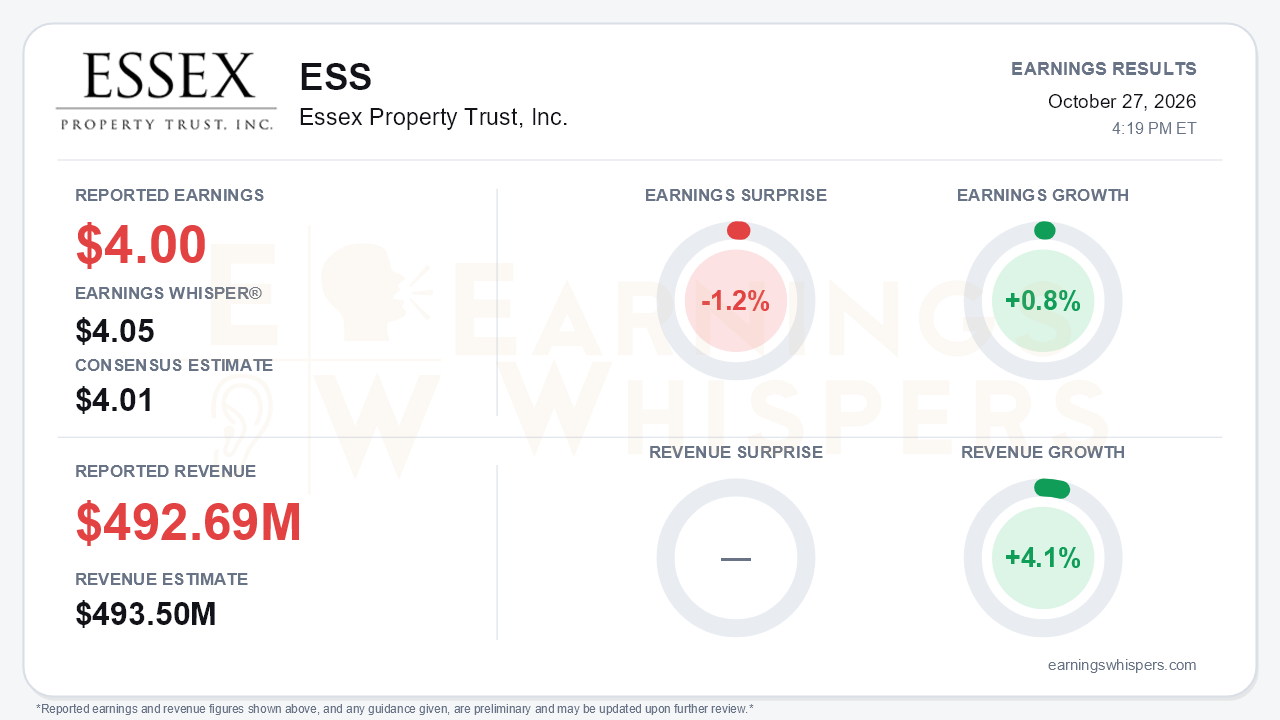
Essex Property Trust's third quarter was a narrow miss against Wall Street that management still framed as a beat against its own plan. Core FFO of $4.00 per share fell a penny short of the $4.01 consensus and well short of the $4.05 Earnings Whisper number, a 1.2% shortfall. Revenue of $492.69 million missed by 0.2% while growing 4.1% year over year. Core FFO grew just 0.8%, behind the 1.6% pace for the first nine months. Yet the $4.00 topped the midpoint of Essex's own guidance by $0.01, and full-year guidance rose for a third straight quarter. That is the central tension. The reported quarter was flat and slightly light, while the forward setup for 2027 improved meaningfully.
The headline GAAP comparison looks worse than the operations. Net income fell to $1.52 per share from $2.56, but that decline mostly reflects large real estate gains booked a year ago. The current quarter also carried a $10.7 million impairment. Total FFO dipped 1.2% to $3.98. Same-property revenue rose 3.0% and NOI 3.1%, and financial occupancy held at 96.3%, up from 96.0% a year earlier. Beneath that, the results split sharply by region:
- **Northern California:** revenue rose 5.4% and NOI 7.0%. San Francisco grew 8.0% and San Mateo 6.6%.
- **Southern California:** revenue managed only 1.5%, with Los Angeles at 0.5%.
- **Seattle:** revenue rose 1.3%, while NOI slipped 0.4% as expenses climbed 5.3%.
Sequentially, same-property revenue grew 1.0%, but operating expenses jumped 6.7% and NOI fell 1.3%. The quality of the quarter therefore rests on Bay Area pricing power, not on broad-based strength.
The call is where the bull case got sharper.
- **Northern California leasing:** blended lease rates climbed from 3.2% in the first quarter to 6.5% in the second and 7.3% in the third. New-lease rates improved 20 basis points sequentially, against a normal seasonal slowdown, and October new leases in the region ran above 10%.
- **Embedded growth:** loss-to-lease reached 1.4% in September, about 8% in Northern California, compared with a 30-basis-point gain-to-lease a year ago. Management now puts the 2027 earn-in at roughly 155 to 160 basis points, versus about 85 basis points entering 2026.
- **Guidance:** full-year blended rent growth is now about 2.9%, up from 2.5%. The same-property revenue midpoint rose to 2.9%, from an original 2.4%, and the NOI midpoint to 3.0%, from 2.1%.
- **Tone:** management's language moved from macro-hedged caution earlier in the year to an openly constructive multi-year West Coast thesis.
Bears still have legitimate ammunition, and much of it points at 2027 earnings rather than revenue.
- **Interest expense:** about $496 million of joint-venture swaps reset from 2.7% to 5.3%, which management estimates adds roughly $0.10 to $0.12 of interest expense. The new $275 million term loan, priced at SOFR plus 0.80%, is unhedged, and about 20% of JV swaps are left floating.
- **Property taxes:** growth is expected to return to 3% to 4% after just 0.6% in 2026, which was aided by one-time Prop 8 appeals.
- **Near-term momentum:** fourth-quarter renewals are guided to the mid-4% range, down from 5.3%, with opex up about 5% year over year.
- **Implied fourth quarter:** the Q4 Core FFO midpoint of $4.01 implies essentially no sequential progress.
- **Raise size:** the $0.02 Core FFO raise was a fraction of the second quarter's $0.20 increase. Guidance remains in line with Street estimates rather than ahead of them.
- **Market overhangs:** Los Angeles continues to decelerate. Seattle faces Microsoft and legislative overhangs. California policy risks include a wealth tax ballot measure.
On the capital side, the release disclosed the post-quarter acquisition of a 378-unit Oakland community following the liquidation of a $64.2 million subordinated loan interest. Essex has not accrued income on that investment since the third quarter of 2025. Separately, the call cited a roughly $200 million-plus purchase of a 474-unit, 2022-vintage East Bay asset at a mid-5% yield, below replacement cost. Both deals show Essex leaning into its strongest market. Liquidity tops $1.7 billion.
Investors have not been rewarding the improving rent story. Earnings Whispers sentiment turned more negative, falling from -0.09 to -0.27, a meaningful though not extreme deterioration. At $274.85, shares are down 5.2% since the open following the July report and sit only about 2% above the 200-day moving average of $269.48. Price trend readings are neutral and the AVWAP trend is negative, consistent with a stock that has drifted rather than broken down. The market appears to be weighing the interest-rate and tax drag on 2027 per-share growth at least as heavily as the rent acceleration.
The bottom line is that Essex delivered a soft quarter on the numbers, missing the whisper and growing Core FFO less than 1%. Even so, it exited the quarter with the strongest forward revenue setup it has had in years, driven by Northern California pricing and a near-doubling of the 2027 earn-in. The question for investors is how much of that revenue tailwind survives higher financing costs and normalizing property taxes on the way to per-share earnings.
Read our earnings preview for Essex Property Trust, Inc.: https://www.earningswhispers.com/article/ESS/20754
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-06 | |
| Sep-11 | |
| Sep-03 | |
| Aug-27 | |
| Aug-06 | |
| Aug-06 | |
| Aug-03 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 |
