Prosperity Bancshares Beats On Stellar-Fueled Margin Expansion, But Flat 2027 Loan Outlook And Rising NPAs Keep Investors Skeptical
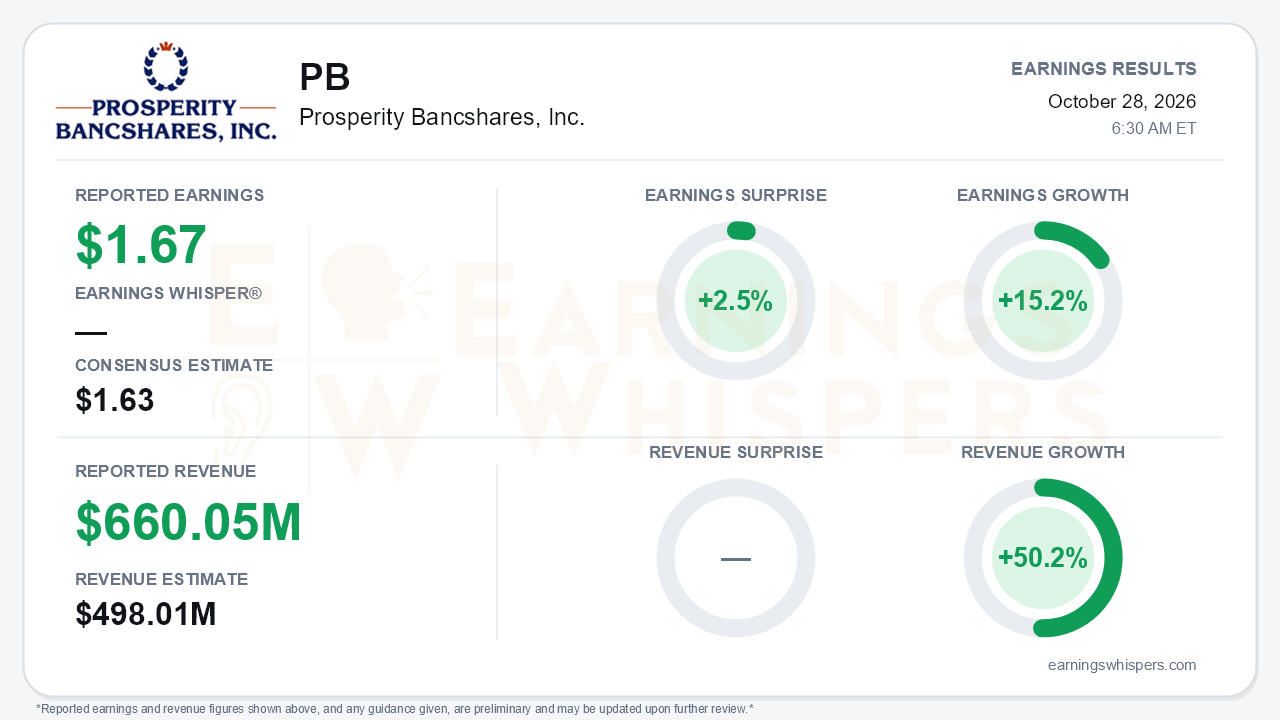
Prosperity Bancshares delivered the merger payoff it promised, even if shareholders are not yet treating it that way. Adjusted EPS of $1.67 topped the $1.63 consensus by 2.5% and grew 15.2% year over year. Revenue of $660.05 million beat expectations by 32.5% and rose 50.2% from a year ago, reflecting Stellar Bank's first full quarter inside the franchise. The central tension is that the margin and earnings-power story improved materially, while the balance-sheet growth story was reset lower. Management now expects 2027 loans to be flat to only slightly up.
The quality of the beat deserves some scrutiny, starting with the GAAP-versus-adjusted gap. GAAP diluted EPS was $1.18, down from $1.45 a year ago and $1.67 in the second quarter. Two items drove the difference: $69.7 million of merger expenses, or $0.46 per share, and a $5.0 million out-of-state tax settlement, or $0.04, which pushed the effective tax rate to 24.4%. Dilution is the other important caveat. Weighted diluted shares jumped to 119.9 million from 95.1 million a year earlier after three stock-funded deals. That explains why adjusted net income of $200.8 million rose far faster than per-share earnings. Tangible book value per share also fell to $39.71 from $43.48 in June, and CET1 dropped to 13.46% from 15.94%. Both remain solid levels, but they show that the acquisitions consumed real capital.
The operating trend beneath those items is genuinely better. Tax-equivalent net interest margin climbed 26 basis points sequentially to 3.73%, up from 3.24% a year ago. Net interest income rose 34% from the prior quarter to $443.0 million. Purchase accounting helped, with loan discount accretion of $11.6 million in the quarter. Even so, management cited a core margin excluding those adjustments of 3.59%, up from 3.41% in the second quarter, so this was not purely an accounting lift. Loan yields rose to 6.08% and securities yields improved to 2.92% as the portfolio continued to reprice. Excluding merger costs, the efficiency ratio was 48.03%. Management also pointed to another $65-70 million of pre-tax cost saves, targeting a $220-225 million quarterly expense run rate by mid-2027. Average monthly loan production accelerated to $635 million from $454 million in the second quarter and $312 million in the first.
The forward guidance cuts both ways. Management nudged its fourth-quarter exit margin guidance to 3.70-3.75% and guided to a 3.80-3.85% average margin for 2027. That 2027 guide assumes flat rates, which leaves room for upside on a modestly asset-sensitive balance sheet. On the call, executives framed 2027 EPS growth in the mid-teens and 2028 growth in double digits. They also emphasized buybacks over near-term M&A, with the stock trading under 10x earnings. Bears, however, have legitimate ammunition:
- **Funding costs.** Deposit rates were raised after the Fed hike, and cost of deposits is expected to rise 6-7 basis points in the fourth quarter.
- **Accretion.** Loan accretion should fall to $7-10 million, so the fourth-quarter margin is guided only flat to slightly up.
- **Warehouse balances.** These are expected to slide to an $850-900 million average from $1.23 billion.
- **Credit.** Nonperforming assets rose to $193.9 million, or 0.60% of loans and ORE, from $130.6 million in June, largely on acquired loans. The Stellar credit mark also came in above the deal-time estimate. Management expects NPAs to settle at $125-150 million, but that is a projection rather than a result.
- **Loan growth.** Strong production is still being offset by post-acquisition runoff, which drives the flat 2027 outlook.
Investors entered the report in a sour mood. Earnings Whispers sentiment deteriorated meaningfully, from -0.20 at the prior report to -0.43. Shares at $69.64 were down 4.5% from the $72.90 open following the July report and sat about 1% below the 200-day moving average of $70.33. The stock has given back much of its early-August run to $75.87 but has also recovered roughly 7% from its October 1 low of $65.14. That leaves it near the middle of its inter-earnings range. The price and AVWAP trend readings remain negative, consistent with a market that has been treating integration risk more seriously than accretion upside.
The bottom line is that Prosperity's third quarter strengthened the earnings-power argument: a 3.73% margin, a clear cost-save path, faster loan production, a 6.7% dividend increase, and management targeting mid-teens EPS growth next year. Against that, investors must weigh heavy share dilution, lower tangible book value, rising acquired-loan NPAs, and a balance sheet that will not grow much in 2027. The setup is more complicated than the beat implies. The upside case now depends on executing the Texas Partners and Stellar conversions on schedule and converting margin expansion into per-share growth, not on balance-sheet expansion.
Read our earnings preview for Prosperity Bancshares, Inc.: https://www.earningswhispers.com/article/PB/20873
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Sep-30 | |
| Sep-15 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 | |
| Jul-01 | |
| Jun-30 | |
| Jun-29 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 |
