Iovance's Raised Outlook Implies A Bigger Third Quarter Than Wall Street Models
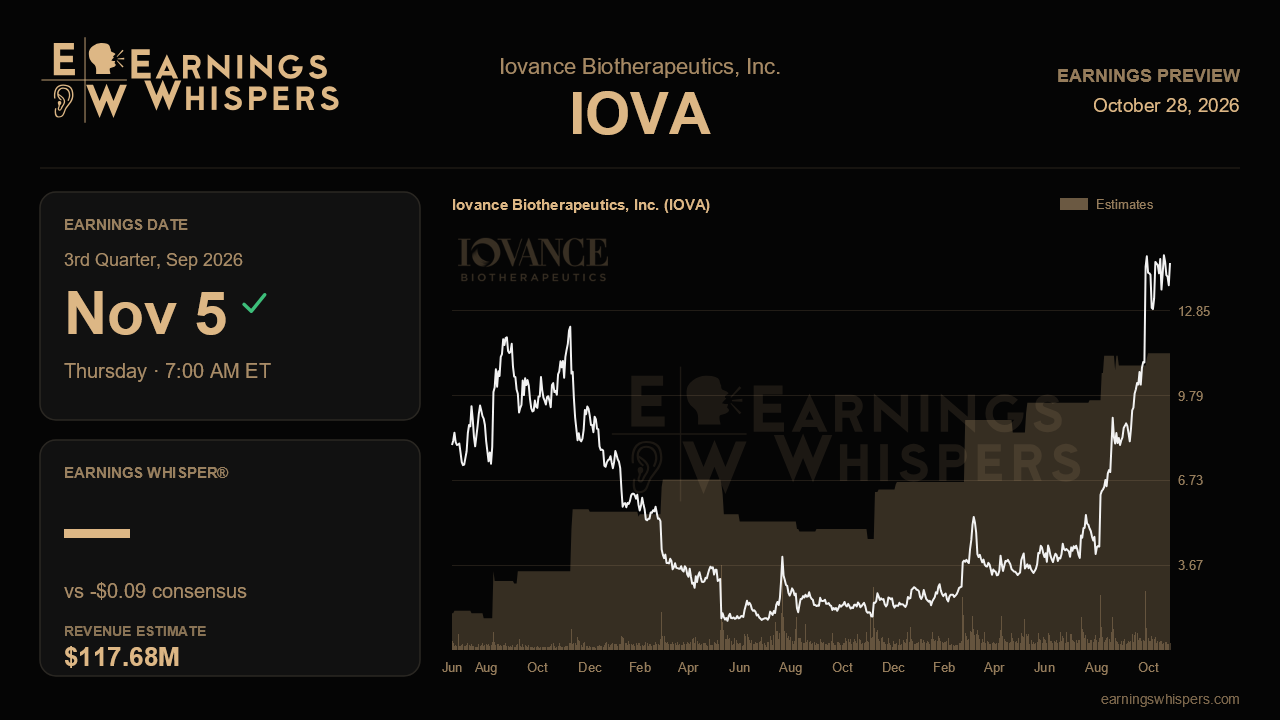
Iovance Biotherapeutics enters its third-quarter report with an unusual problem for a cell therapy company: its own forecast looks more ambitious than Wall Street's. After management lifted its 2026 revenue outlook to $410 million to $420 million from $350 million to $370 million, the full-year consensus of $399.4 million still sits below the bottom of that range. The quarter due before the open on November 5 will show whether the Street is being prudent or simply hasn't caught up.
Analysts expect revenue of $117.7 million, up 74.5% from $67.5 million a year ago and roughly 18% above the second quarter's $99.3 million. The projected loss of 9 cents a share would mark a 64% improvement from the year-ago loss of 25 cents and a modest step from last quarter's 11-cent loss. The arithmetic behind guidance is what makes the setup interesting. First-half revenue came to about $170 million, so hitting even the low end of the new range requires around $240 million in the back half, or roughly $120 million a quarter. A $117.7 million print would therefore be respectable but not quite on pace, leaving the company leaning on a strong fourth quarter. A number comfortably above $120 million would suggest the raised range is conservative rather than stretched.
The second-quarter call gave the bull case its strongest evidence yet. Amtagvy generated about $91 million against guidance of $79 million to $81 million, and total revenue beat the company's own target by more than $11 million. The demand indicators behind that beat matter more than the beat itself: more than 50 commercial patients treated per month, unaided physician awareness up about threefold from a year earlier, and an authorized treatment center network above 95 sites with a goal of 110 or more by year-end. Community centers now make up a third of that network, which matters because broadening beyond academic hubs is how a complex, single-patient therapy scales. Confirmation this quarter would come from a higher monthly patient count and steady progress toward the 110-site target. Any stall in either would challenge the idea that the second quarter marked a true inflection rather than a catch-up after first-quarter facility maintenance.
Margins are the next test. Gross margin reached a record 56%, up from 41% in the first quarter and 50% at the end of 2025, while R&D spending fell for a fourth straight quarter and SG&A held near $39 million despite sharp revenue growth. Holding gross margin in the mid-50s with flat operating costs would validate the operating leverage story and explain why losses are narrowing. Slippage back toward the 40s would raise questions about manufacturing consistency. Prolucan, which dipped to about $9 million on wholesaler inventory timing, should rebound if management's expectation that it settles near 16% of total revenue holds. Cash of $304 million, which management says funds operations into the second half of 2028, also deserves a look given past reliance on at-the-market share sales.
Expectations have clearly reset. The stock has surged 145% since the last report while the S&P 500 was essentially flat, and at $14.58 it trades far above its 200-day average of $5.69 and near the top of a post-earnings range of $5.63 to $15.37. Sentiment has improved to modestly bullish from barely positive heading into the prior quarter. That rally means the market is already paying for continued execution, and pipeline items such as the Lung 202 update expected in the fourth quarter, the SAR201 Fast Track designation and the frontline melanoma data add optionality but will not cushion a commercial wobble.
The central question is whether Amtagvy's patient and site growth is running fast enough to make the raised guidance look easy. A quarter at or above $120 million, with stable margins and a reaffirmed or higher range, would keep the narrative intact. Anything that leaves the fourth quarter carrying too much of the load would invite a reassessment of a stock that has already moved a long way.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-25 | |
| Oct-23 | |
| Oct-23 | |
| Oct-19 | |
| Oct-16 | |
| Oct-01 | |
| Sep-29 | |
| Sep-29 |
